CORPORATE PRESENTATION DATED OCTOBER 2026
Published on October 2, 2026
Exhibit 99.1
Critical Materials Critical Processes Critical Engineering Critical Manufacturing Securing Critical Components Supply Chain October 2026
Disclaimer 2 FORWARD-LOOKING STATEMENTS The information in this Presentation includes "forward-looking statements" within the meaning of the Private Securities Litigation Reform Act of 1995, as amended. All statements other than statements of historical fact included in this presentation regarding our business strategy, plans, goals, and objectives are forward-looking statements. When used in this presentation, the words "believe," "project," "expect," "anticipate," "estimate," "intend," "budget," "target," "aim," "strategy," "plan," "guidance," "outlook," "intent," "may," "should," "could," "will," "would," "will be," "will continue," "will likely result," and similar expressions are intended to identify forward-looking statements, although not all forward-looking statements contain such identifying words. These forward-looking statements are based on the current expectations of The Elmet Group Co. ("we," "us," "our," or the "Company") and assumptions about future events and are based on currently available information as to the outcome and timing of future events. We caution you that these forward-looking statements are subject to all the risks and uncertainties, most of which are difficult to predict and many of which are beyond our control, associated with our business of critical materials components, critical materials refining and trading, and high-powered microwave engineering and manufacturing. These risks include, but are not limited to: our market opportunities and the potential growth of those markets; our strategy, expected outcomes and growth prospects; trends in our operations and industry markets; our ability to execute our growth strategy, including becoming a U.S. leader in the critical materials supply chain, and successfully acquire and integrate potential acquisition target, including our ability to complete construction projects on time and within expected costs; our future profitability, indebtedness, liquidity, access to capital and financial condition; our ability to service our current and future indebtedness; an event of default or liquidation under our financing agreements with the Department of War; covenants contained in our financing agreements with the Department of War restricting our ability to take certain actions; dilution and/or the perception thereof; any inability to attract, train or retain employees with the requisite skills and experience; failure by us or our employees to obtain and maintain necessary security clearances or certifications; changes in U.S. government appropriations, procurement, contract or other practices or the adoption by governments of new laws, rules, regulations and programs in a manner adverse to us; the termination or nonrenewal of our government contracts and subcontracts, particularly those contracts with the U.S. government and the Department of War; any inability to satisfy our obligations under offtake agreements; our ability to work effectively with our counterparties; our ability to achieve the anticipated benefits from the Department of War investment in us and related transactions, if at all; availability and volatility in the prices of raw materials and energy; our ability to remain in compliance with extensive laws and regulations that apply to our business and operations; the increased expenses associated with being a public company; changes in estimates used in recognizing revenue; internal system or service failures and security breaches; inherent uncertainties and potential adverse developments in legal proceedings, including litigation, audits, reviews and investigations, which may result in materially adverse judgments, settlements or other unfavorable outcomes; the future trading prices of our common stock; and other risks and uncertainties set forth in our filings that may be made with the SEC from time to time. Should one or more of these risks or uncertainties occur, or should underlying assumptions prove incorrect, our actual results and plans could differ materially from those expressed in any forward-looking statements. No representation or warranty (express or implied) is made as to and no reliance should be placed on, any information, including projections, estimates, targets, or opinions contained herein and no liability whatsoever is accepted as to any errors, omissions, or misstatements contained herein. Please refer to the "Risk Factors" section of the Registration Statement on Form S-1 (File No. 333- 294725), as amended and supplemented, and declared effective by the SEC on April 22, 2026, Part II, Item 1A. "Risk Factors" in our Quarterly Reports on Form 10-Q for the quarters ended April 3, 2026 and July 3, 2026, and our Current Reports on Form 8-K filed with the SEC on September 8, 2026 and September 14, 2026 for more information. You are cautioned not to place undue reliance on any forward-looking statements, which speak only as of the date of this Presentation. Except as otherwise required by applicable law, we disclaim any duty to update and do not intend to update any forward-looking statements, all of which are expressly qualified by the statements in this section, to reflect events or circumstances after the date of this Presentation. This presentation also includes certain forward-looking figures, including Projected Revenue and Projected Gross Margin, that management believes is useful in evaluating the Company's underlying economic trajectory and scalability of the Company's business model once the proceeds of the DoW investment are deployed. These figures are presented in connection with the strategic investments described herein. These figures are not financial measures prepared in accordance with U.S. GAAP and have not been audited or reviewed by the Company's independent auditors. They are provided solely for information purposes in connection with this presentation. Actual future revenue, gross profit, and gross margin may differ materially from these figures due to, among other factors: (1) the prevailing market price of ammonium paratungstate, (2) the timing of, and successful entry into, definitive documentation for the transactions discussed in this presentation, (3) the final terms of the definitive transaction documentation, (4) the completion and on-time ramp-up of key projects related to the DoW investment, including (i) U.S. facility upgrades, (ii) commercial agreements and strategic offtakes, and (iii) the APT refining facility, (5) the closing and long-term expectations of existing operations and the Schwabmünchen facility, (6) cost fluctuations, supply-chain conditions, or operational efficiencies, (7) timing of revenue recognition, (8) changes in customer purchasing behavior, customer cancellations, and demand for our products generally, (9) customer acquisition rates and competitive dynamics, and (10) other risks and uncertainties set forth in our filings that may be made with the SEC from time to time. These figures are included solely to assist investors in understanding management's view of the Company's operating trajectory in the context of the strategic transactions discussed in this presentation. They should not be considered in isolation, as a substitute for, or superior to, the Company's historical financial results prepared in accordance with U.S. GAAP, or as a guarantee of future performance. Investors are strongly encouraged to review the Company's complete financial statements, risk factors and all other information contained in set our filings that have been made and may be made with the SEC from time to time. NON-GAAP FINANCIAL MEASURES In evaluating its business, the Company uses or may use certain non-GAAP measures as supplemental measures to review and assess its operating and financial performance. These measures are commonly used in the manufacturing industry to provide stockholders and potential investors with additional information that excludes unusual or non-recurring items as well as non-cash items that are unrelated to or may not be indicative of the Company's ongoing operating results. These measures may not be comparable to similar measures presented by other companies and should not be viewed as a substitute for measures reported under U.S. GAAP. These non-GAAP financial measures have limitations as analytical tools when assessing the Company's operating and financial performances, and investors should not consider them in isolation, or as a substitute for any consolidated statement of operations data prepared in accordance with U.S. GAAP. The Appendixes at the end of this presentation contain reconciliations to Adjusted Gross Profit, Adjusted Gross Profit Margin, EBITDA, Adjusted EBITDA and Adjusted EBITDA Margin from relevant GAAP metrics. MARKET AND INDUSTRY DATA This Presentation has been prepared by the Company and includes market data and other statistical information from third-party sources, including independent industry publications, government publications or other published independent sources. Although the Company believes these third-party sources are reliable as of their respective dates for the purposes used herein, neither we nor any of our affiliates, directors, officers, employees, members, partners, stockholders or agents make any representation or warranty with respect to the accuracy or completeness of such information. Although we believe the sources are reliable, we have not independently verified the accuracy or completeness of data from such sources. Some data is also based on the Company's good faith estimates, which are derived from our review of internal sources as well as the third-party sources described above. Additionally, descriptions herein of market conditions and opportunities are presented for informational purposes only and there can be no assurance that such conditions will actually occur or result in positive returns.
E x e c u t i v e S u m m a r y
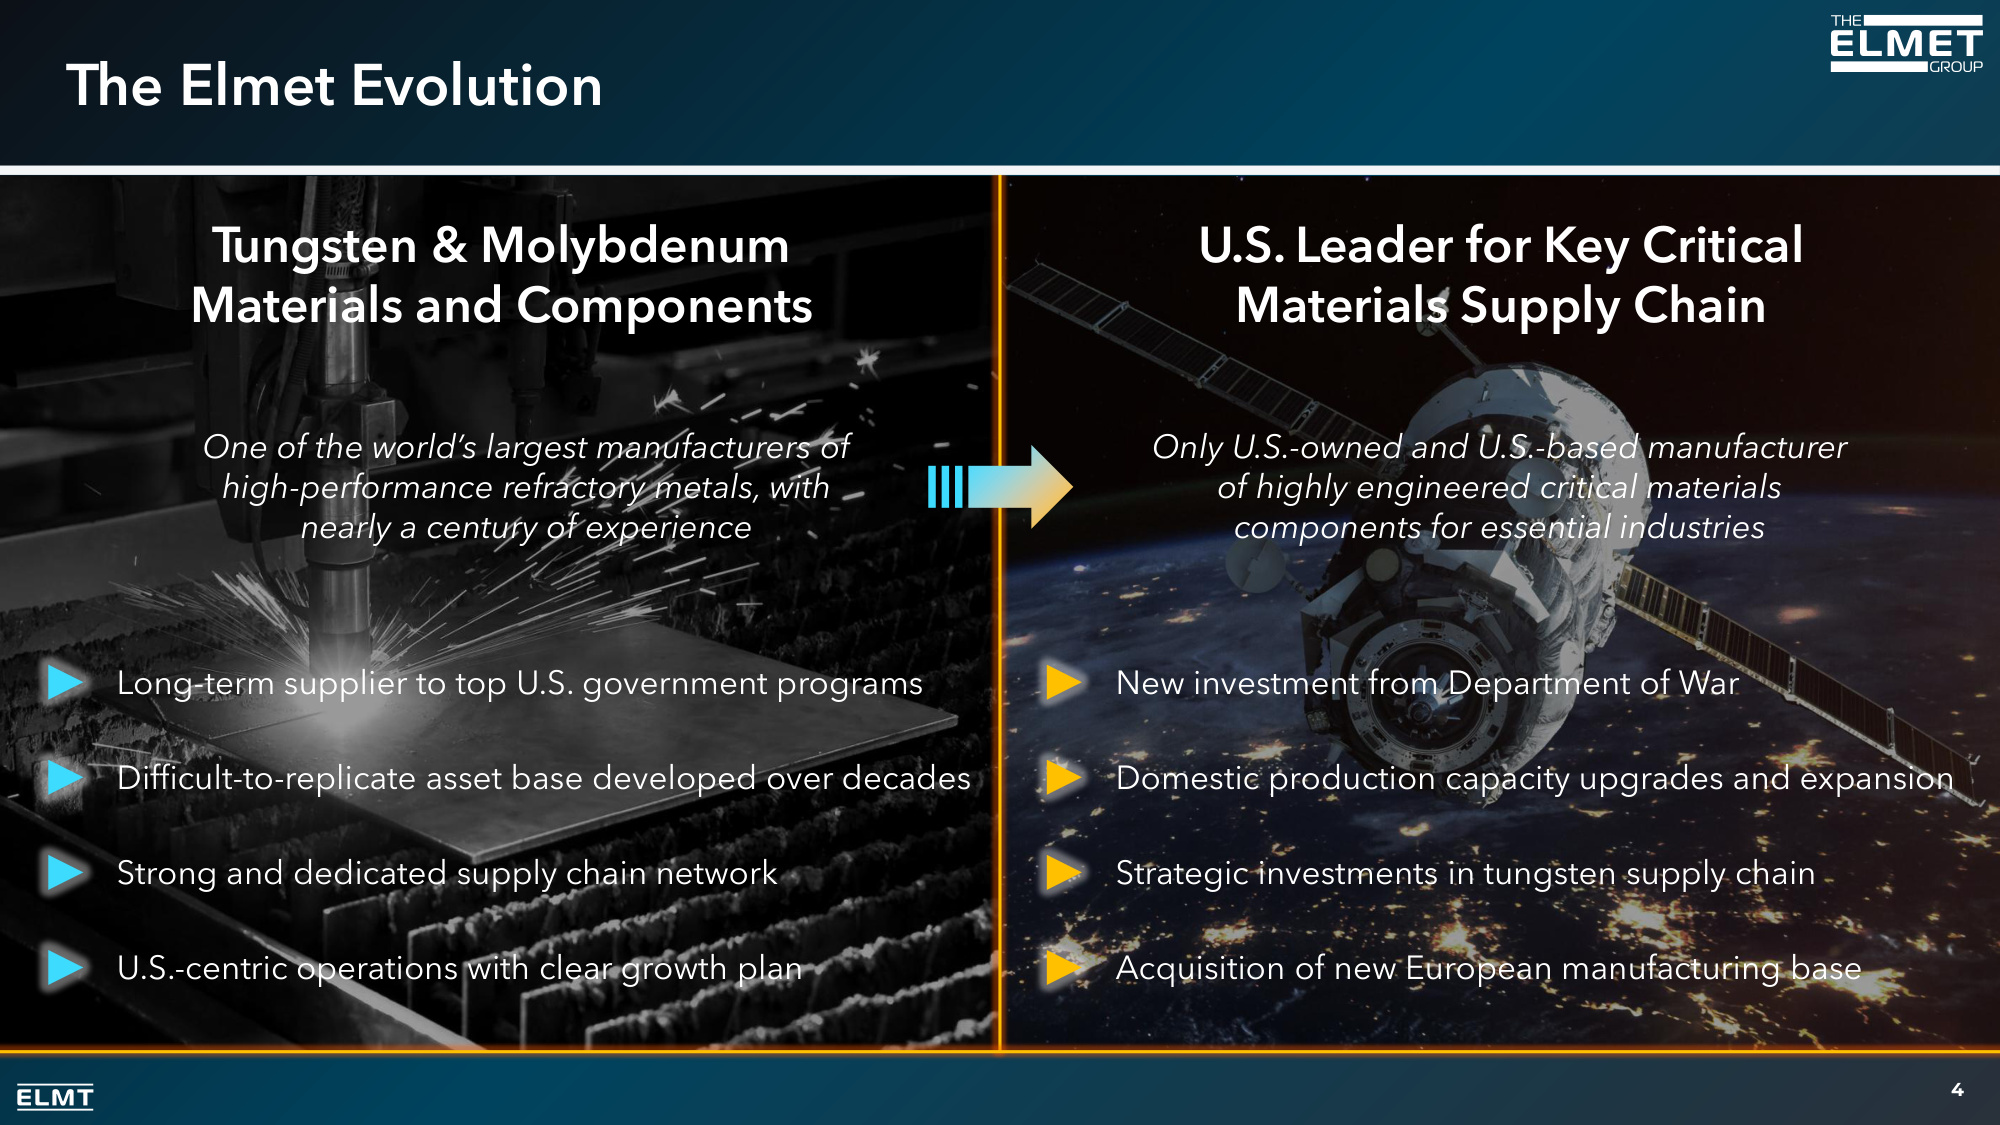
4 Tungsten & Molybdenum Materials and Components U.S. Leader for Key Critical Materials Supply Chain One of the world's largest manufacturers of high-performance refractory metals, with nearly a century of experience Only U.S.-owned and U.S.-based manufacturer of highly engineered critical materials components for essential industries New investment from Department of War Domestic production capacity upgrades and expansion Acquisition of new European manufacturing base Strategic investments in tungsten supply chain Long-term supplier to top U.S. government programs Difficult-to-replicate asset base developed over decades U.S.-centric operations with clear growth plan Strong and dedicated supply chain network The Elmet Evolution
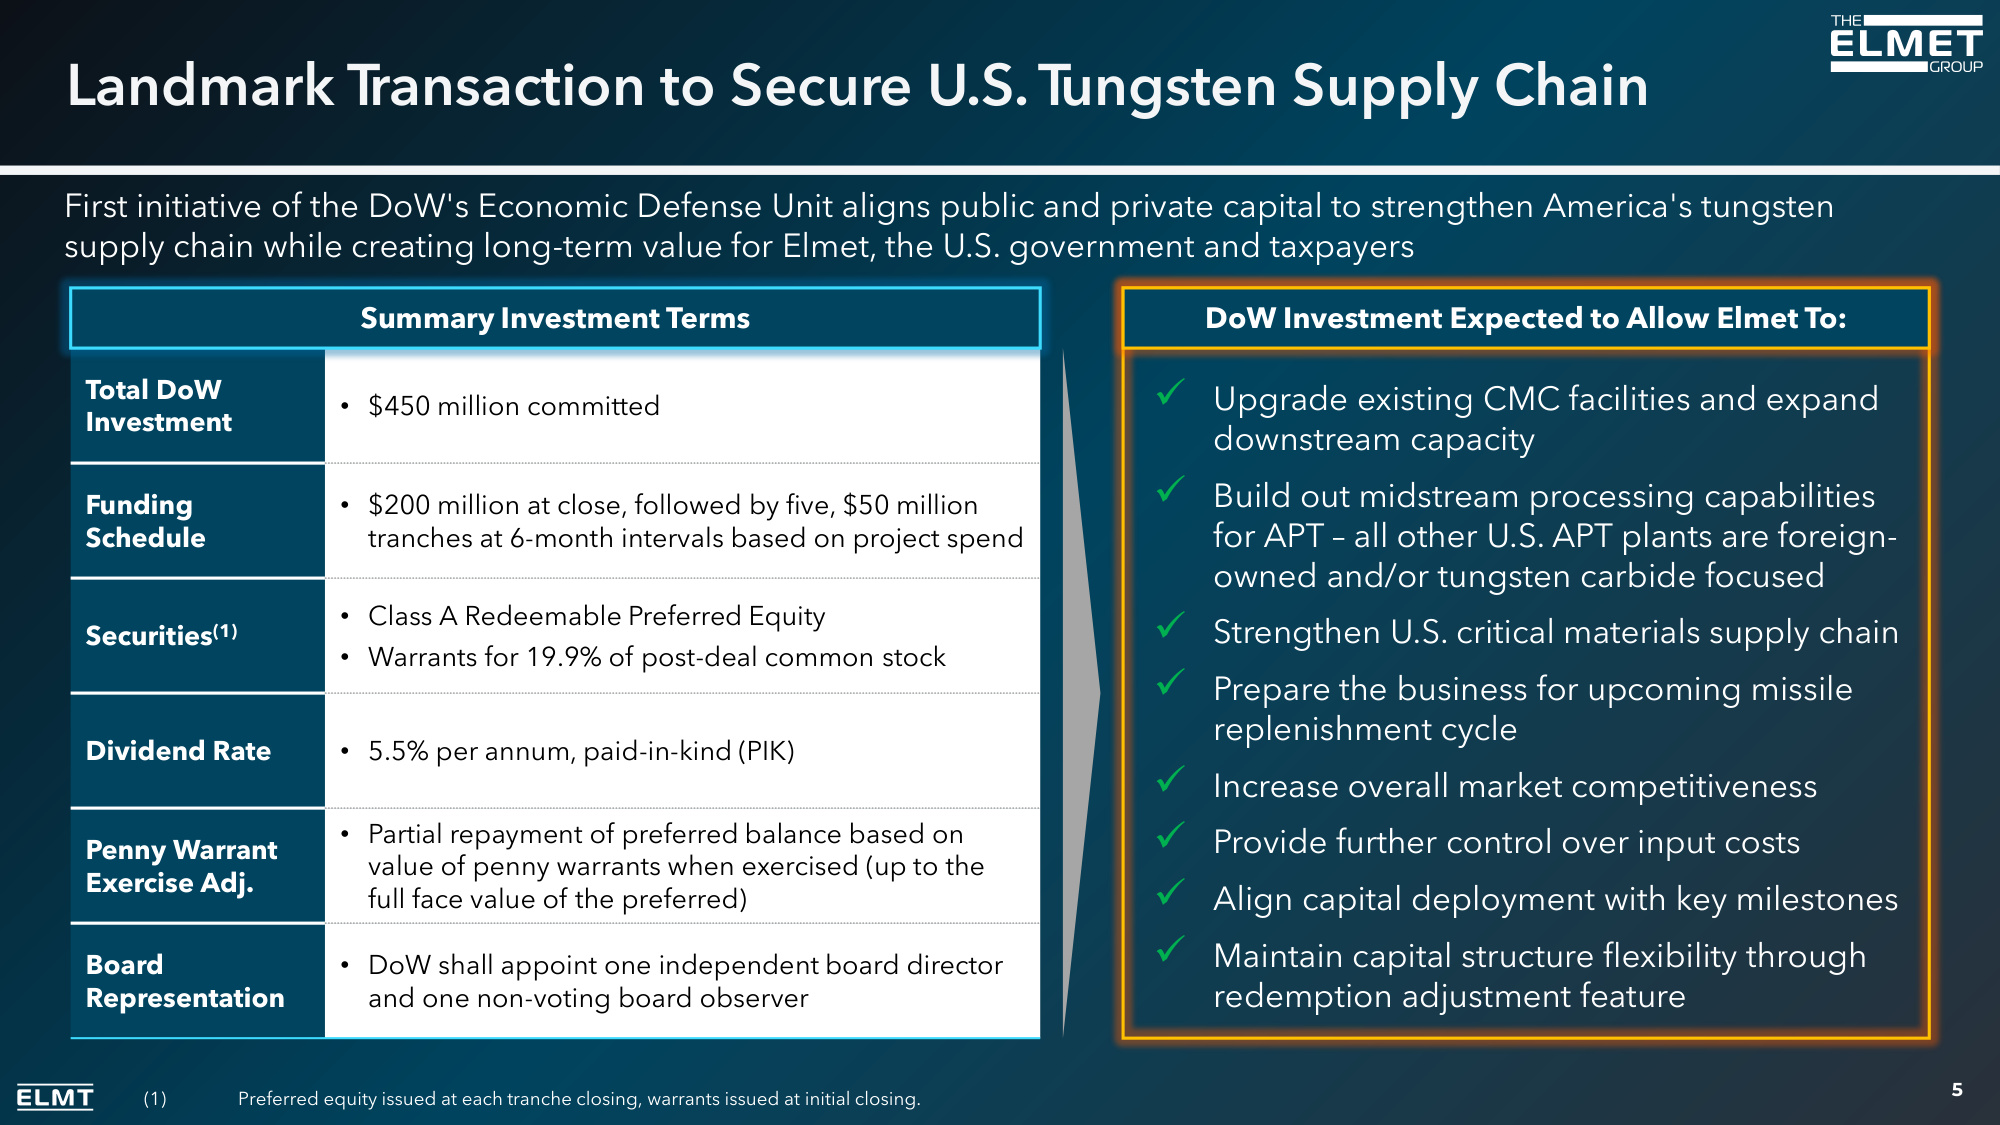
5 Landmark Transaction to Secure U.S. Tungsten Supply Chain ✓ Upgrade existing CMC facilities and expand downstream capacity ✓ Build out midstream processing capabilities for APT – all other U.S. APT plants are foreign- owned and/or tungsten carbide focused ✓ Strengthen U.S. critical materials supply chain ✓ Prepare the business for upcoming missile replenishment cycle ✓ Increase overall market competitiveness ✓ Provide further control over input costs ✓ Align capital deployment with key milestones ✓ Maintain capital structure flexibility through redemption adjustment feature Total DoW Investment • $450 million committed Funding Schedule • $200 million at close, followed by five, $50 million tranches at 6-month intervals based on project spend Securities(1) • Class A Redeemable Preferred Equity • Warrants for 19.9% of post-deal common stock Dividend Rate • 5.5% per annum, paid-in-kind (PIK) Penny Warrant Exercise Adj. • Partial repayment of preferred balance based on value of penny warrants when exercised (up to the full face value of the preferred) Board Representation • DoW shall appoint one independent board director and one non-voting board observer (1) Preferred equity issued at each tranche closing, warrants issued at initial closing. Summary Investment Terms DoW Investment Expected to Allow Elmet To: First initiative of the DoW's Economic Defense Unit aligns public and private capital to strengthen America's tungsten supply chain while creating long-term value for Elmet, the U.S. government and taxpayers
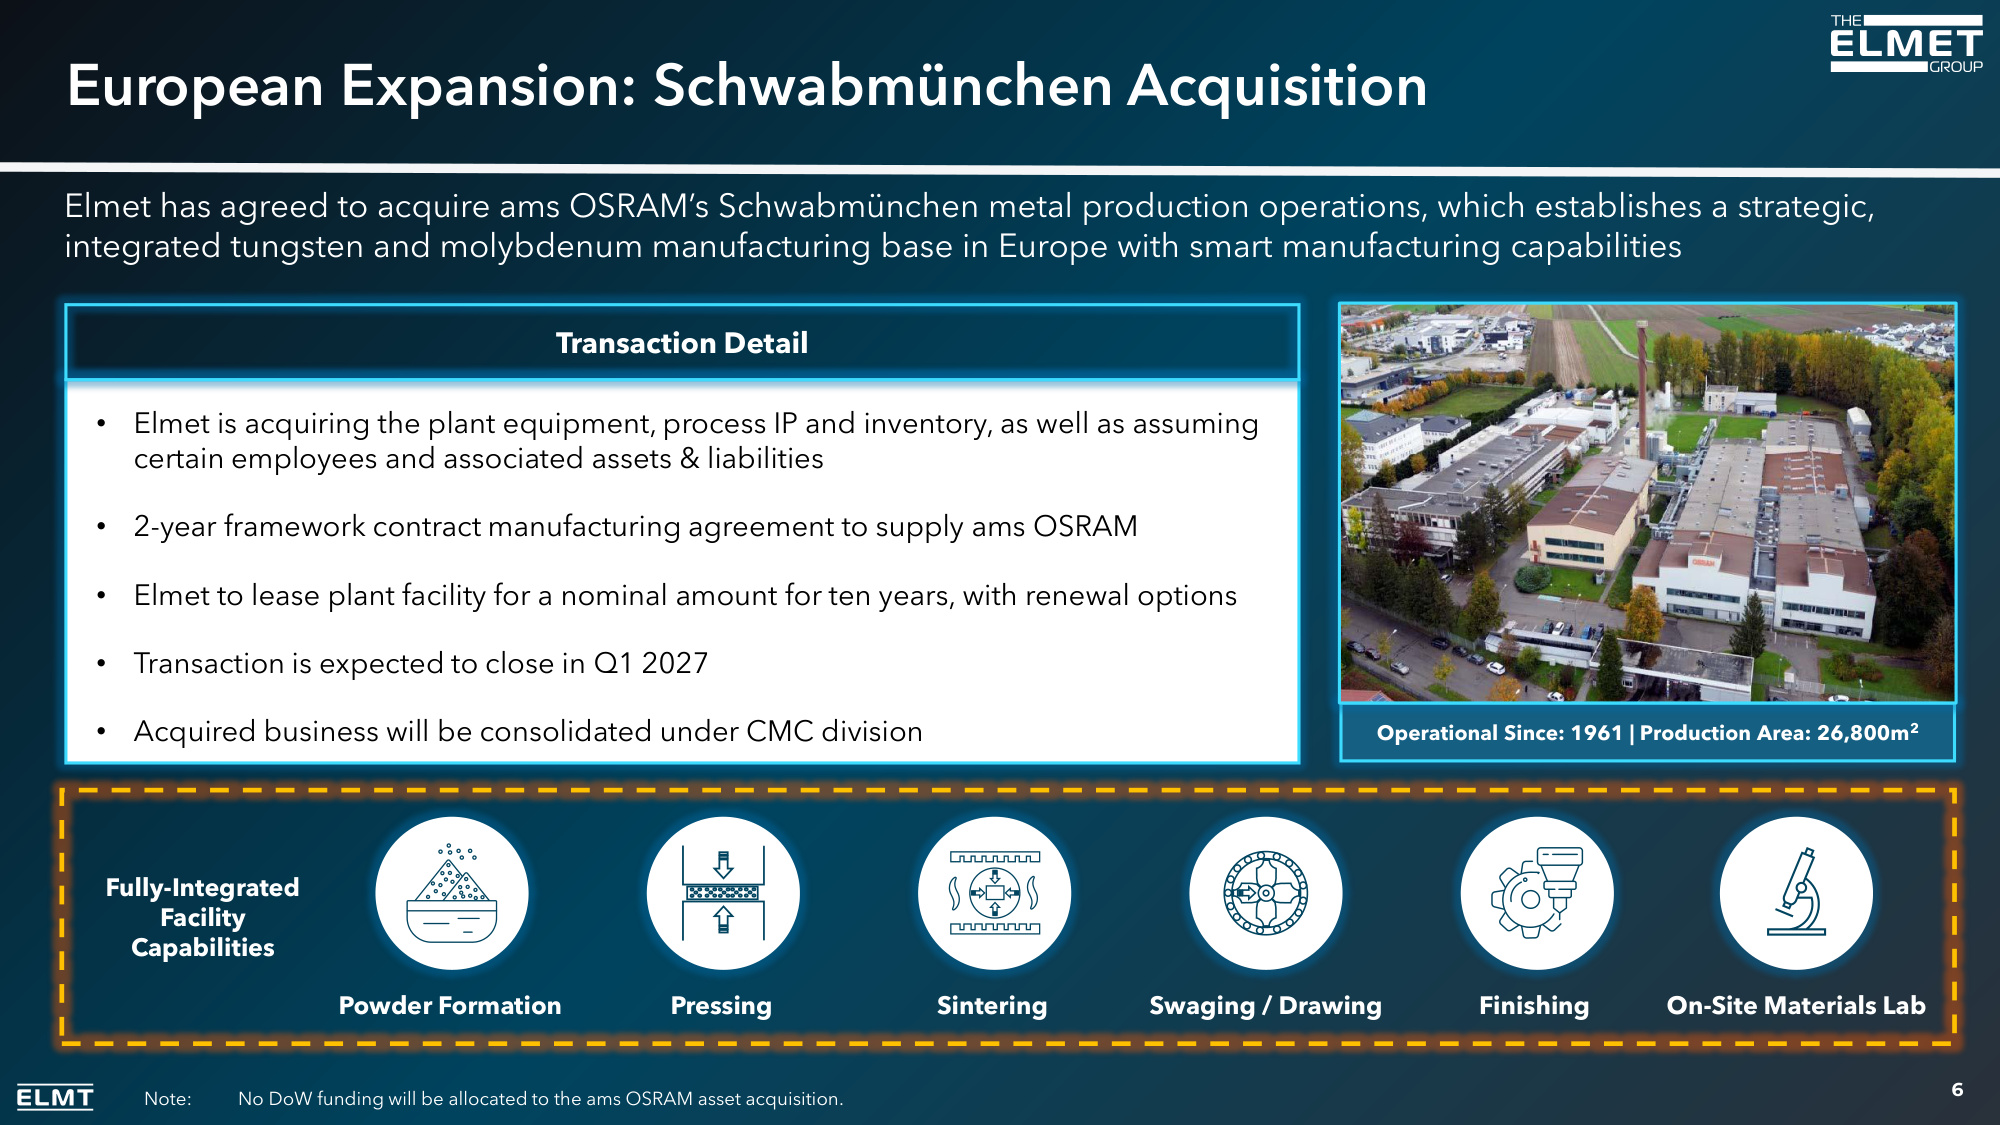
Operational Since: 1961 | Production Area: 26,800m2 European Expansion: Schwabmünchen Acquisition 6 • Elmet is acquiring the plant equipment, process IP and inventory, as well as assuming certain employees and associated assets & liabilities • 2-year framework contract manufacturing agreement to supply ams OSRAM • Elmet to lease plant facility for a nominal amount for ten years, with renewal options • Transaction is expected to close in Q1 2027 • Acquired business will be consolidated under CMC division Transaction Detail Fully-Integrated Facility Capabilities Powder Formation Pressing Sintering Swaging / Drawing Finishing On-Site Materials Lab Elmet has agreed to acquire ams OSRAM's Schwabmünchen metal production operations, which establishes a strategic, integrated tungsten and molybdenum manufacturing base in Europe with smart manufacturing capabilities Note: No DoW funding will be allocated to the ams OSRAM asset acquisition.
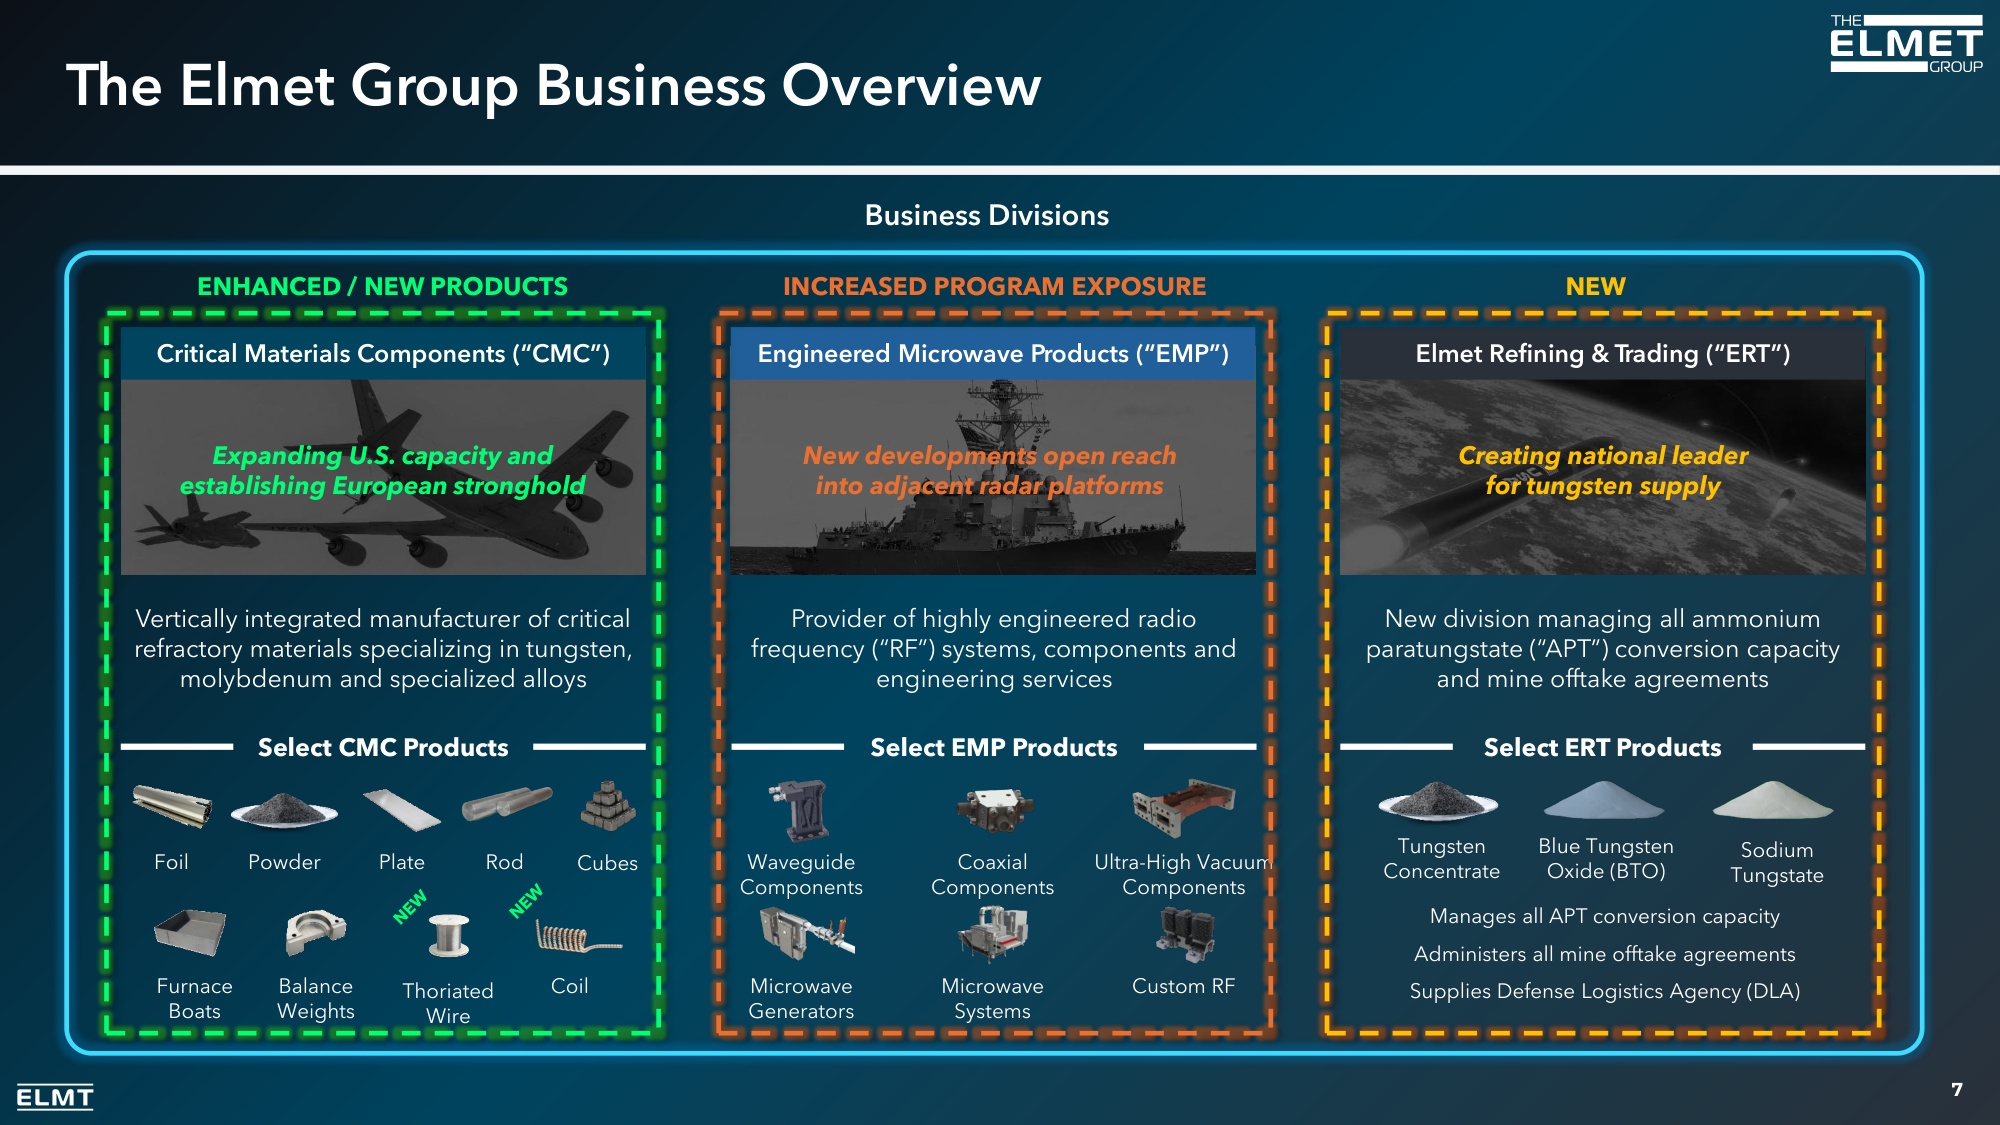
7 The Elmet Group Business Overview Select CMC Products Foil Furnace Boats Balance Weights Cubes Powder Plate Select EMP Products Waveguide Components Coaxial Components Microwave Generators Ultra-High Vacuum Components Microwave Systems Custom RF Critical Materials Components ("CMC") Engineered Microwave Products ("EMP") Vertically integrated manufacturer of critical refractory materials specializing in tungsten, molybdenum and specialized alloys Provider of highly engineered radio frequency ("RF") systems, components and engineering services Elmet Refining & Trading ("ERT") New division managing all ammonium paratungstate ("APT") conversion capacity and mine offtake agreements Select ERT Products Manages all APT conversion capacity Administers all mine offtake agreements Supplies Defense Logistics Agency (DLA) NEW ENHANCED / NEW PRODUCTS Business Divisions Expanding U.S. capacity and establishing European stronghold Creating national leader for tungsten supply Rod Coil Thoriated Wire INCREASED PROGRAM EXPOSURE New developments open reach into adjacent radar platforms Sodium Tungstate Tungsten Concentrate Blue Tungsten Oxide (BTO)
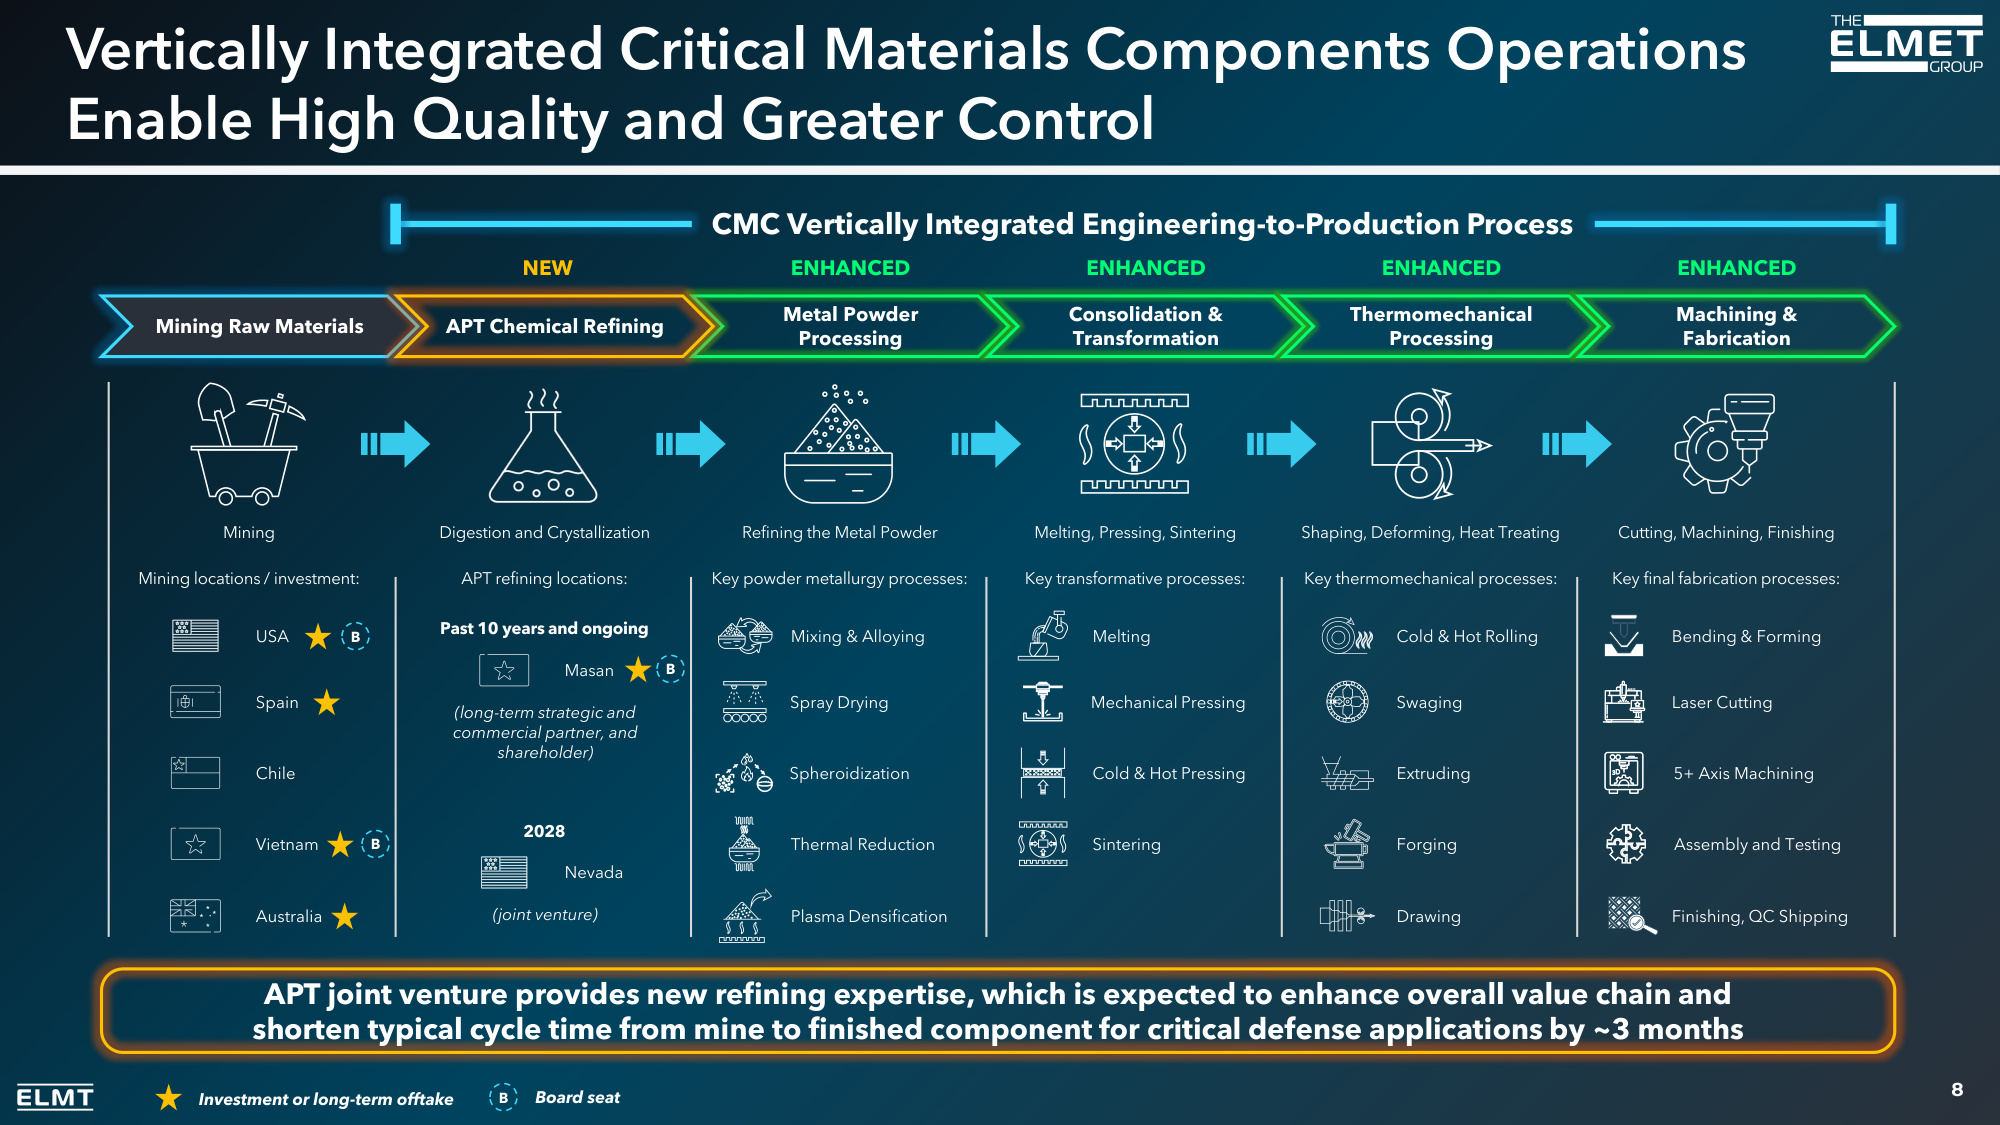
USA 8 Consolidation & Transformation Metal Powder Processing Mining Raw Materials Thermomechanical Processing Machining & Fabrication Shaping, Deforming, Heat Treating Melting, Pressing, Sintering Refining the Metal Powder Mining Cutting, Machining, Finishing Australia Vietnam Spain Chile Mining locations / investment: Mixing & Alloying Key powder metallurgy processes: Spray Drying Spheroidization Thermal Reduction Plasma Densification Key transformative processes: Melting Cold & Hot Pressing Mechanical Pressing Sintering Key thermomechanical processes: Cold & Hot Rolling Swaging Extruding Forging Drawing Key final fabrication processes: Bending & Forming Laser Cutting 5+ Axis Machining Assembly and Testing Finishing, QC Shipping CMC Vertically Integrated Engineering-to-Production Process Vertically Integrated Critical Materials Components Operations Enable High Quality and Greater Control APT Chemical Refining Digestion and Crystallization APT refining locations: Masan Nevada Past 10 years and ongoing 2028 NEW (long-term strategic and commercial partner, and shareholder) (joint venture) Investment or long-term offtake ENHANCED ENHANCED ENHANCED ENHANCED APT joint venture provides new refining expertise, which is expected to enhance overall value chain and shorten typical cycle time from mine to finished component for critical defense applications by ~3 months B B B B Board seat
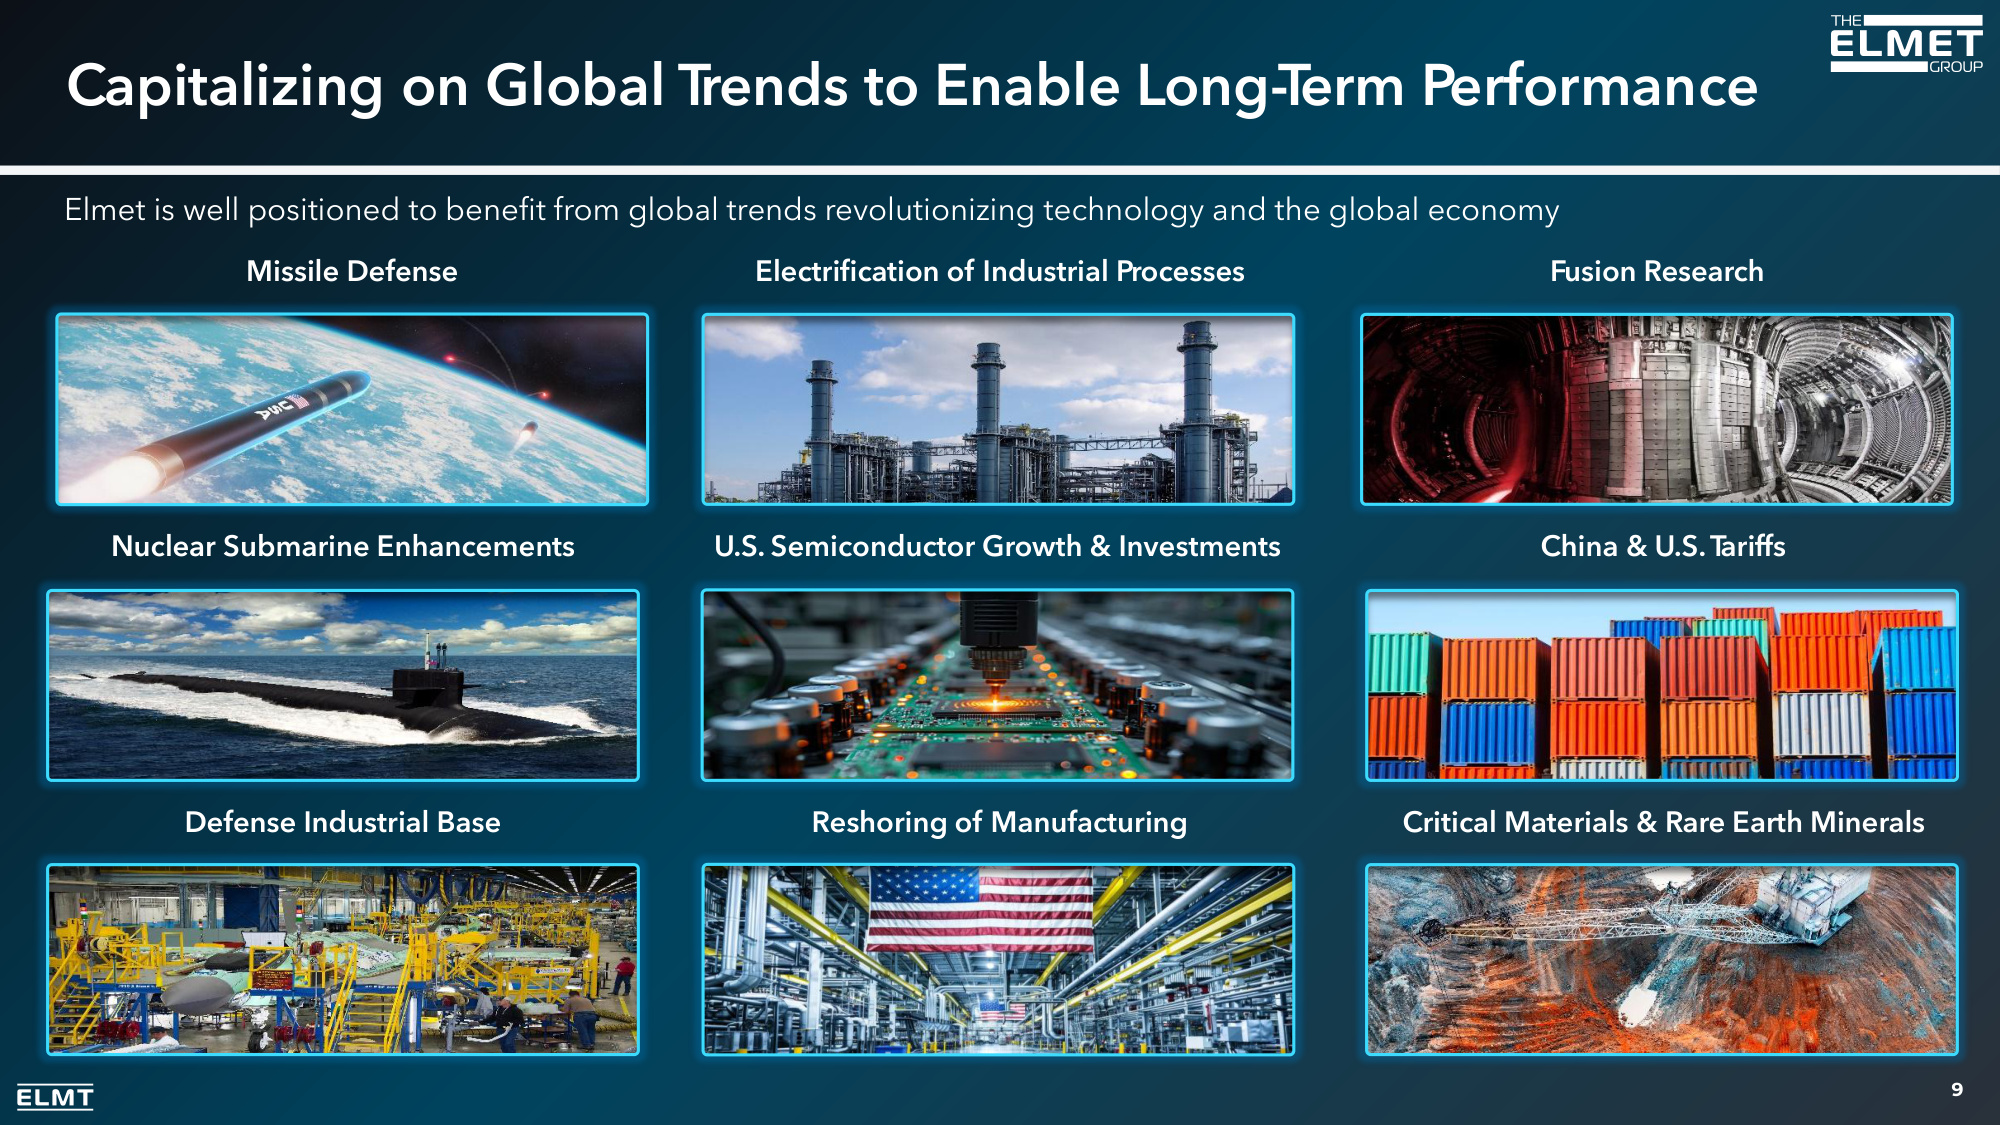
U.S. Semiconductor Growth & Investments Nuclear Submarine Enhancements Defense Industrial Base Electrification of Industrial Processes China & U.S. Tariffs Reshoring of Manufacturing Missile Defense Fusion Research 9 Critical Materials & Rare Earth Minerals Elmet is well positioned to benefit from global trends revolutionizing technology and the global economy Capitalizing on Global Trends to Enable Long-Term Performance
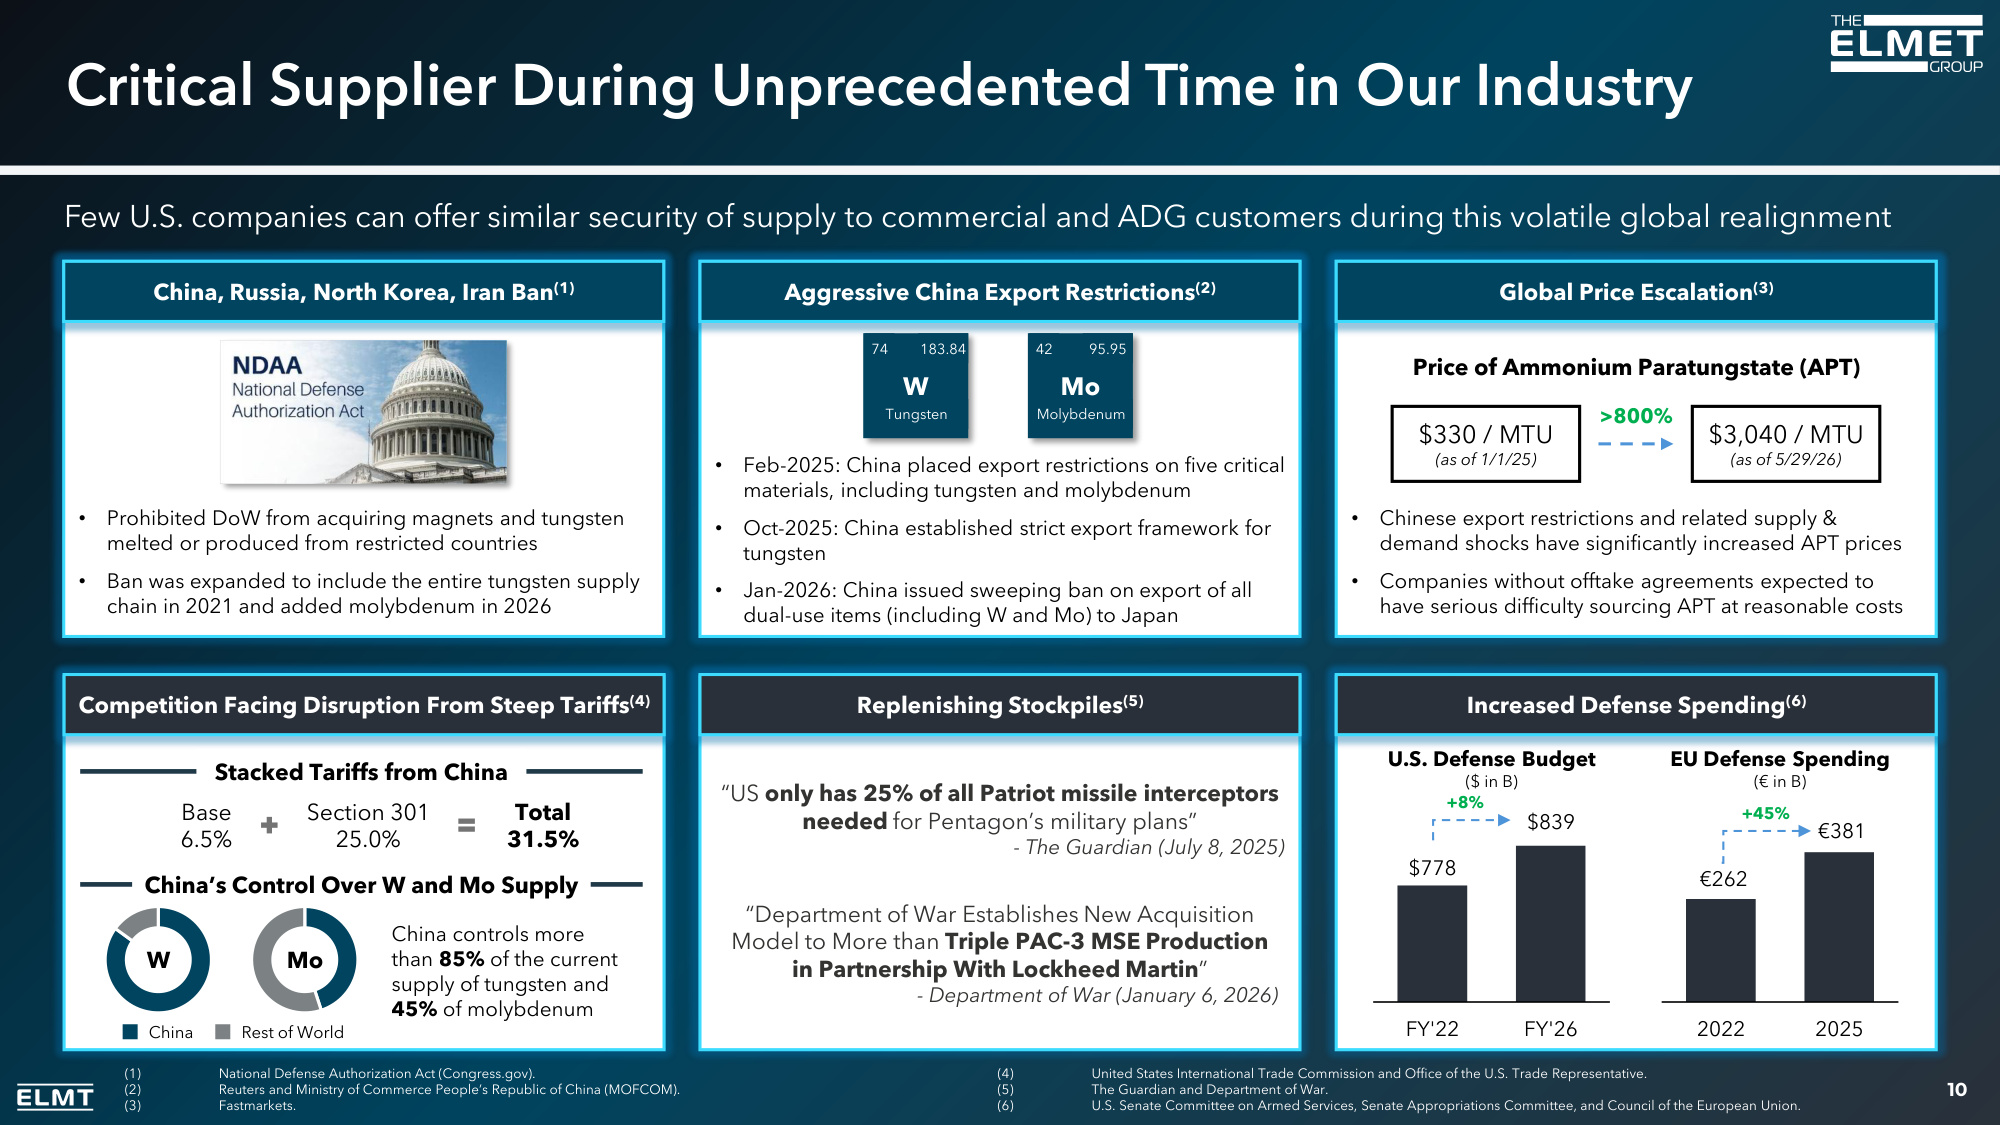
10 Few U.S. companies can offer similar security of supply to commercial and ADG customers during this volatile global realignment Replenishing Stockpiles(5) "Department of War Establishes New Acquisition Model to More than Triple PAC-3 MSE Production in Partnership With Lockheed Martin" - Department of War (January 6, 2026) "US only has 25% of all Patriot missile interceptors needed for Pentagon's military plans" - The Guardian (July 8, 2025) Increased Defense Spending(6) $778 $839 FY'22 FY'26 U.S. Defense Budget ($ in B) EU Defense Spending (€ in B) €262 €381 2022 2025 +45% +8% Global Price Escalation(3) $330 / MTU (as of 1/1/25) $3,040 / MTU (as of 5/29/26) >800% Price of Ammonium Paratungstate (APT) • Chinese export restrictions and related supply & demand shocks have significantly increased APT prices • Companies without offtake agreements expected to have serious difficulty sourcing APT at reasonable costs China, Russia, North Korea, Iran Ban(1) • Prohibited DoW from acquiring magnets and tungsten melted or produced from restricted countries • Ban was expanded to include the entire tungsten supply chain in 2021 and added molybdenum in 2026 Competition Facing Disruption From Steep Tariffs(4) Stacked Tariffs from China (1) National Defense Authorization Act (Congress.gov). (2) Reuters and Ministry of Commerce People's Republic of China (MOFCOM). (3) Fastmarkets. (4) United States International Trade Commission and Office of the U.S. Trade Representative. (5) The Guardian and Department of War. (6) U.S. Senate Committee on Armed Services, Senate Appropriations Committee, and Council of the European Union. Aggressive China Export Restrictions(2) • Feb-2025: China placed export restrictions on five critical materials, including tungsten and molybdenum • Oct-2025: China established strict export framework for tungsten • Jan-2026: China issued sweeping ban on export of all dual-use items (including W and Mo) to Japan Mo 42 95.95 Molybdenum W 74 183.84 Tungsten Critical Supplier During Unprecedented Time in Our Industry Base 6.5% Section 301 25.0% Total 31.5% China's Control Over W and Mo Supply China controls more than 85% of the current supply of tungsten and 45% of molybdenum China Rest of World W Mo
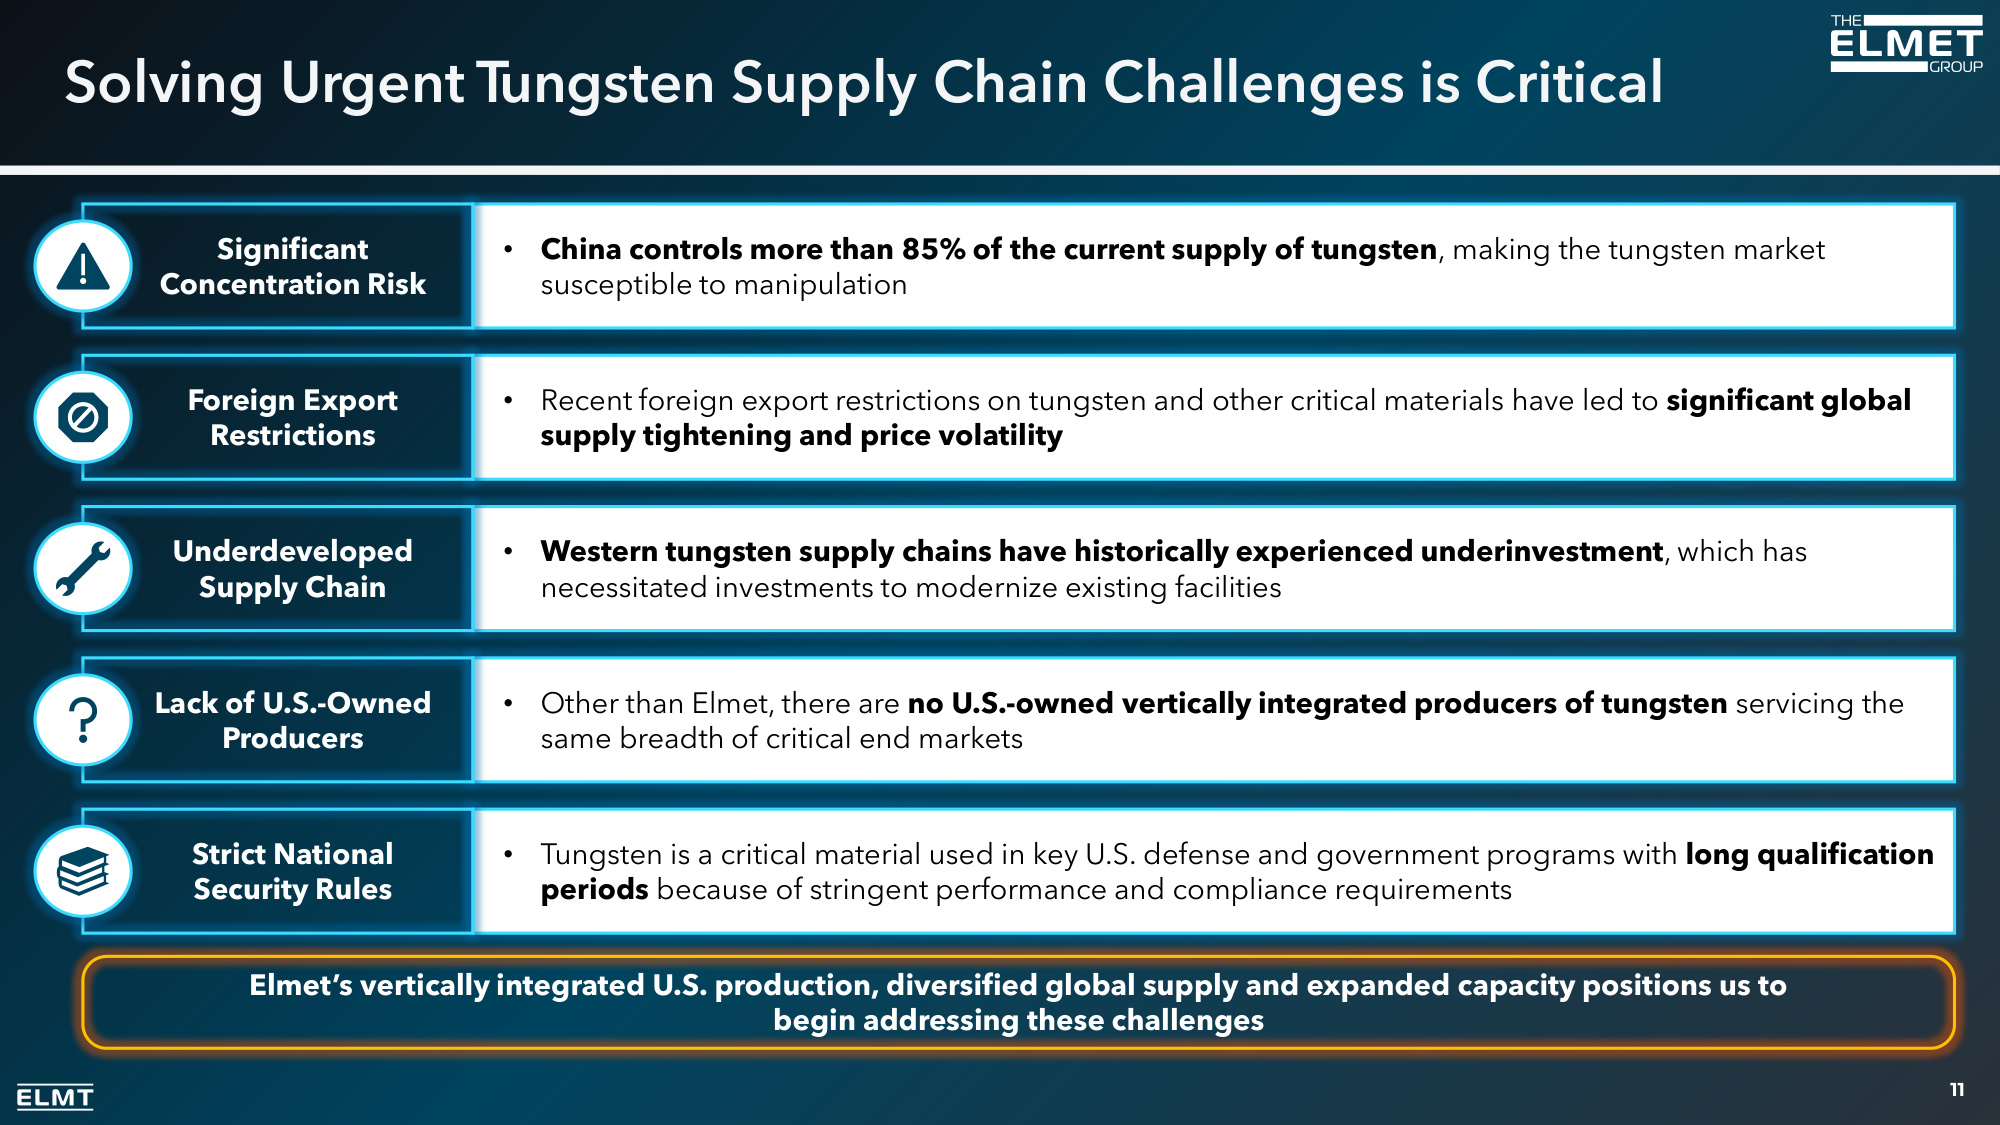
Solving Urgent Tungsten Supply Chain Challenges is Critical 11 • China controls more than 85% of the current supply of tungsten, making the tungsten market susceptible to manipulation Significant Concentration Risk • Recent foreign export restrictions on tungsten and other critical materials have led to significant global supply tightening and price volatility Foreign Export Restrictions • Western tungsten supply chains have historically experienced underinvestment, which has necessitated investments to modernize existing facilities Underdeveloped Supply Chain • Other than Elmet, there are no U.S.-owned vertically integrated producers of tungsten servicing the same breadth of critical end markets Lack of U.S.-Owned Producers • Tungsten is a critical material used in key U.S. defense and government programs with long qualification periods because of stringent performance and compliance requirements Strict National Security Rules Elmet's vertically integrated U.S. production, diversified global supply and expanded capacity positions us to begin addressing these challenges
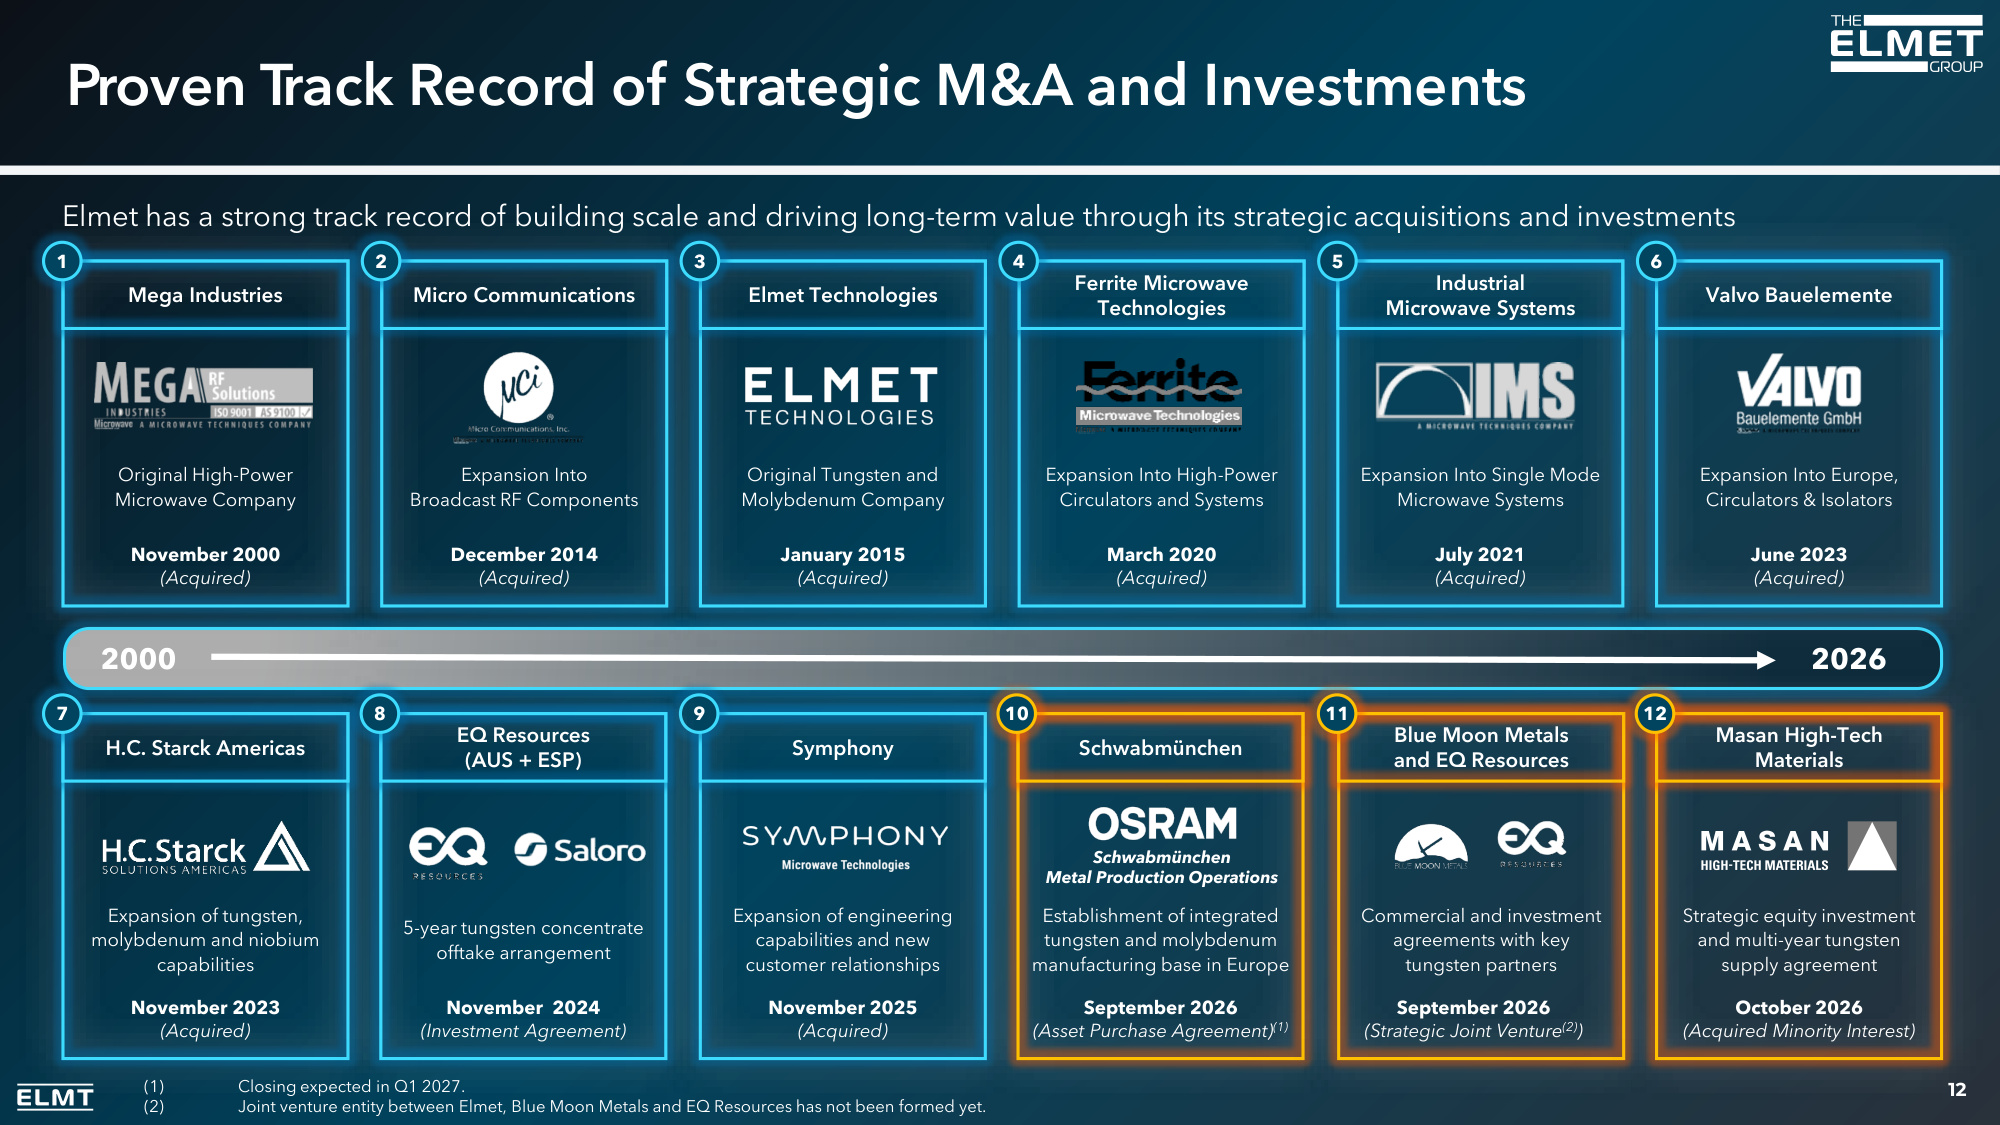
12 Proven Track Record of Strategic M&A and Investments Elmet has a strong track record of building scale and driving long-term value through its strategic acquisitions and investments 2000 2026 Mega Industries November 2000 (Acquired) Original High-Power Microwave Company 1 Micro Communications December 2014 (Acquired) Expansion Into Broadcast RF Components Elmet Technologies January 2015 (Acquired) Original Tungsten and Molybdenum Company Ferrite Microwave Technologies March 2020 (Acquired) Expansion Into High-Power Circulators and Systems Industrial Microwave Systems July 2021 (Acquired) Expansion Into Single Mode Microwave Systems Valvo Bauelemente June 2023 (Acquired) Expansion Into Europe, Circulators & Isolators 2 3 4 5 6 H.C. Starck Americas November 2023 (Acquired) Expansion of tungsten, molybdenum and niobium capabilities 7 Symphony November 2025 (Acquired) Expansion of engineering capabilities and new customer relationships 9 Schwabmünchen September 2026 (Asset Purchase Agreement)(1) Establishment of integrated tungsten and molybdenum manufacturing base in Europe 10 Schwabmünchen Metal Production Operations Blue Moon Metals and EQ Resources September 2026 (Strategic Joint Venture(2)) Commercial and investment agreements with key tungsten partners 11 EQ Resources (AUS + ESP) November 2024 (Investment Agreement) 5-year tungsten concentrate offtake arrangement 8 (1) Closing expected in Q1 2027. (2) Joint venture entity between Elmet, Blue Moon Metals and EQ Resources has not been formed yet. Masan High-Tech Materials October 2026 (Acquired Minority Interest) Strategic equity investment and multi-year tungsten supply agreement 12
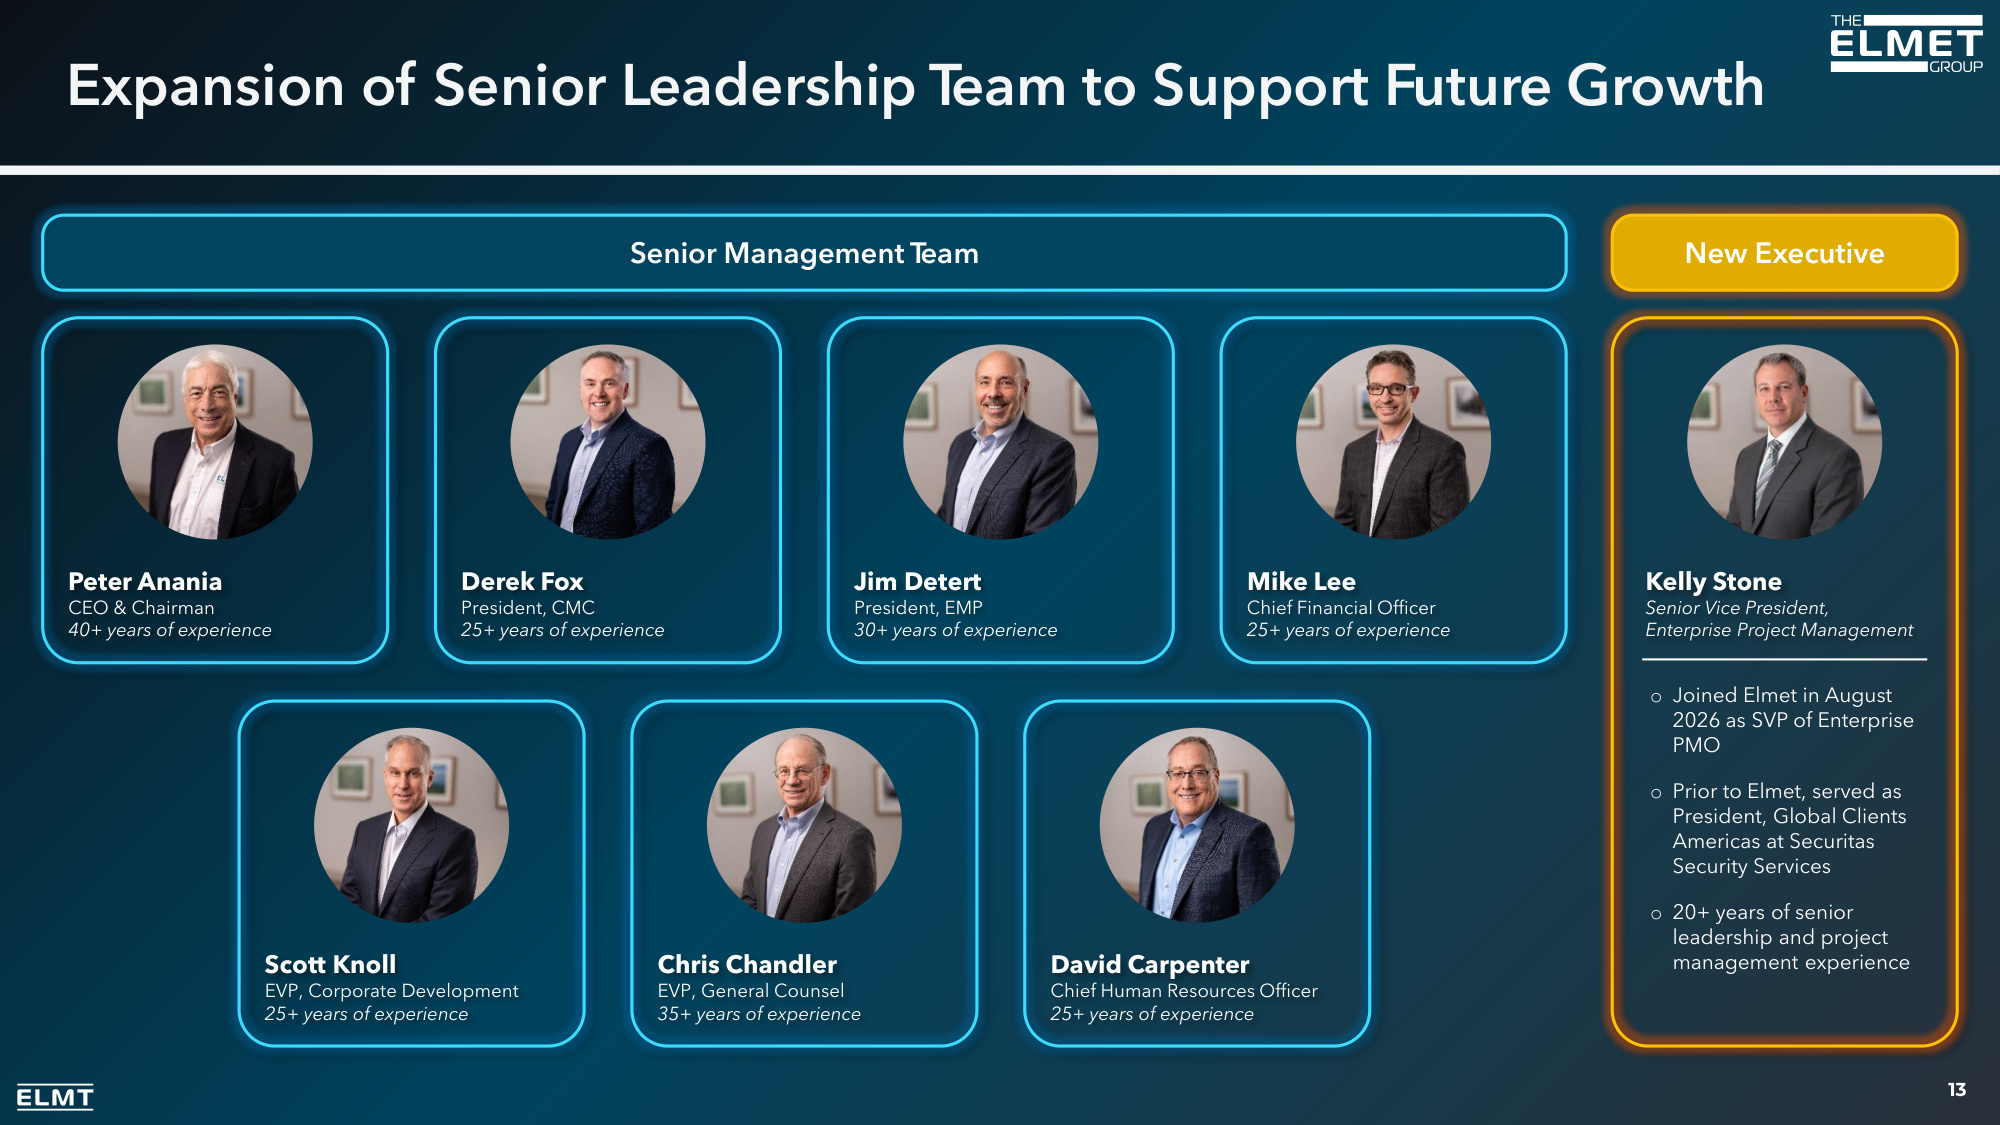
Expansion of Senior Leadership Team to Support Future Growth 13 Scott Knoll EVP, Corporate Development 25+ years of experience Jim Detert President, EMP 30+ years of experience David Carpenter Chief Human Resources Officer 25+ years of experience Peter Anania CEO & Chairman 40+ years of experience Derek Fox President, CMC 25+ years of experience Chris Chandler EVP, General Counsel 35+ years of experience Mike Lee Chief Financial Officer 25+ years of experience Senior Management Team Kelly Stone Senior Vice President, Enterprise Project Management New Executive o Joined Elmet in August 2026 as SVP of Enterprise PMO o Prior to Elmet, served as President, Global Clients Americas at Securitas Security Services o 20+ years of senior leadership and project management experience
O v e r v i e w o f L a n d m a r k D o W Tr a n s a c t i o n
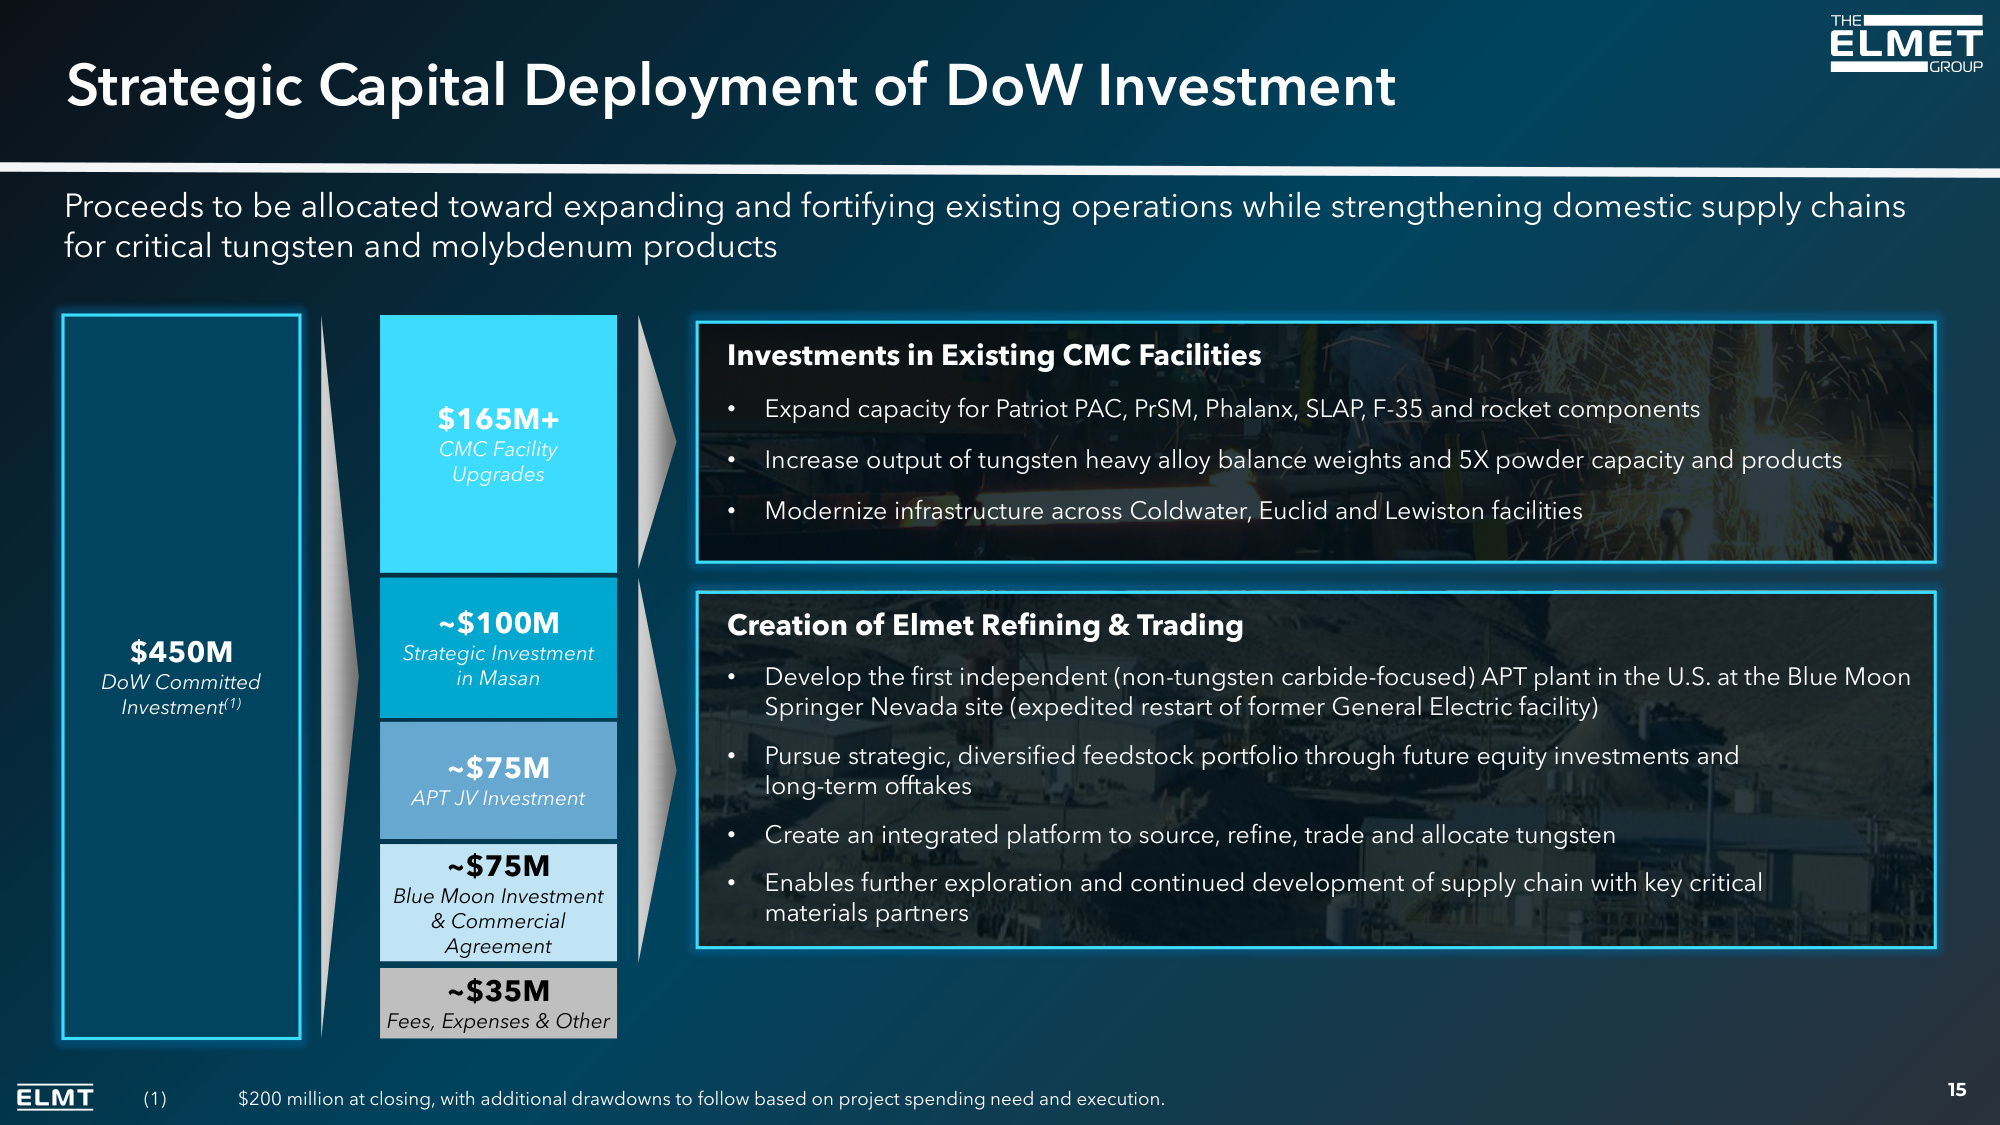
Investments in Existing CMC Facilities • Expand capacity for Patriot PAC, PrSM, Phalanx, SLAP, F-35 and rocket components • Increase output of tungsten heavy alloy balance weights and 5X powder capacity and products • Modernize infrastructure across Coldwater, Euclid and Lewiston facilities Strategic Capital Deployment of DoW Investment 15 $450M DoW Committed Investment(1) $165M+ CMC Facility Upgrades ~$100M Strategic Investment in Masan ~$75M APT JV Investment Creation of Elmet Refining & Trading • Develop the first independent (non-tungsten carbide-focused) APT plant in the U.S. at the Blue Moon Springer Nevada site (expedited restart of former General Electric facility) • Pursue strategic, diversified feedstock portfolio through future equity investments and long-term offtakes • Create an integrated platform to source, refine, trade and allocate tungsten • Enables further exploration and continued development of supply chain with key critical materials partners Proceeds to be allocated toward expanding and fortifying existing operations while strengthening domestic supply chains for critical tungsten and molybdenum products ~$35M Fees, Expenses & Other ~$75M Blue Moon Investment & Commercial Agreement (1) $200 million at closing, with additional drawdowns to follow based on project spending need and execution.
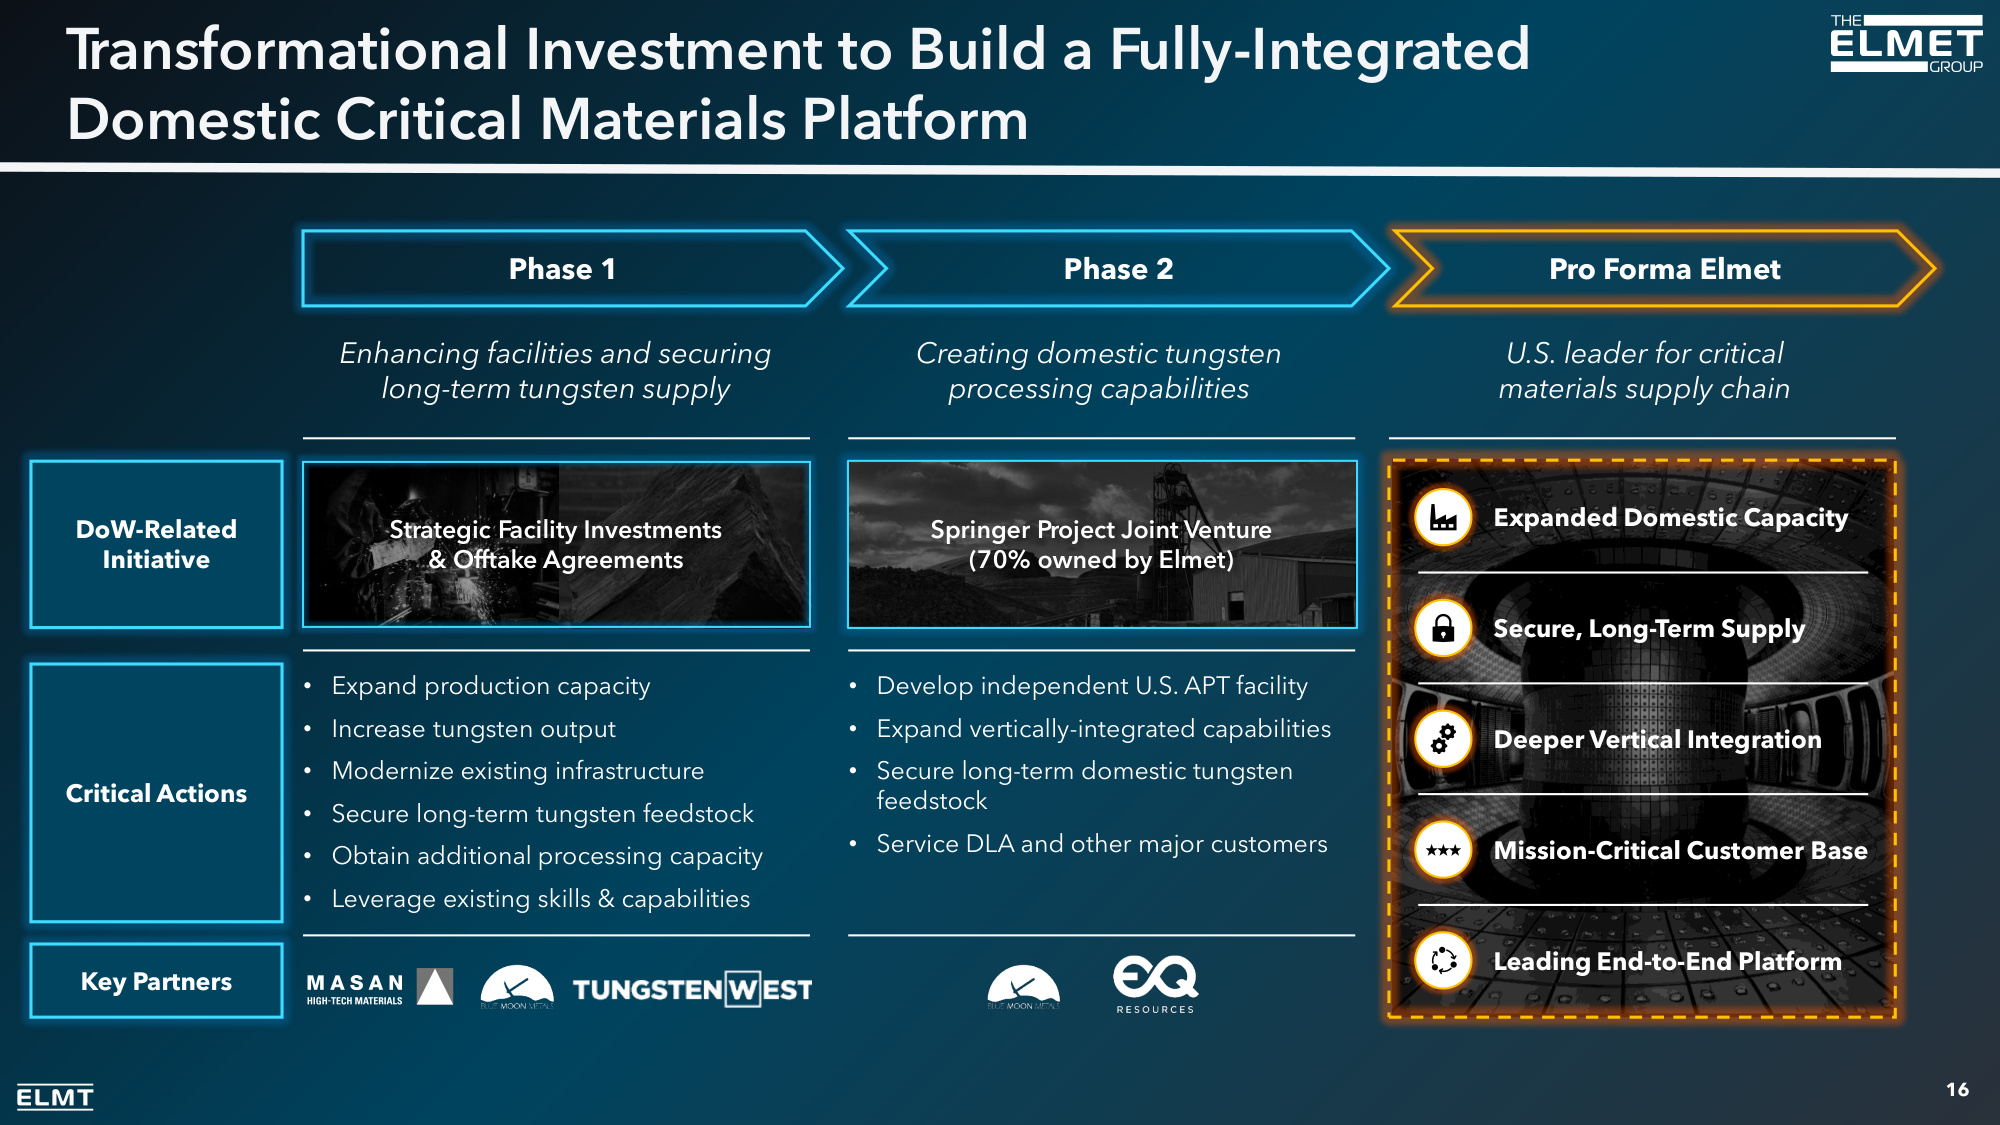
Pro Forma Elmet 16 Phase 1 Phase 2 Enhancing facilities and securing long-term tungsten supply Creating domestic tungsten processing capabilities U.S. leader for critical materials supply chain Critical Actions • Expand production capacity • Increase tungsten output • Modernize existing infrastructure • Secure long-term tungsten feedstock • Obtain additional processing capacity • Leverage existing skills & capabilities • Develop independent U.S. APT facility • Expand vertically-integrated capabilities • Secure long-term domestic tungsten feedstock • Service DLA and other major customers Key Partners DoW-Related Initiative Strategic Facility Investments & Offtake Agreements Springer Project Joint Venture (70% owned by Elmet) Transformational Investment to Build a Fully-Integrated Domestic Critical Materials Platform Expanded Domestic Capacity Secure, Long-Term Supply Deeper Vertical Integration Mission-Critical Customer Base Leading End-to-End Platform
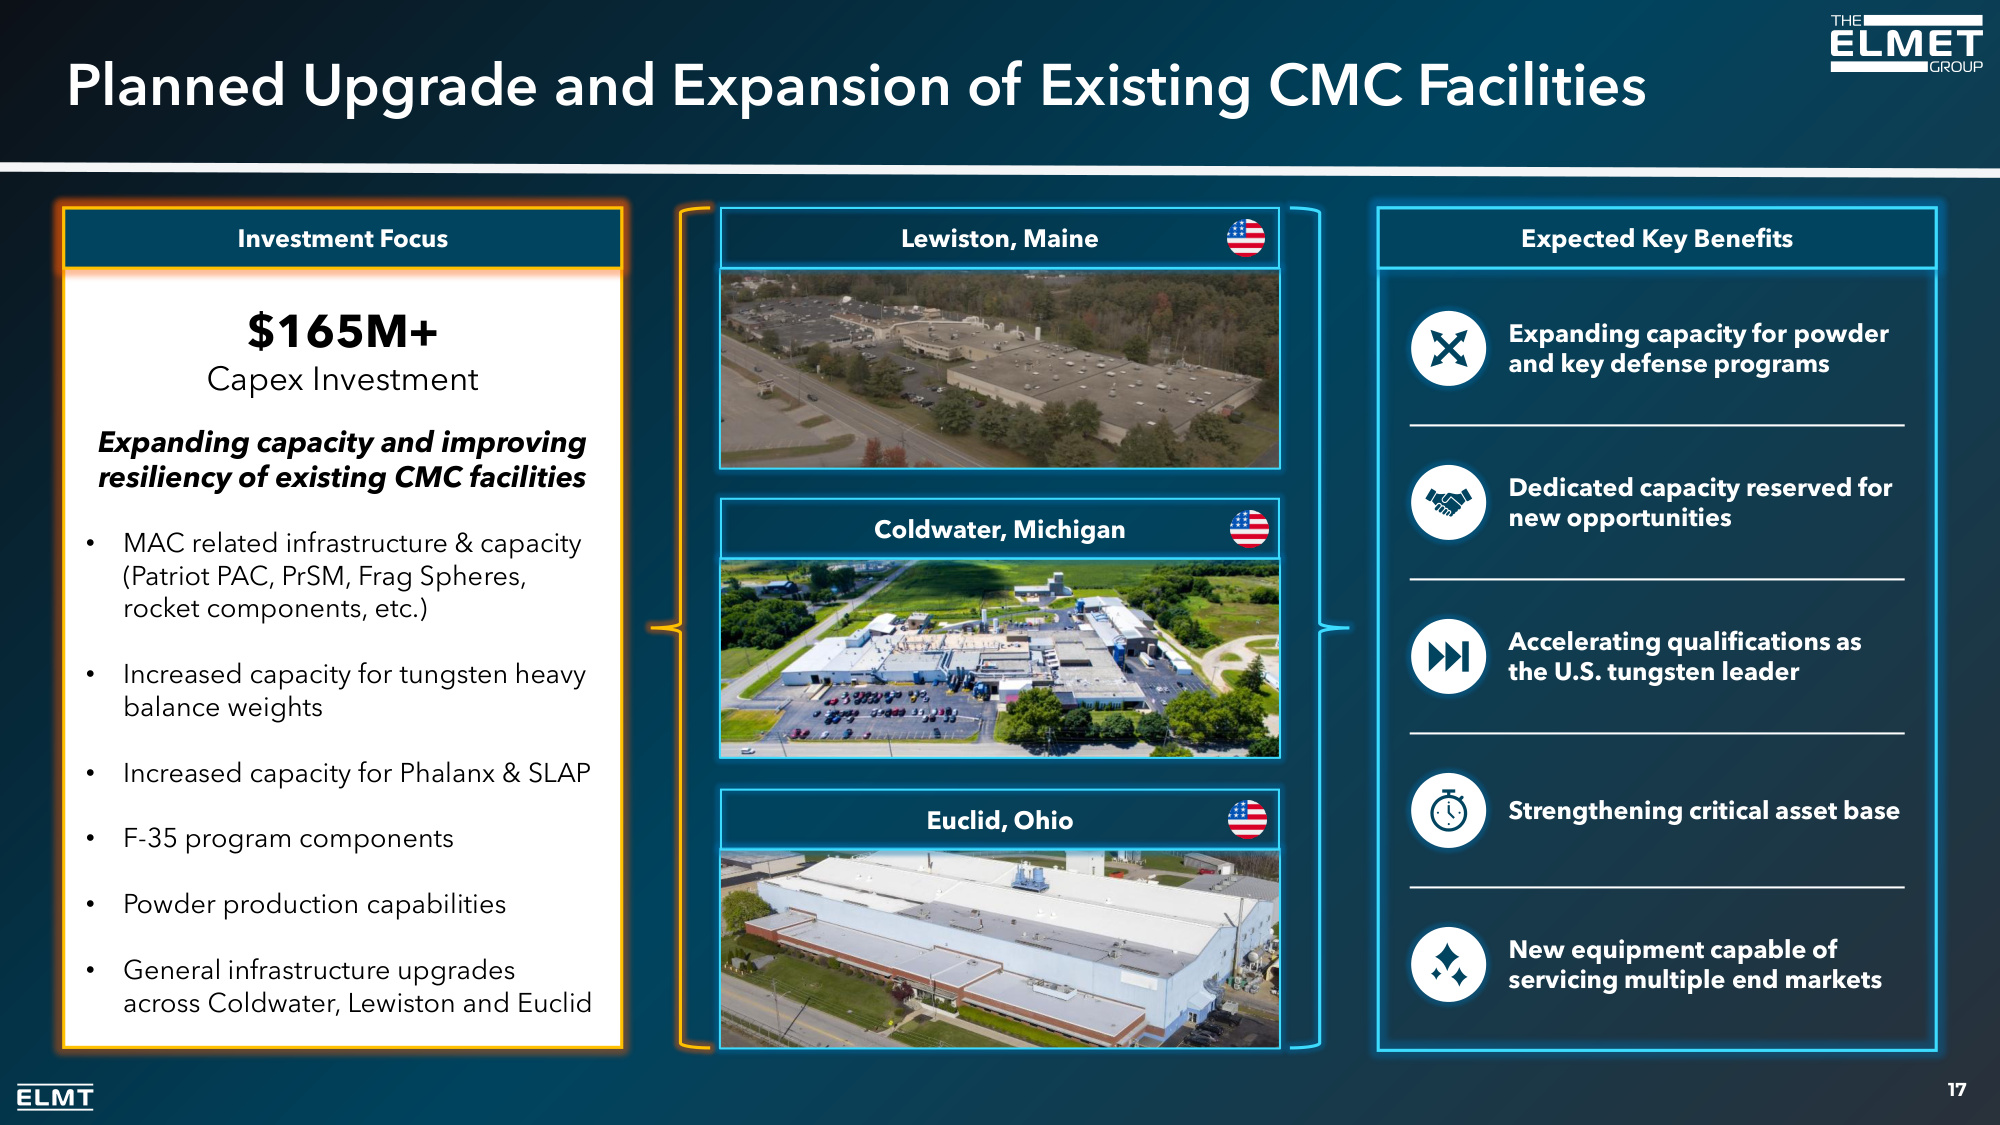
Planned Upgrade and Expansion of Existing CMC Facilities 17 Euclid, Ohio Coldwater, Michigan Lewiston, Maine Expected Key Benefits Expanding capacity for powder and key defense programs Dedicated capacity reserved for new opportunities Accelerating qualifications as the U.S. tungsten leader Strengthening critical asset base New equipment capable of servicing multiple end markets Investment Focus $165M+ Capex Investment Expanding capacity and improving resiliency of existing CMC facilities • MAC related infrastructure & capacity (Patriot PAC, PrSM, Frag Spheres, rocket components, etc.) • Increased capacity for tungsten heavy balance weights • Increased capacity for Phalanx & SLAP • F-35 program components • Powder production capabilities • General infrastructure upgrades across Coldwater, Lewiston and Euclid
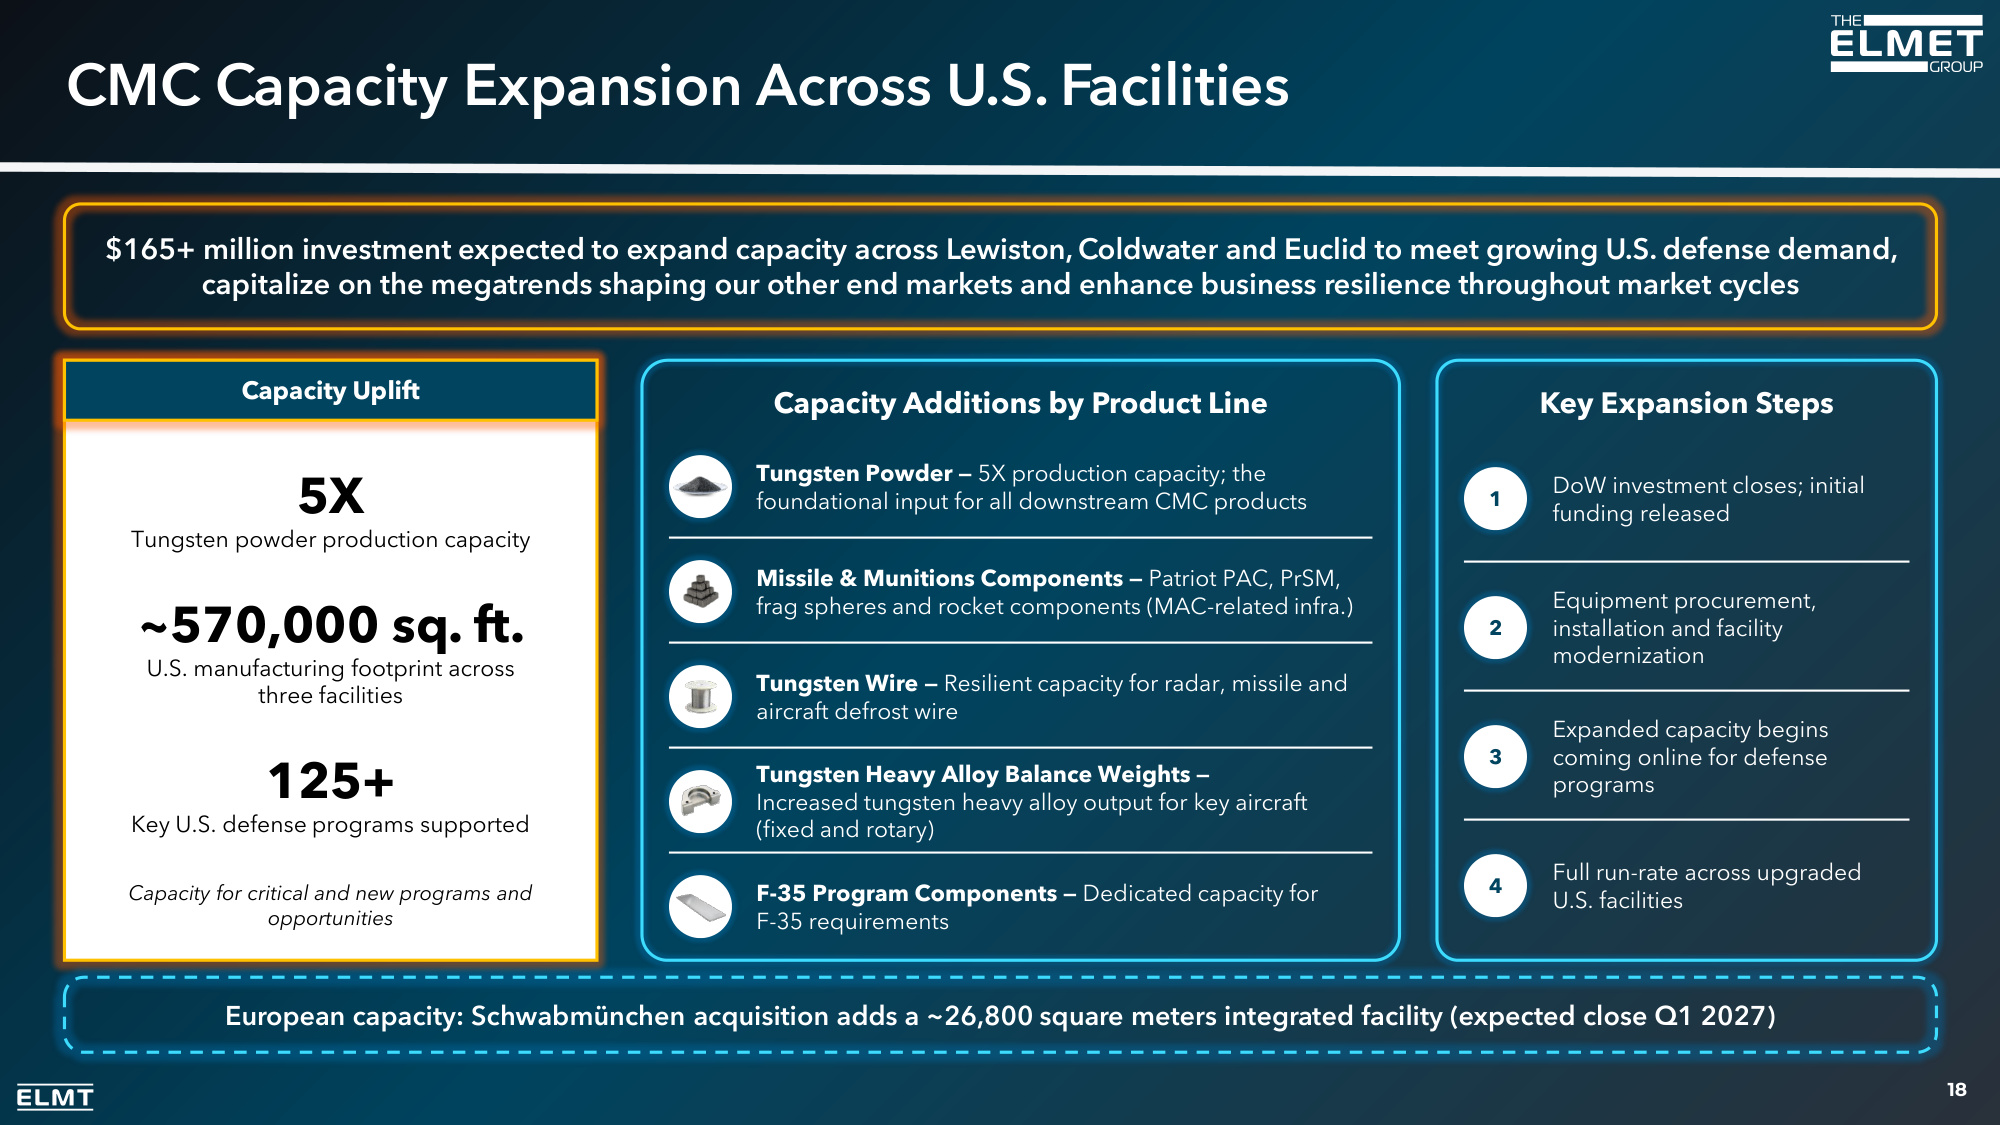
DoW investment closes; initial funding released Equipment procurement, installation and facility modernization Expanded capacity begins coming online for defense programs Full run-rate across upgraded U.S. facilities CMC Capacity Expansion Across U.S. Facilities 18 $165+ million investment expected to expand capacity across Lewiston, Coldwater and Euclid to meet growing U.S. defense demand, capitalize on the megatrends shaping our other end markets and enhance business resilience throughout market cycles Capacity Uplift 5X Tungsten powder production capacity ~570,000 sq. ft. U.S. manufacturing footprint across three facilities 125+ Key U.S. defense programs supported Capacity for critical and new programs and opportunities Capacity Additions by Product Line Tungsten Powder — 5X production capacity; the foundational input for all downstream CMC products Missile & Munitions Components — Patriot PAC, PrSM, frag spheres and rocket components (MAC-related infra.) Tungsten Wire — Resilient capacity for radar, missile and aircraft defrost wire Tungsten Heavy Alloy Balance Weights — Increased tungsten heavy alloy output for key aircraft (fixed and rotary) F-35 Program Components — Dedicated capacity for F-35 requirements Key Expansion Steps 1 2 3 4 European capacity: Schwabmünchen acquisition adds a ~26,800 square meters integrated facility (expected close Q1 2027)
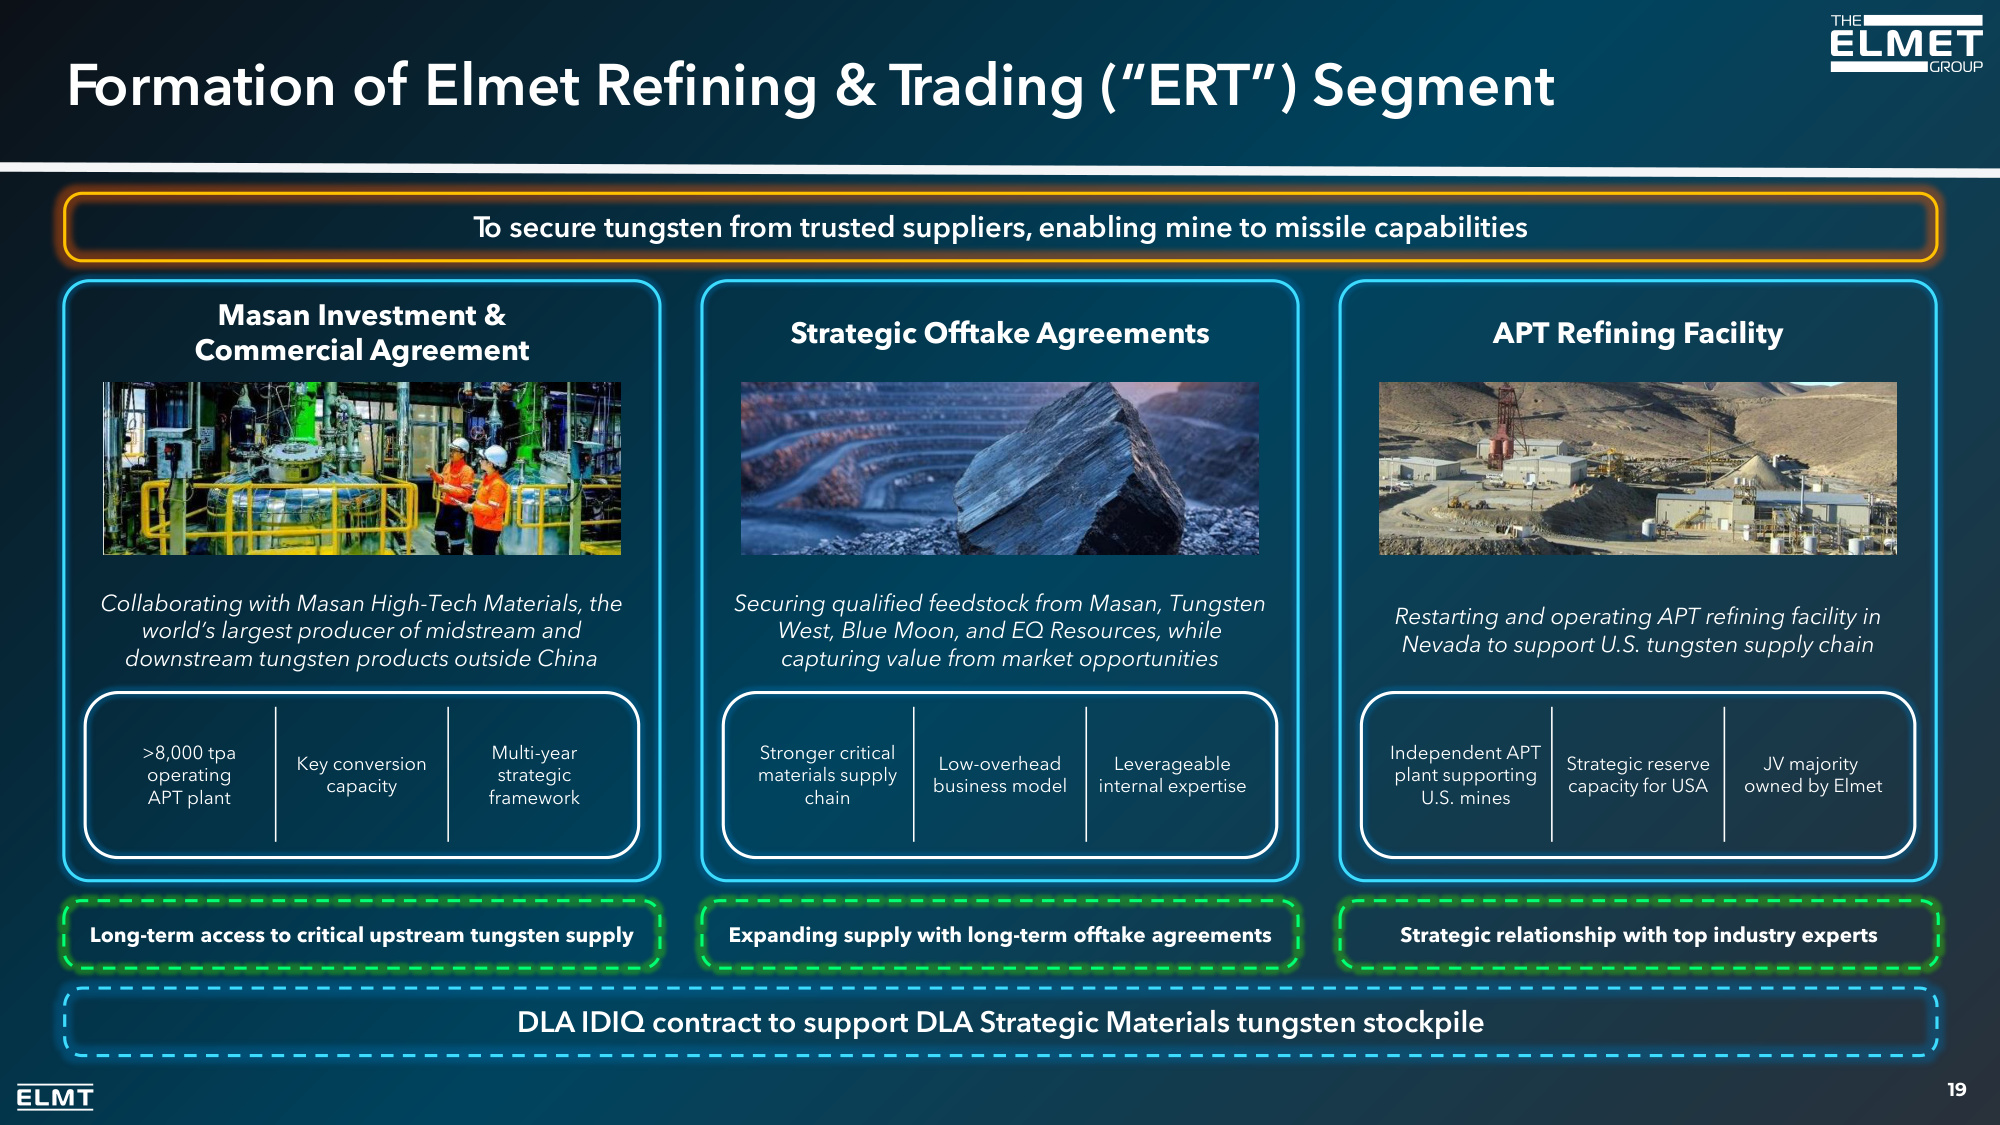
Formation of Elmet Refining & Trading ("ERT") Segment 19 To secure tungsten from trusted suppliers, enabling mine to missile capabilities DLA IDIQ contract to support DLA Strategic Materials tungsten stockpile Expanding supply with long-term offtake agreements Strategic relationship with top industry experts APT Refining Facility Restarting and operating APT refining facility in Nevada to support U.S. tungsten supply chain Independent APT plant supporting U.S. mines Strategic reserve capacity for USA JV majority owned by Elmet Strategic Offtake Agreements Securing qualified feedstock from Masan, Tungsten West, Blue Moon, and EQ Resources, while capturing value from market opportunities Stronger critical materials supply chain Low-overhead business model Leverageable internal expertise Masan Investment & Commercial Agreement Collaborating with Masan High-Tech Materials, the world's largest producer of midstream and downstream tungsten products outside China >8,000 tpa operating APT plant Key conversion capacity Multi-year strategic framework Long-term access to critical upstream tungsten supply
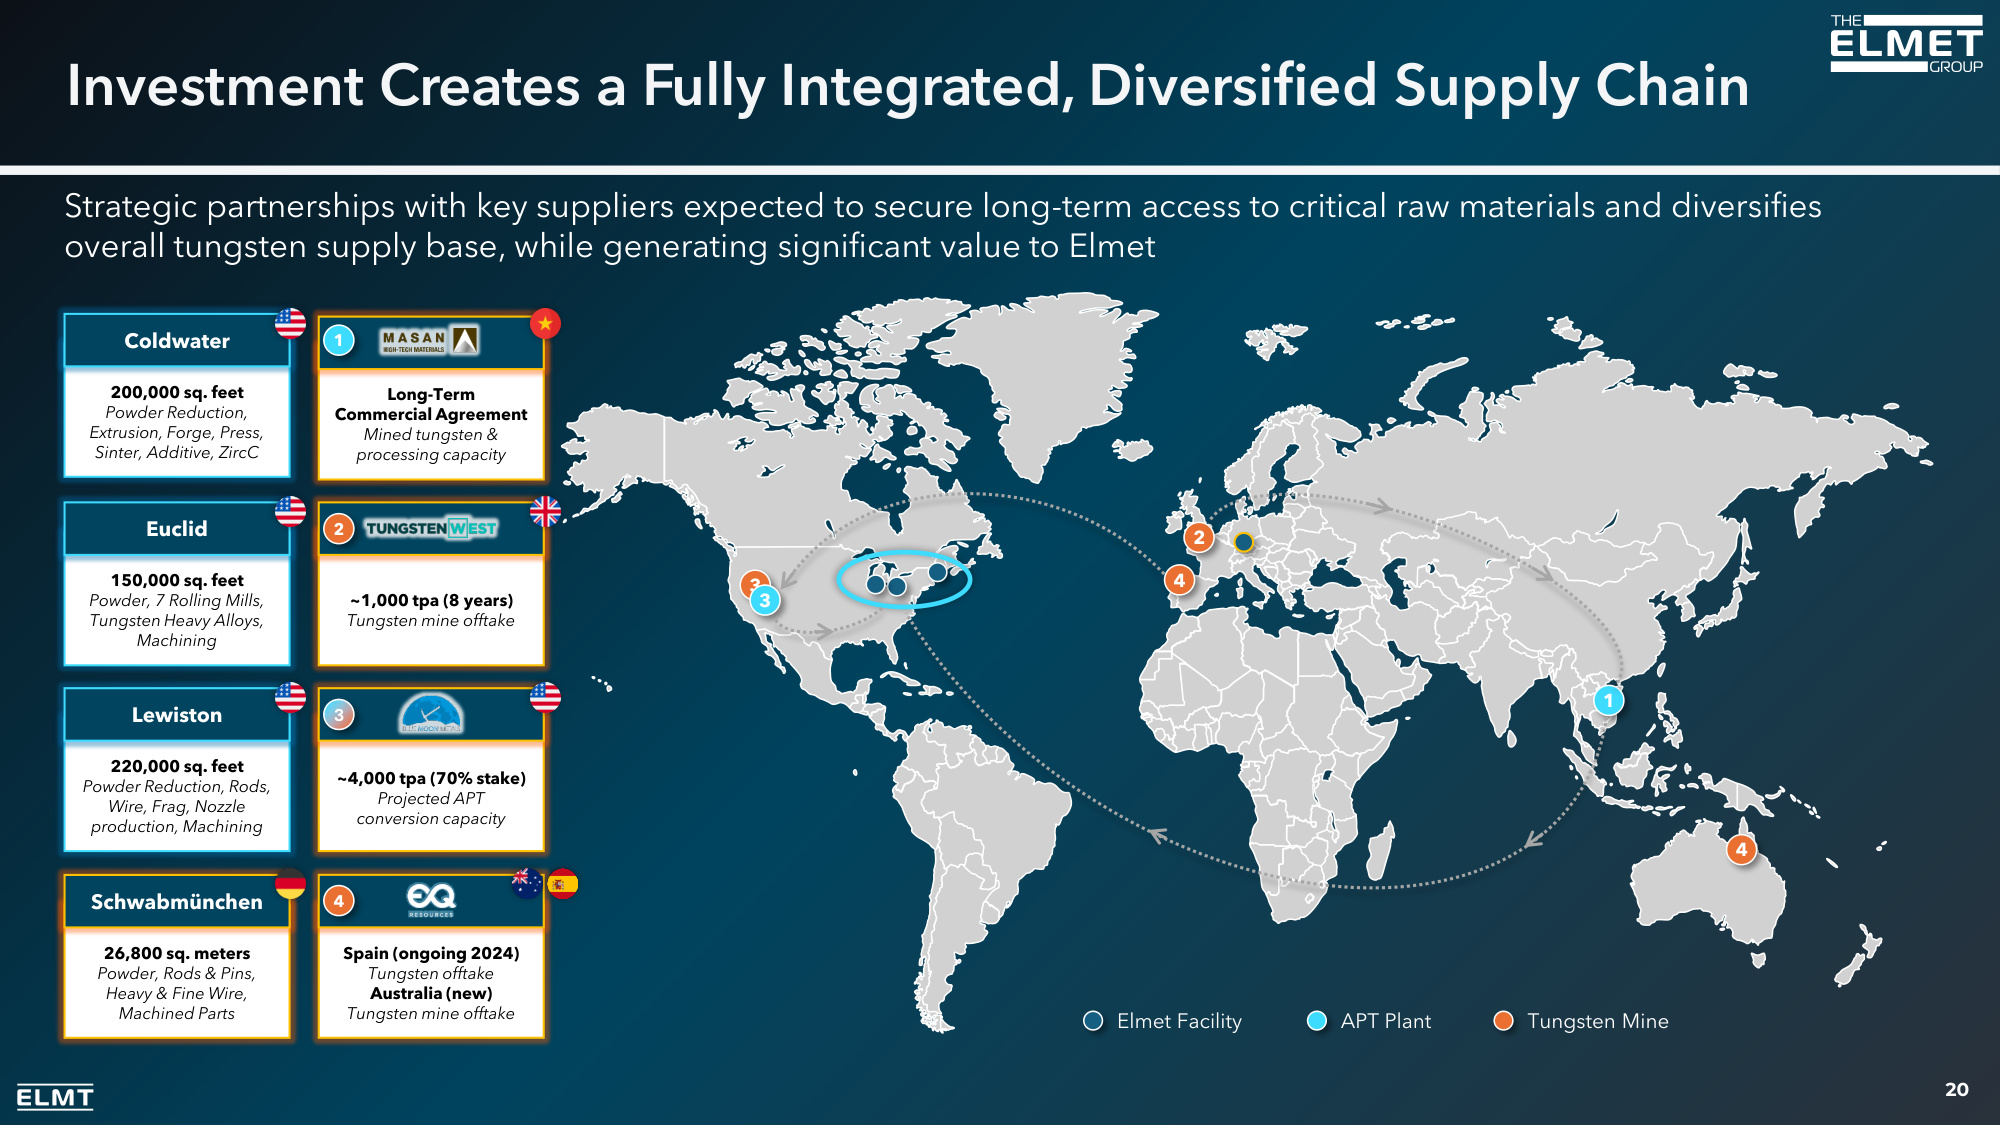
20 1 2 33 4 Elmet Facility Tungsten Mine APT Plant Investment Creates a Fully Integrated, Diversified Supply Chain Strategic partnerships with key suppliers expected to secure long-term access to critical raw materials and diversifies overall tungsten supply base, while generating significant value to Elmet ~4,000 tpa (70% stake) Projected APT conversion capacity 220,000 sq. feet Powder Reduction, Rods, Wire, Frag, Nozzle production, Machining Lewiston 3 ~1,000 tpa (8 years) Tungsten mine offtake 150,000 sq. feet Powder, 7 Rolling Mills, Tungsten Heavy Alloys, Machining Euclid 2 200,000 sq. feet Powder Reduction, Extrusion, Forge, Press, Sinter, Additive, ZircC Coldwater Long-Term Commercial Agreement Mined tungsten & processing capacity 1 Spain (ongoing 2024) Tungsten offtake Australia (new) Tungsten mine offtake 4 26,800 sq. meters Powder, Rods & Pins, Heavy & Fine Wire, Machined Parts Schwabmünchen 4
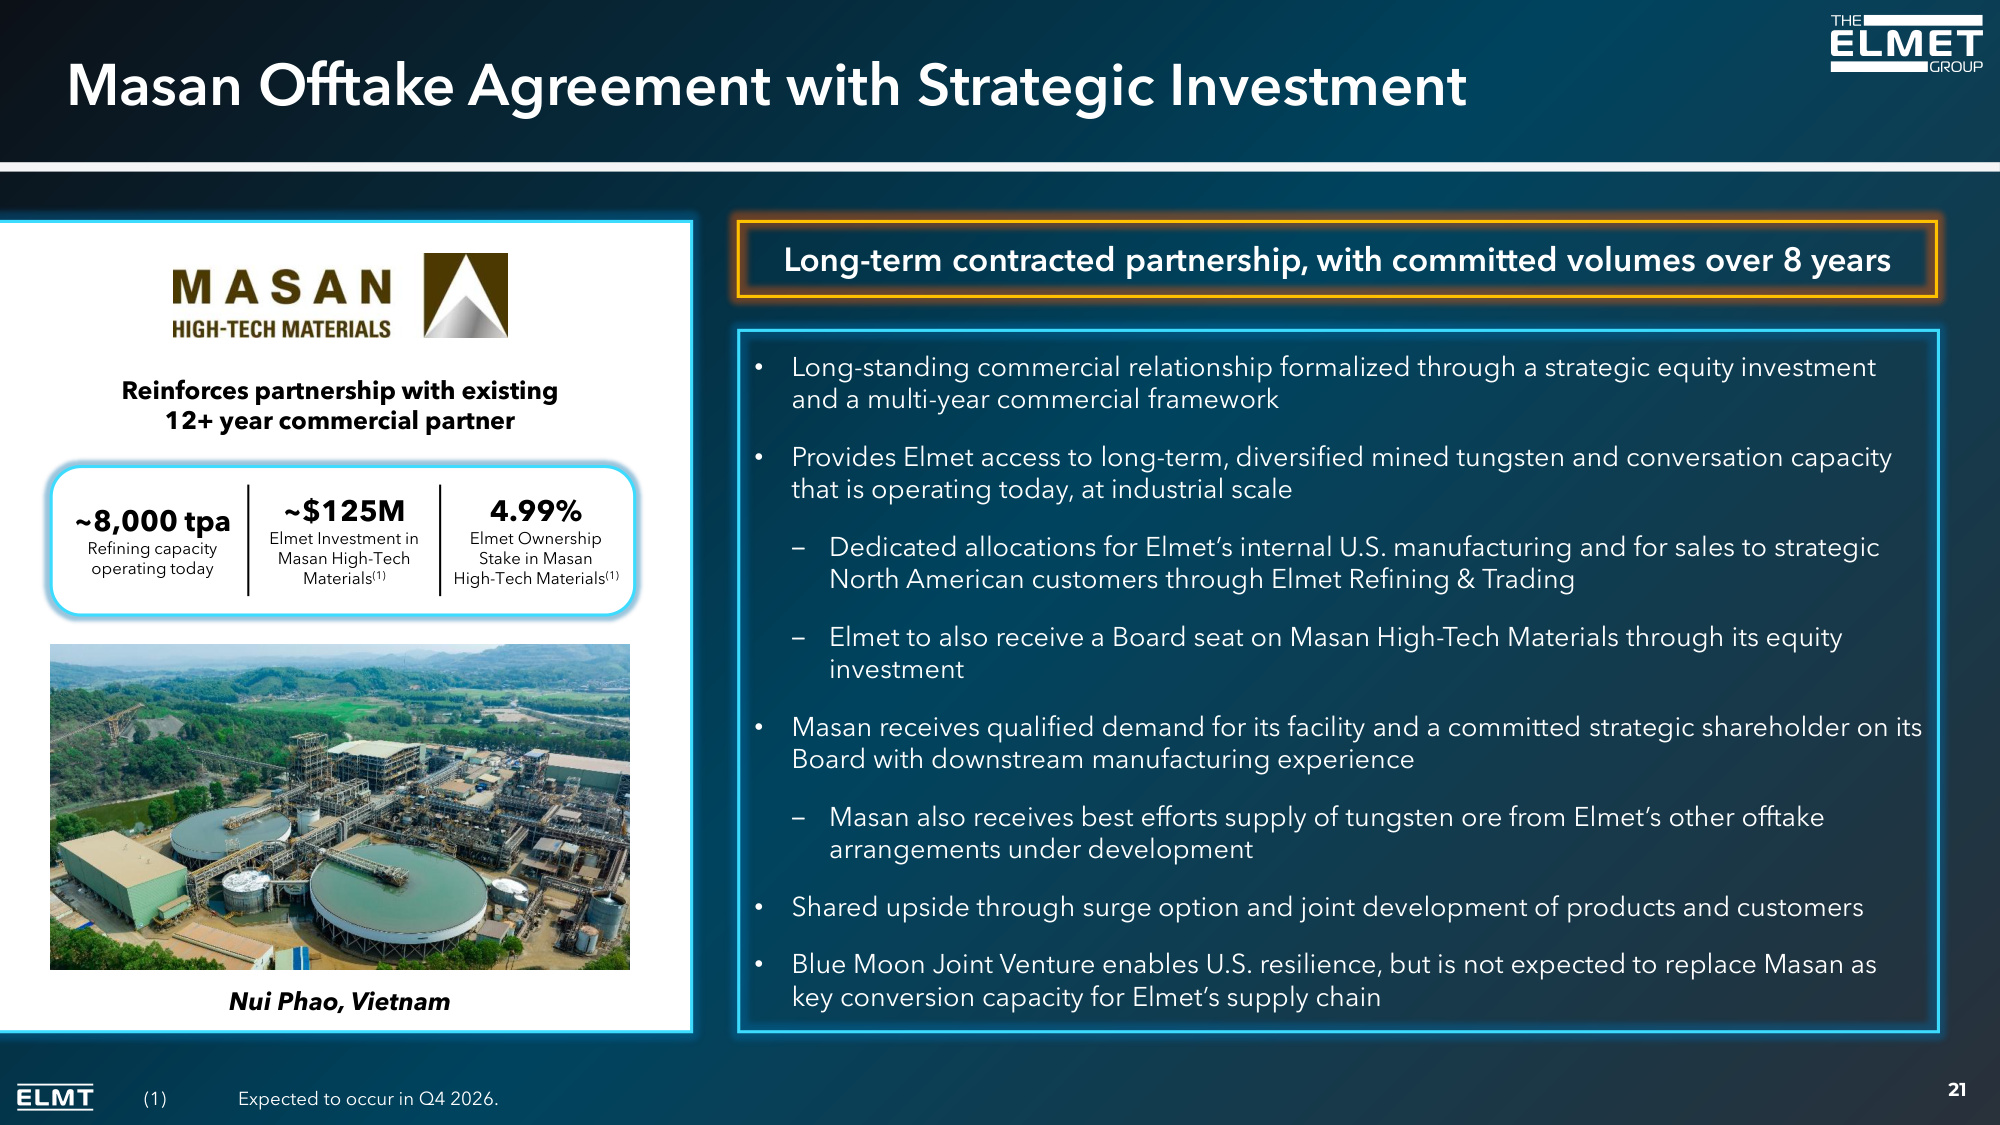
Masan Offtake Agreement with Strategic Investment 21 Reinforces partnership with existing 12+ year commercial partner Nui Phao, Vietnam ~8,000 tpa Refining capacity operating today ~$125M Elmet Investment in Masan High-Tech Materials(1) 4.99% Elmet Ownership Stake in Masan High-Tech Materials(1) • Long-standing commercial relationship formalized through a strategic equity investment and a multi-year commercial framework • Provides Elmet access to long-term, diversified mined tungsten and conversation capacity that is operating today, at industrial scale ‒ Dedicated allocations for Elmet's internal U.S. manufacturing and for sales to strategic North American customers through Elmet Refining & Trading ‒ Elmet to also receive a Board seat on Masan High-Tech Materials through its equity investment • Masan receives qualified demand for its facility and a committed strategic shareholder on its Board with downstream manufacturing experience ‒ Masan also receives best efforts supply of tungsten ore from Elmet's other offtake arrangements under development • Shared upside through surge option and joint development of products and customers • Blue Moon Joint Venture enables U.S. resilience, but is not expected to replace Masan as key conversion capacity for Elmet's supply chain Long-term contracted partnership, with committed volumes over 8 years (1) Expected to occur in Q4 2026.
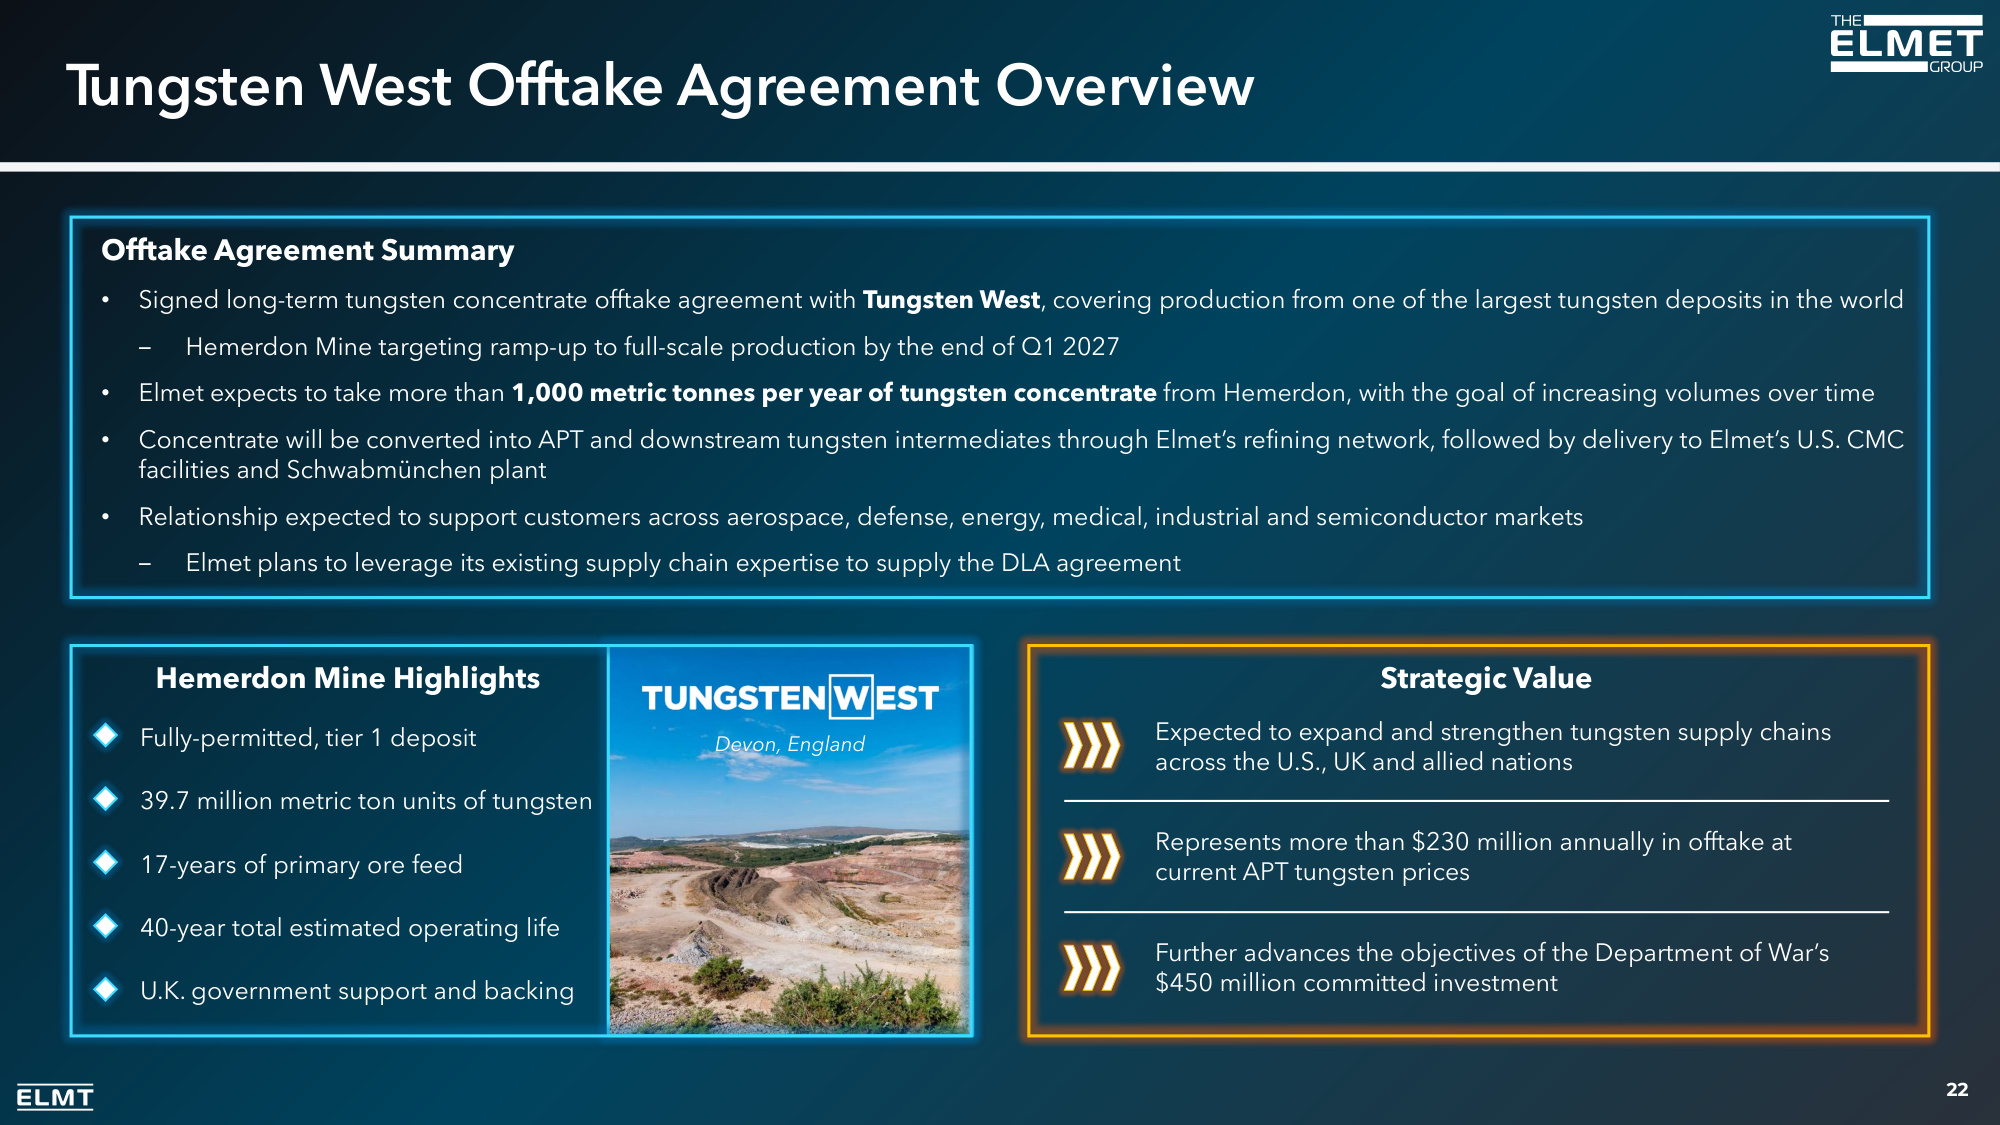
Hemerdon Mine Highlights Tungsten West Offtake Agreement Overview 22 Offtake Agreement Summary • Signed long-term tungsten concentrate offtake agreement with Tungsten West, covering production from one of the largest tungsten deposits in the world ‒ Hemerdon Mine targeting ramp-up to full-scale production by the end of Q1 2027 • Elmet expects to take more than 1,000 metric tonnes per year of tungsten concentrate from Hemerdon, with the goal of increasing volumes over time • Concentrate will be converted into APT and downstream tungsten intermediates through Elmet's refining network, followed by delivery to Elmet's U.S. CMC facilities and Schwabmünchen plant • Relationship expected to support customers across aerospace, defense, energy, medical, industrial and semiconductor markets ‒ Elmet plans to leverage its existing supply chain expertise to supply the DLA agreement Strategic Value Devon, England Fully-permitted, tier 1 deposit 39.7 million metric ton units of tungsten 17-years of primary ore feed 40-year total estimated operating life U.K. government support and backing Expected to expand and strengthen tungsten supply chains across the U.S., UK and allied nations Further advances the objectives of the Department of War's $450 million committed investment Represents more than $230 million annually in offtake at current APT tungsten prices
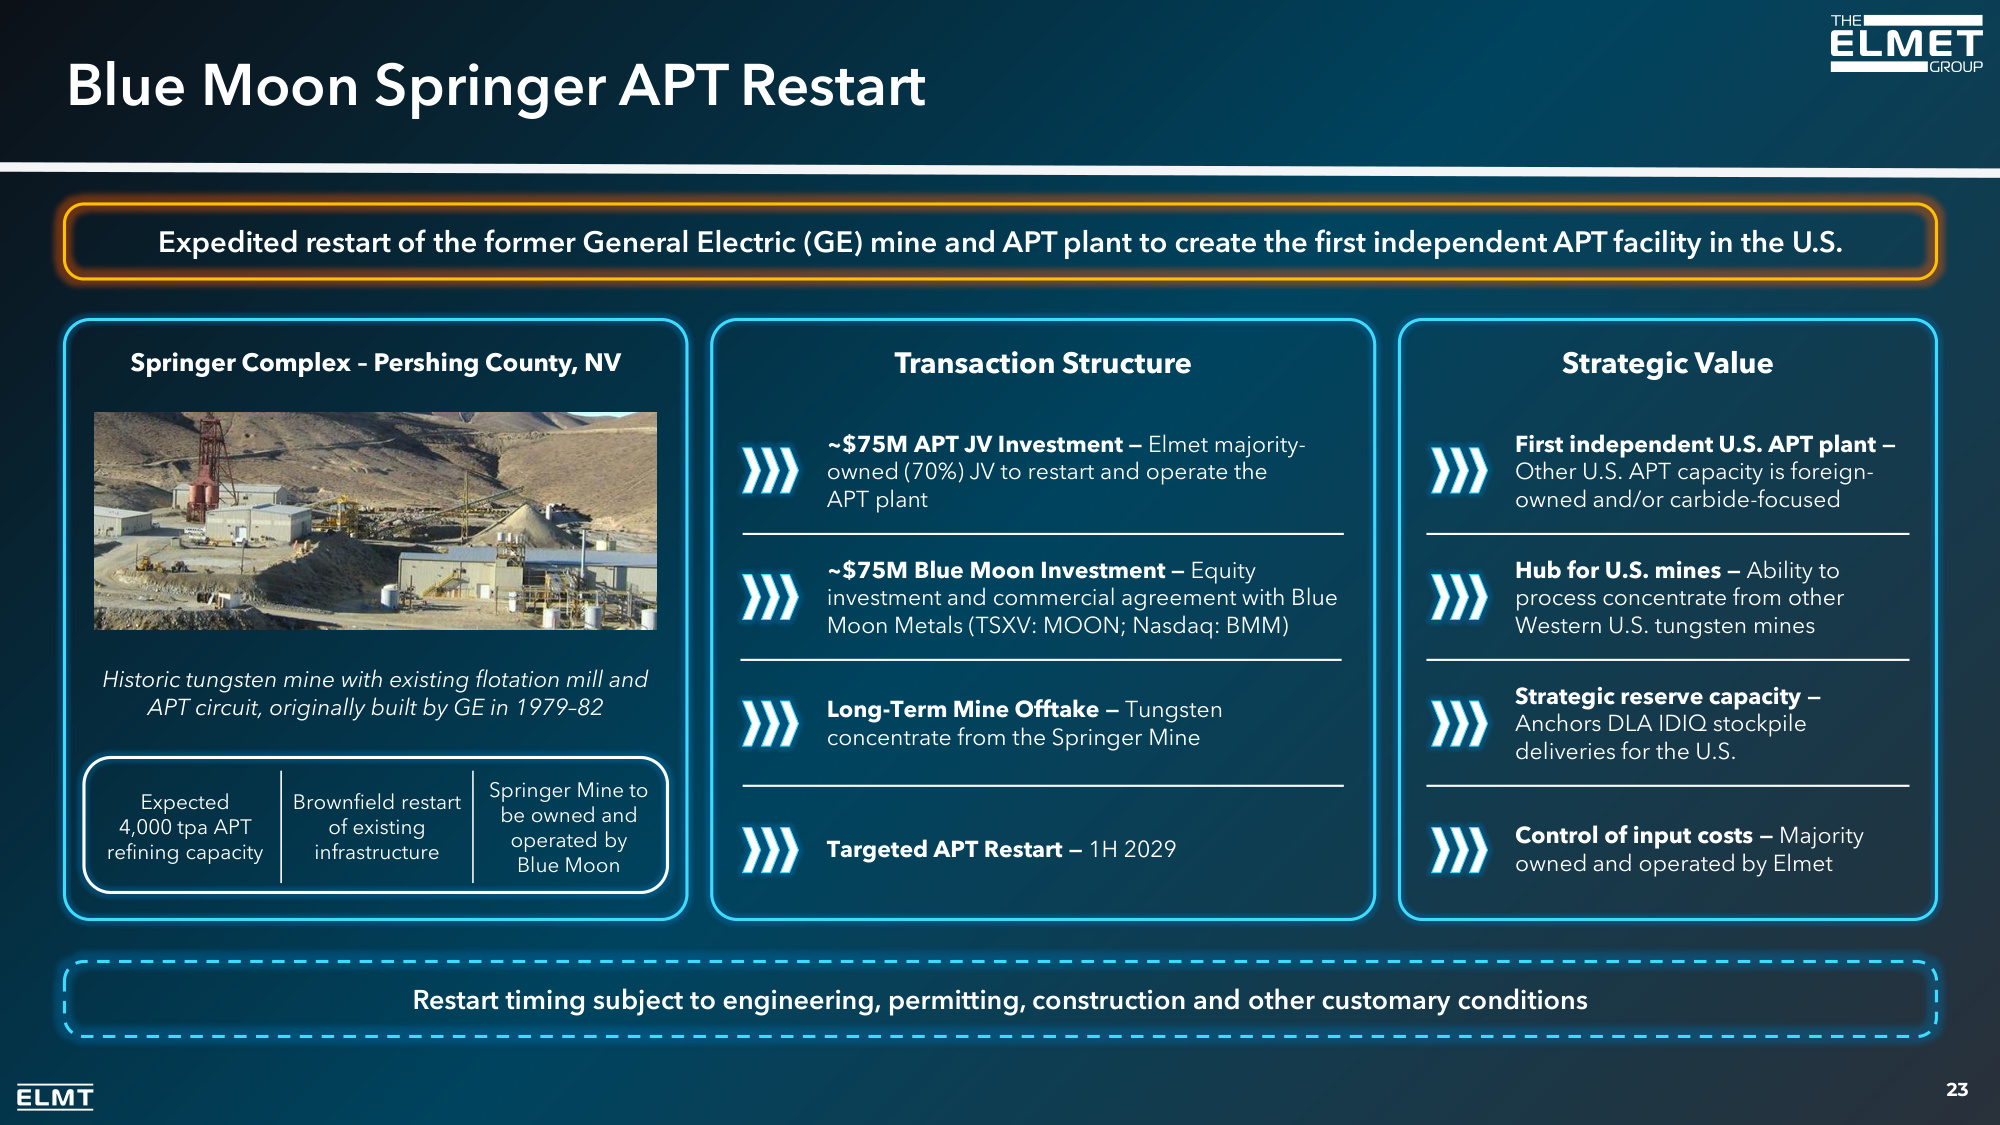
~$75M APT JV Investment — Elmet majority- owned (70%) JV to restart and operate the APT plant ~$75M Blue Moon Investment — Equity investment and commercial agreement with Blue Moon Metals (TSXV: MOON; Nasdaq: BMM) Long-Term Mine Offtake — Tungsten concentrate from the Springer Mine Targeted APT Restart — 1H 2029 Blue Moon Springer APT Restart 23 Expedited restart of the former General Electric (GE) mine and APT plant to create the first independent APT facility in the U.S. Springer Complex – Pershing County, NV Historic tungsten mine with existing flotation mill and APT circuit, originally built by GE in 1979–82 Expected 4,000 tpa APT refining capacity Brownfield restart of existing infrastructure Springer Mine to be owned and operated by Blue Moon Transaction Structure Strategic Value First independent U.S. APT plant — Other U.S. APT capacity is foreign- owned and/or carbide-focused Hub for U.S. mines — Ability to process concentrate from other Western U.S. tungsten mines Strategic reserve capacity — Anchors DLA IDIQ stockpile deliveries for the U.S. Control of input costs — Majority owned and operated by Elmet Restart timing subject to engineering, permitting, construction and other customary conditions
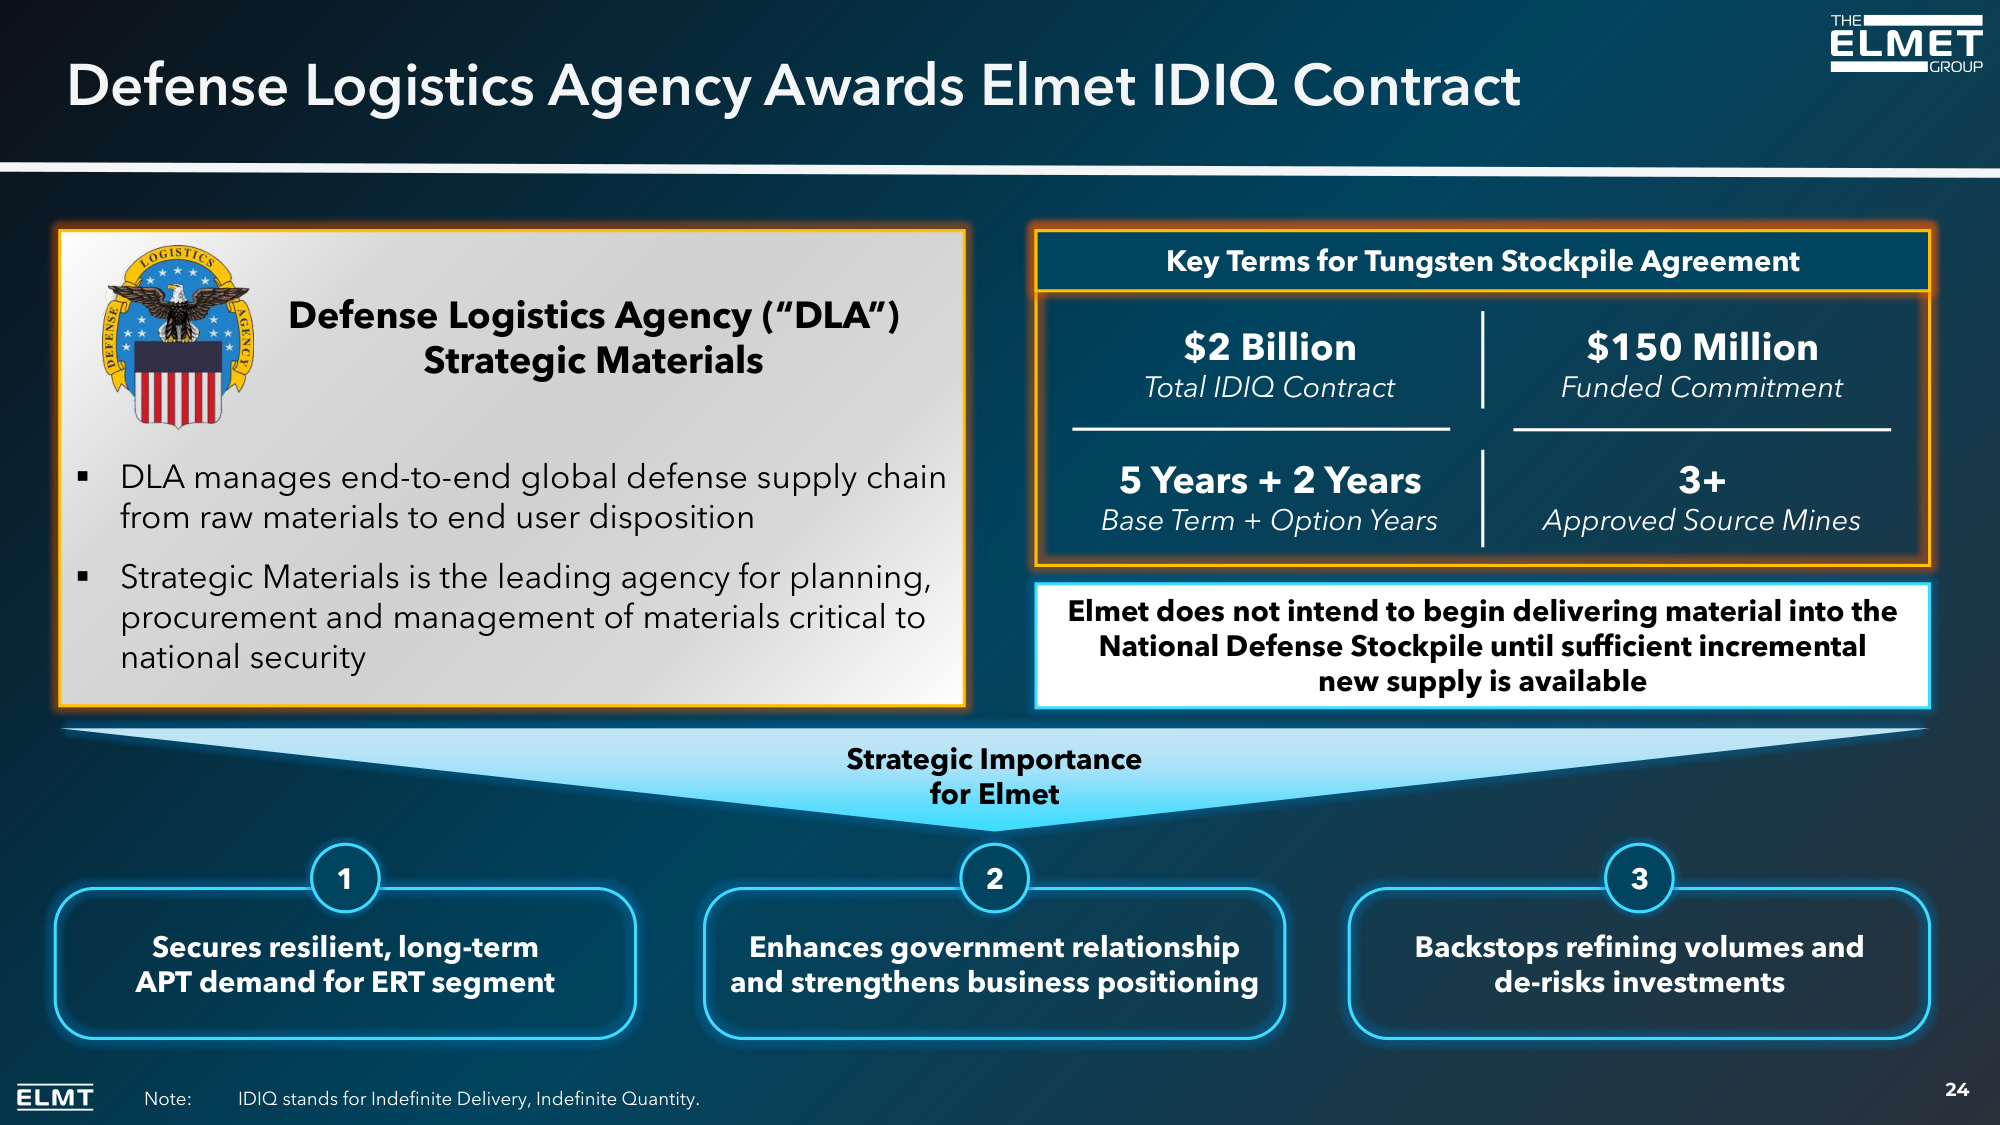
24 Defense Logistics Agency Awards Elmet IDIQ Contract ▪ DLA manages end-to-end global defense supply chain from raw materials to end user disposition ▪ Strategic Materials is the leading agency for planning, procurement and management of materials critical to national security Defense Logistics Agency ("DLA") Strategic Materials Key Terms for Tungsten Stockpile Agreement $2 Billion Total IDIQ Contract $150 Million Funded Commitment 5 Years + 2 Years Base Term + Option Years 3+ Approved Source Mines Secures resilient, long-term APT demand for ERT segment Enhances government relationship and strengthens business positioning Backstops refining volumes and de-risks investments Strategic Importance for Elmet 1 2 3 Note: IDIQ stands for Indefinite Delivery, Indefinite Quantity. Elmet does not intend to begin delivering material into the National Defense Stockpile until sufficient incremental new supply is available
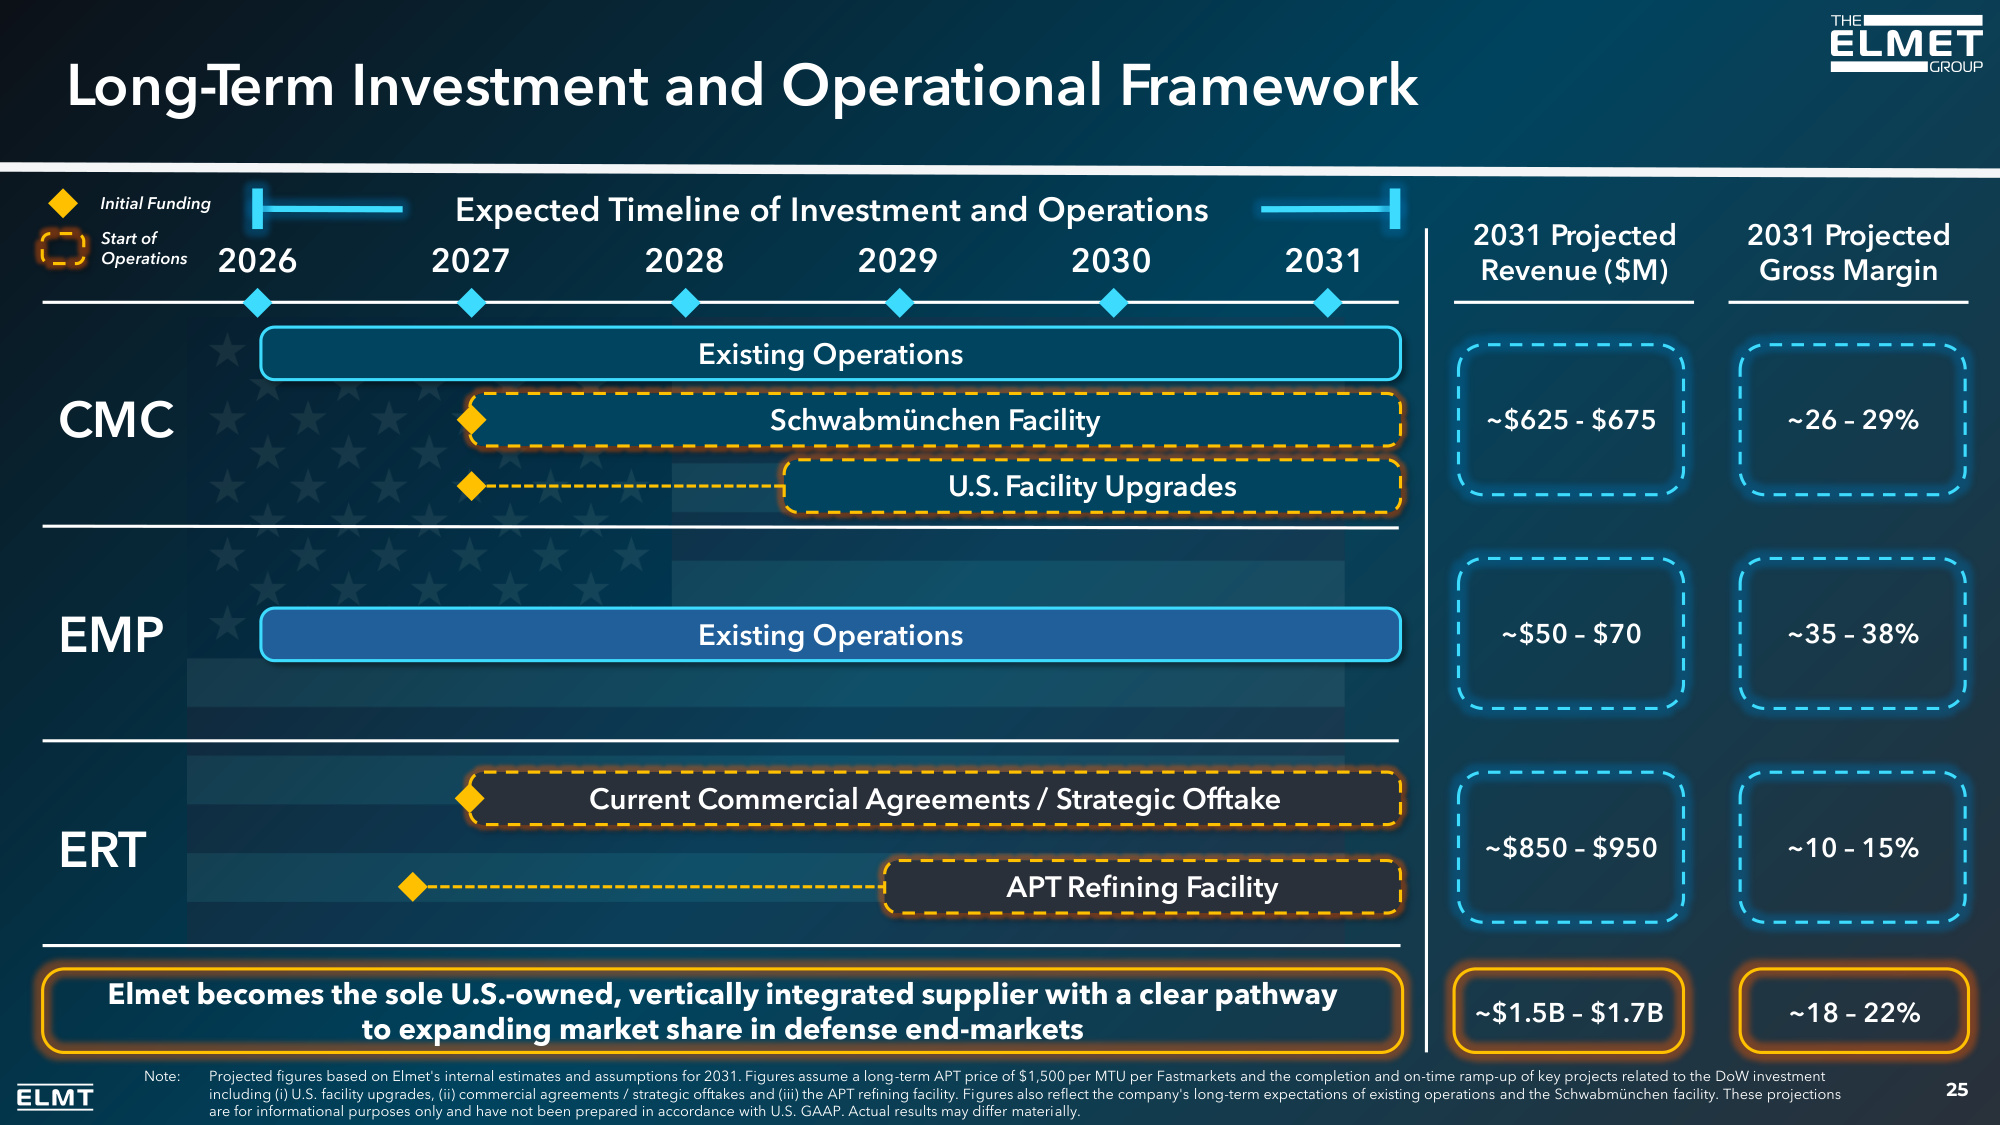
Long-Term Investment and Operational Framework 25 CMC EMP ERT 2026 2029 2027 2028 2030 2031 Existing Operations Schwabmünchen Facility U.S. Facility Upgrades Existing Operations Current Commercial Agreements / Strategic Offtake APT Refining Facility ~$50 – $70 Start of Operations Initial Funding ~$625 - $675 ~$850 – $950 Note: Projected figures based on Elmet's internal estimates and assumptions for 2031. Figures assume a long-term APT price of $1,500 per MTU per Fastmarkets and the completion and on-time ramp-up of key projects related to the DoW investment including (i) U.S. facility upgrades, (ii) commercial agreements / strategic offtakes and (iii) the APT refining facility. Figures also reflect the company's long-term expectations of existing operations and the Schwabmünchen facility. These projections are for informational purposes only and have not been prepared in accordance with U.S. GAAP. Actual results may differ materially. Elmet becomes the sole U.S.-owned, vertically integrated supplier with a clear pathway to expanding market share in defense end-markets 2031 Projected Gross Margin ~26 – 29% ~35 – 38% ~10 – 15% Expected Timeline of Investment and Operations ~$1.5B – $1.7B ~18 – 22% 2031 Projected Revenue ($M)
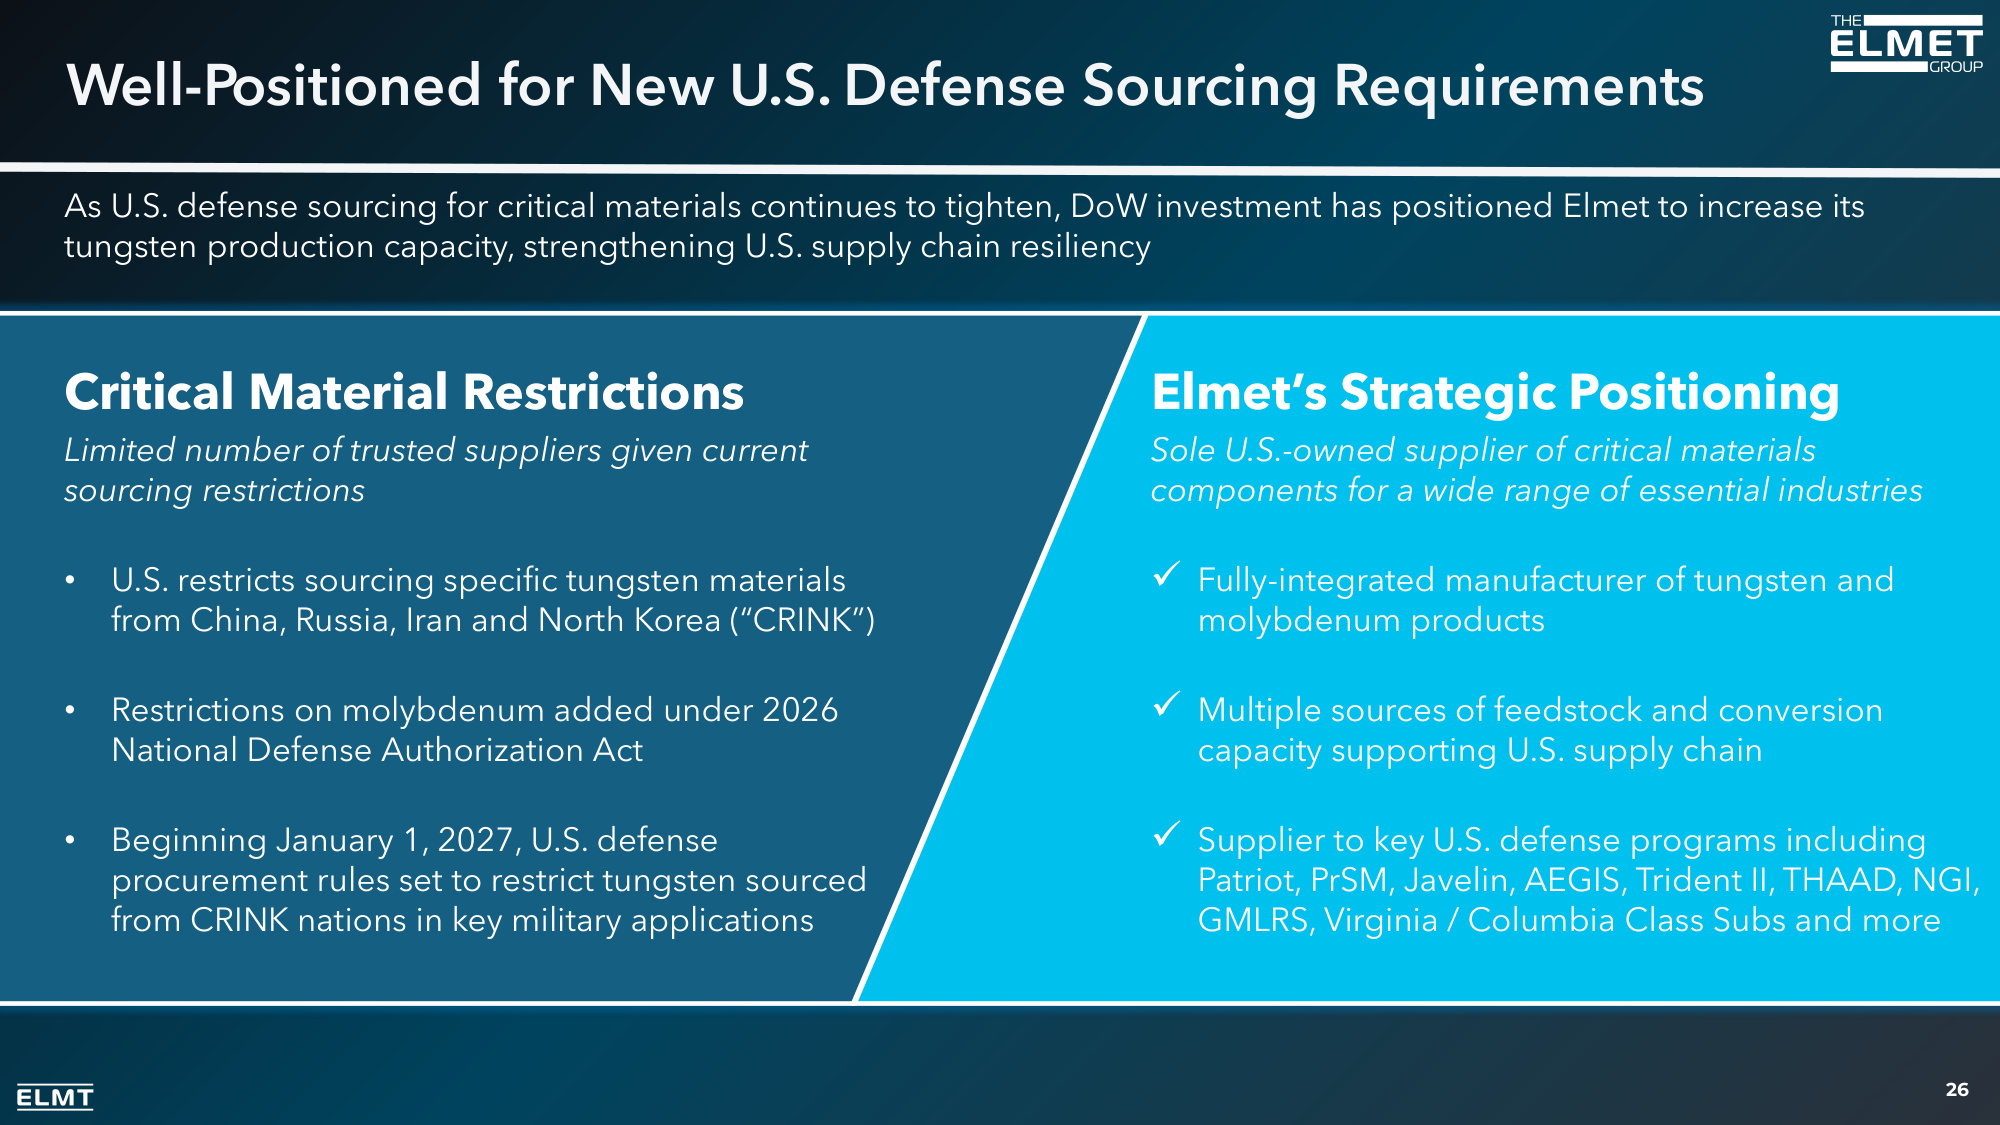
Well-Positioned for New U.S. Defense Sourcing Requirements 26 As U.S. defense sourcing for critical materials continues to tighten, DoW investment has positioned Elmet to increase its tungsten production capacity, strengthening U.S. supply chain resiliency Critical Material Restrictions Limited number of trusted suppliers given current sourcing restrictions • U.S. restricts sourcing specific tungsten materials from China, Russia, Iran and North Korea ("CRINK") • Restrictions on molybdenum added under 2026 National Defense Authorization Act • Beginning January 1, 2027, U.S. defense procurement rules set to restrict tungsten sourced from CRINK nations in key military applications Elmet's Strategic Positioning Sole U.S.-owned supplier of critical materials components for a wide range of essential industries ✓Fully-integrated manufacturer of tungsten and molybdenum products ✓Multiple sources of feedstock and conversion capacity supporting U.S. supply chain ✓Supplier to key U.S. defense programs including Patriot, PrSM, Javelin, AEGIS, Trident II, THAAD, NGI, GMLRS, Virginia / Columbia Class Subs and more
F i n a n c i a l U p d a t e
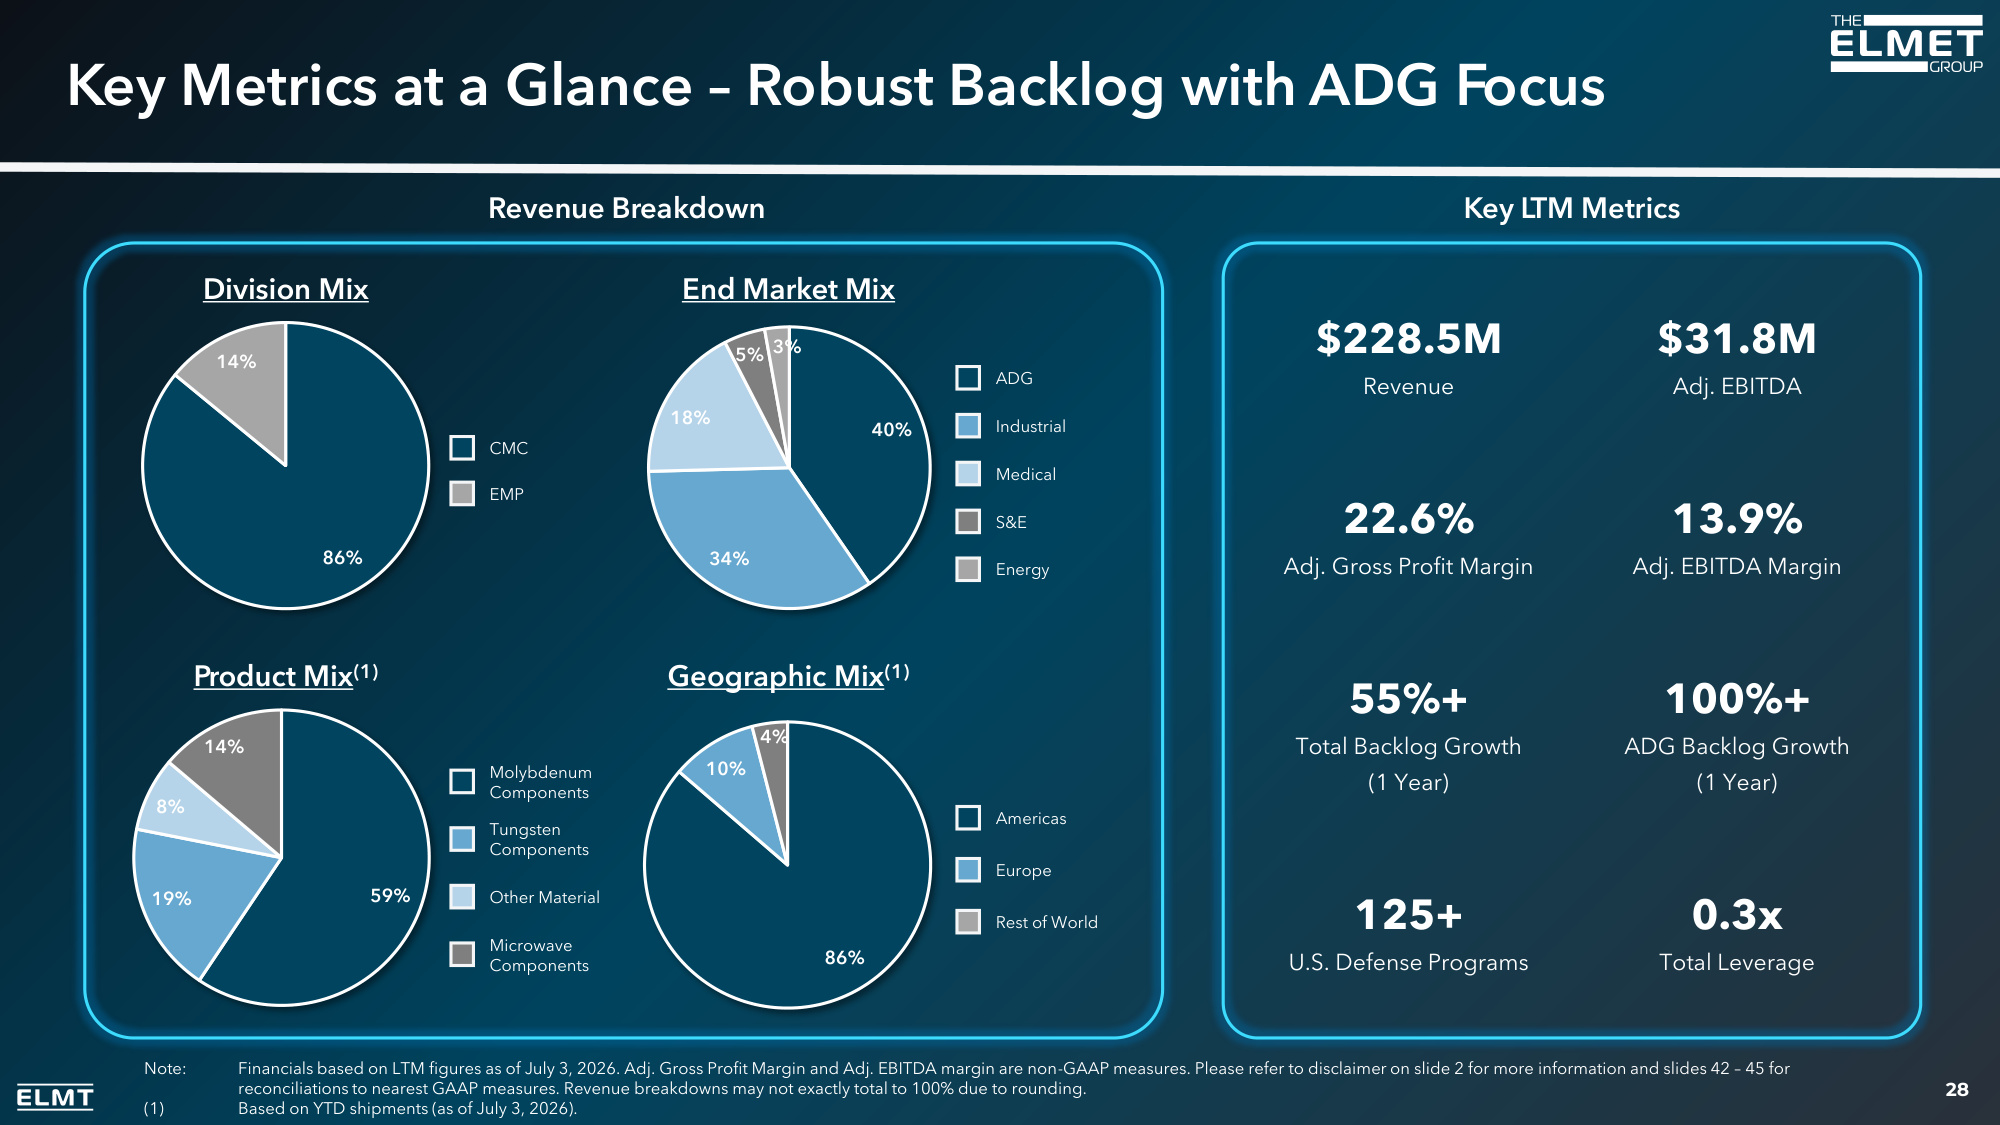
86% 10% 4% 59% 19% 8% 14% 28 Key LTM Metrics Revenue Breakdown 40% 34% 18% 5% 3% 86% 14% End Market Mix CMC EMP ADG Industrial Medical S&E Energy Division Mix $228.5M Revenue $31.8M Adj. EBITDA 13.9% Adj. EBITDA Margin 22.6% Adj. Gross Profit Margin 100%+ ADG Backlog Growth (1 Year) 55%+ Total Backlog Growth (1 Year) 0.3x Total Leverage 125+ U.S. Defense Programs Geographic Mix(1) Product Mix(1) Americas Rest of World Molybdenum Components Tungsten Components Other Material Microwave Components Key Metrics at a Glance – Robust Backlog with ADG Focus Europe Note: Financials based on LTM figures as of July 3, 2026. Adj. Gross Profit Margin and Adj. EBITDA margin are non-GAAP measures. Please refer to disclaimer on slide 2 for more information and slides 42 – 45 for reconciliations to nearest GAAP measures. Revenue breakdowns may not exactly total to 100% due to rounding. (1) Based on YTD shipments (as of July 3, 2026).
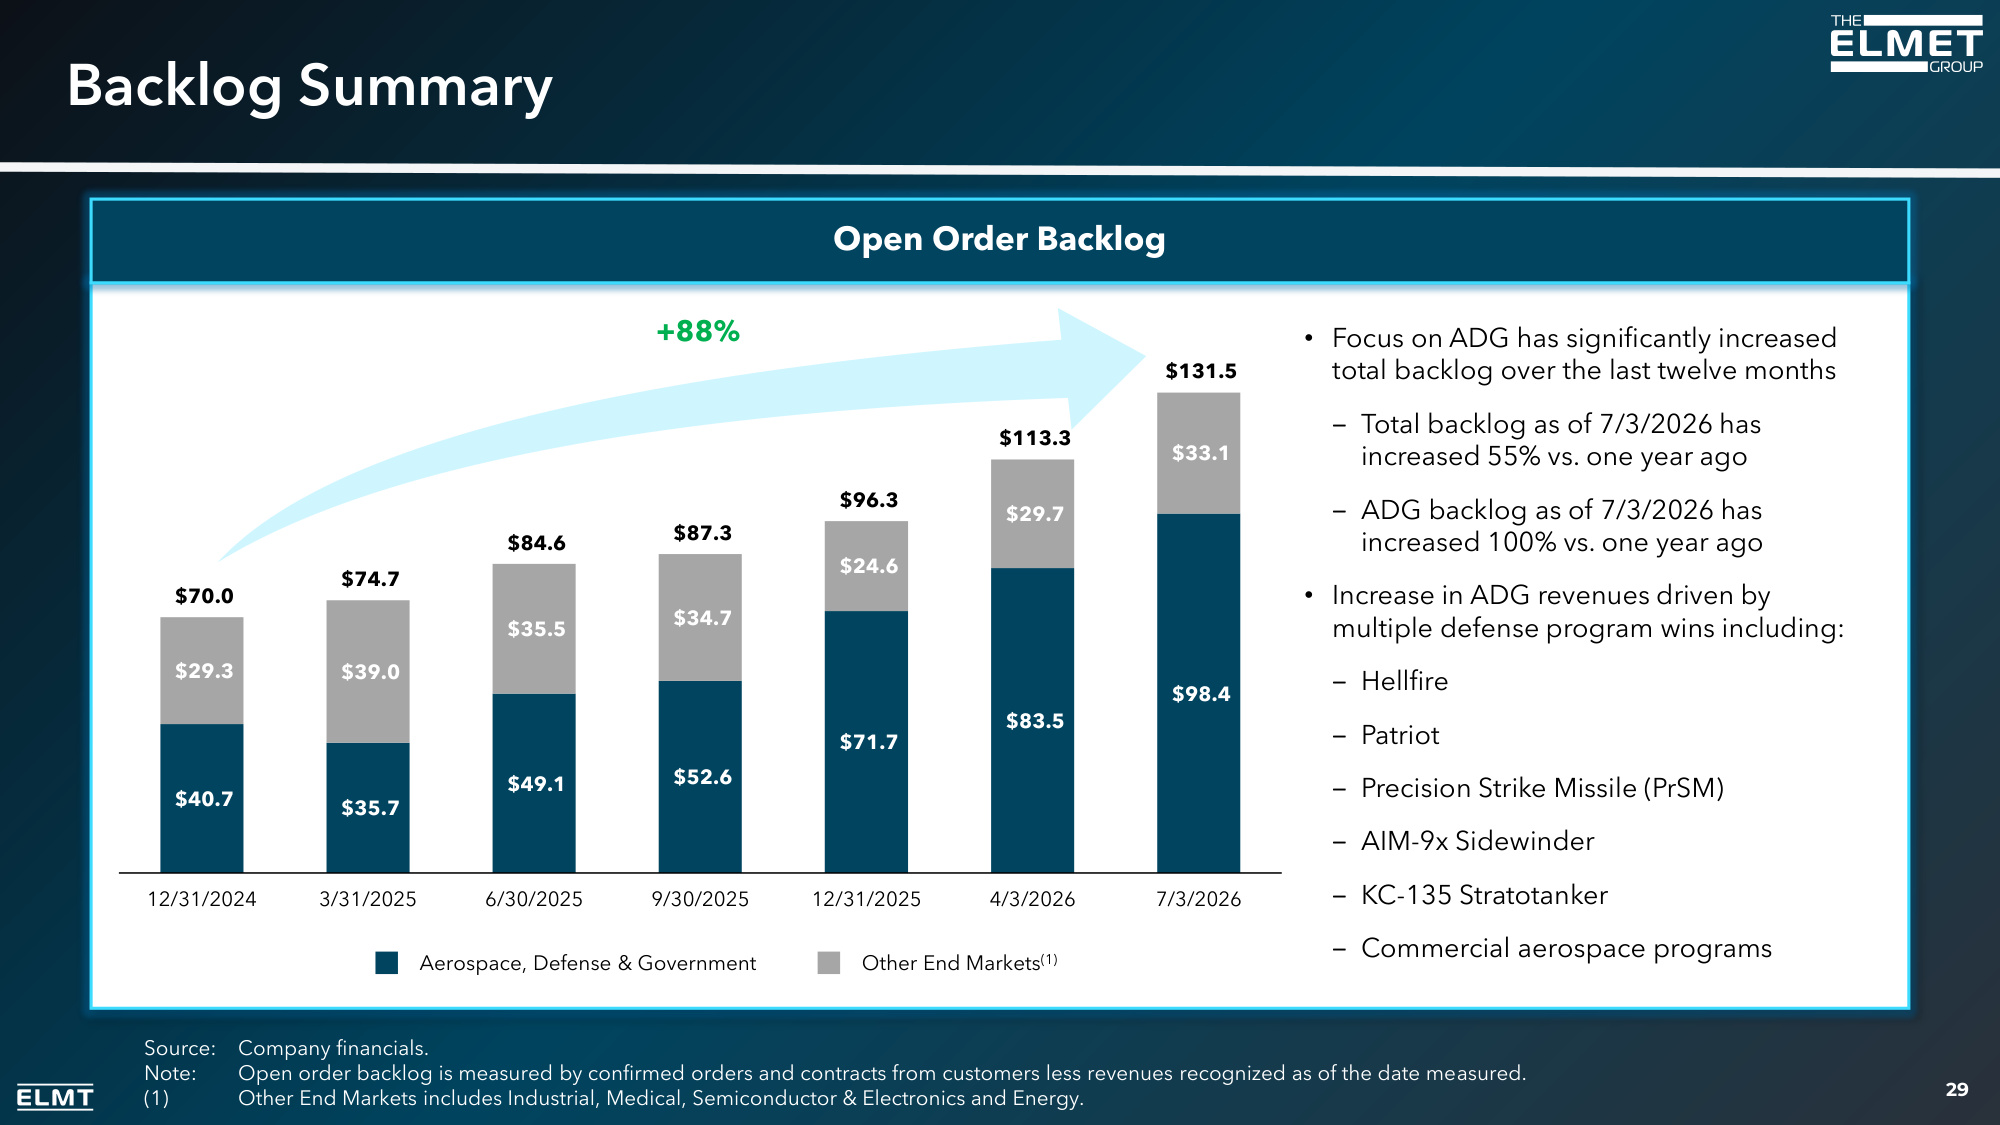
Backlog Summary 29 Source: Company financials. Note: Open order backlog is measured by confirmed orders and contracts from customers less revenues recognized as of the date measured. (1) Other End Markets includes Industrial, Medical, Semiconductor & Electronics and Energy. Aerospace, Defense & Government Other End Markets(1) +88% Open Order Backlog $40.7 $35.7 $49.1 $52.6 $71.7 $83.5 $98.4 $29.3 $39.0 $35.5 $34.7 $24.6 $29.7 $33.1 $70.0 $74.7 $84.6 $87.3 $96.3 $113.3 $131.5 12/31/2024 3/31/2025 6/30/2025 9/30/2025 12/31/2025 4/3/2026 7/3/2026 • Focus on ADG has significantly increased total backlog over the last twelve months ‒ Total backlog as of 7/3/2026 has increased 55% vs. one year ago ‒ ADG backlog as of 7/3/2026 has increased 100% vs. one year ago • Increase in ADG revenues driven by multiple defense program wins including: ‒ Hellfire ‒ Patriot ‒ Precision Strike Missile (PrSM) ‒ AIM-9x Sidewinder ‒ KC-135 Stratotanker ‒ Commercial aerospace programs
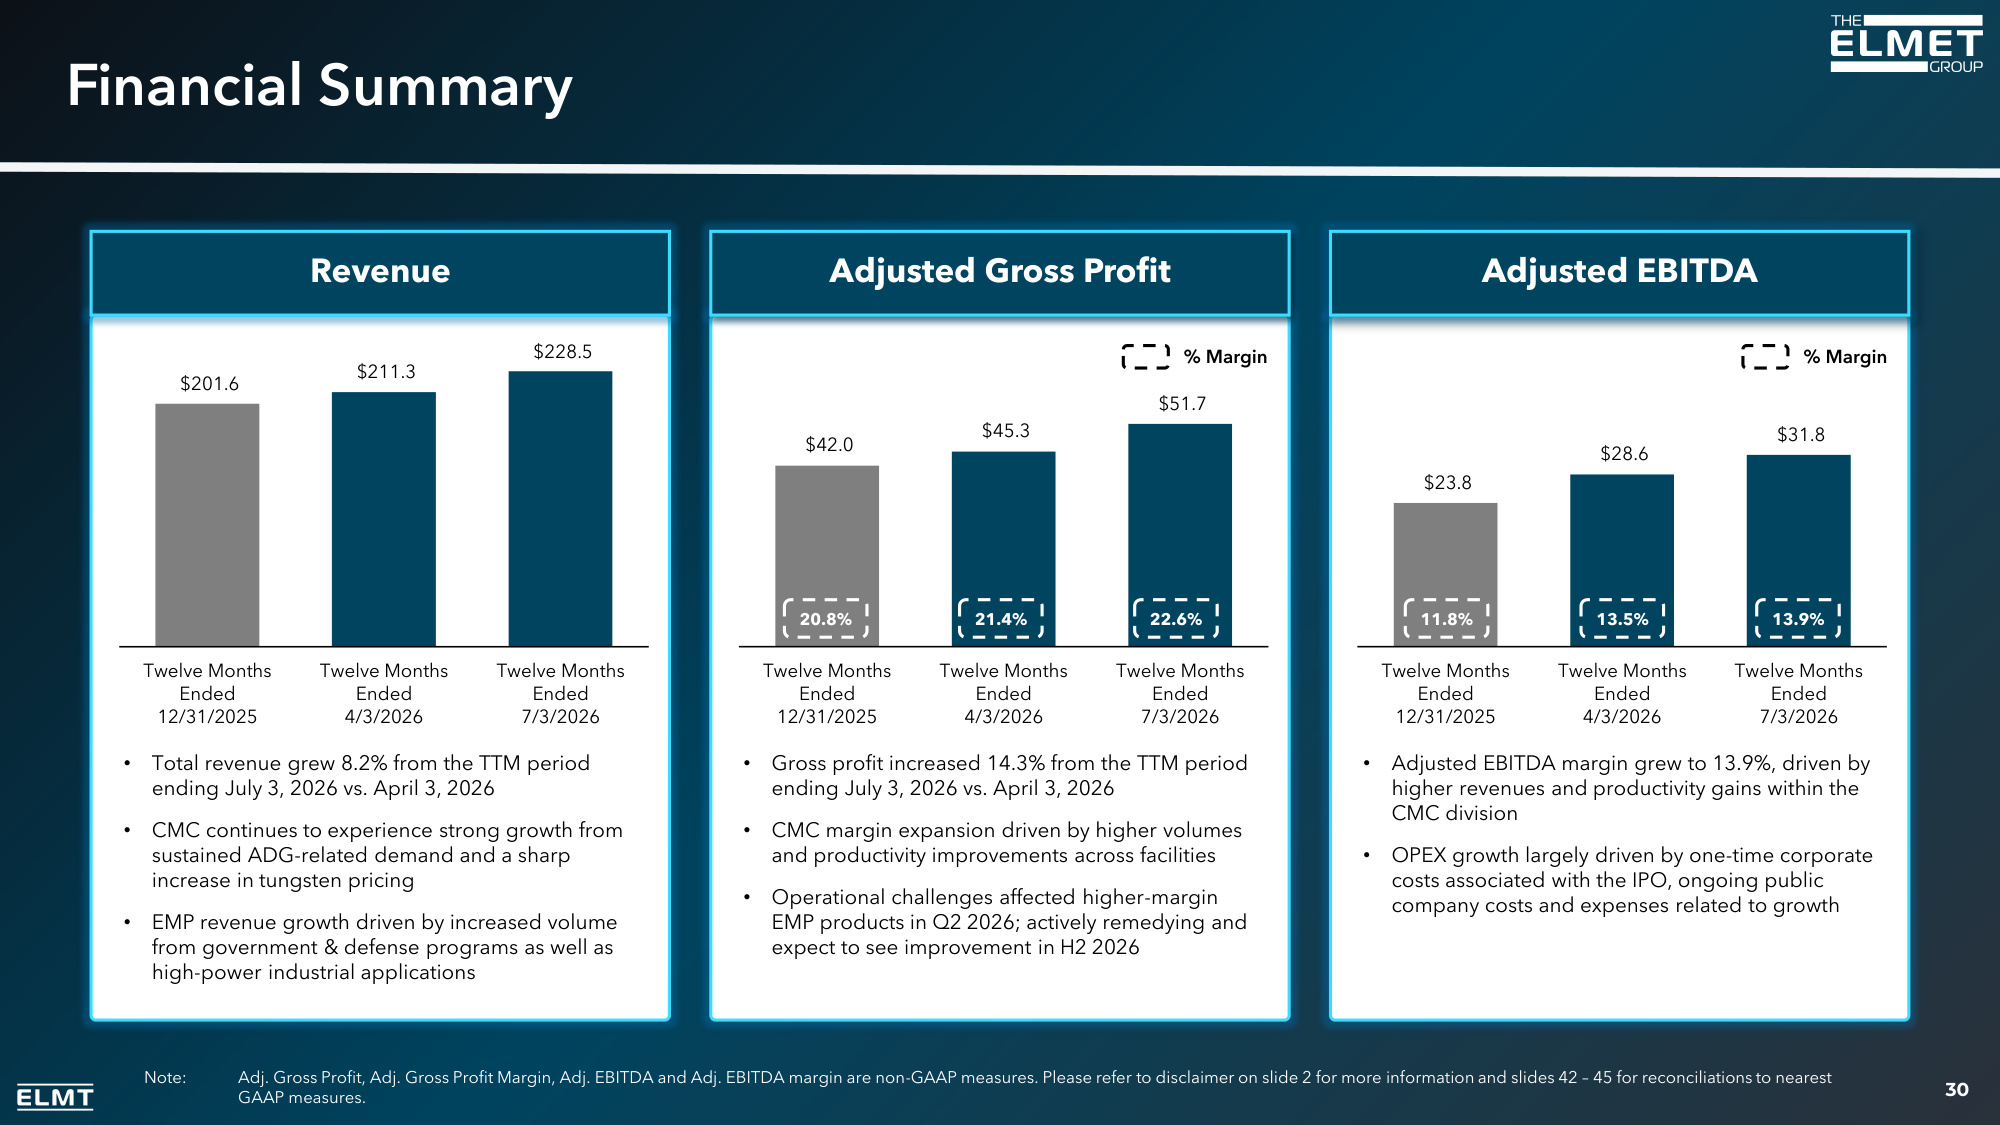
Financial Summary 30 Revenue • Total revenue grew 8.2% from the TTM period ending July 3, 2026 vs. April 3, 2026 • CMC continues to experience strong growth from sustained ADG-related demand and a sharp increase in tungsten pricing • EMP revenue growth driven by increased volume from government & defense programs as well as high-power industrial applications Adjusted Gross Profit • Gross profit increased 14.3% from the TTM period ending July 3, 2026 vs. April 3, 2026 • CMC margin expansion driven by higher volumes and productivity improvements across facilities • Operational challenges affected higher-margin EMP products in Q2 2026; actively remedying and expect to see improvement in H2 2026 Adjusted EBITDA • Adjusted EBITDA margin grew to 13.9%, driven by higher revenues and productivity gains within the CMC division • OPEX growth largely driven by one-time corporate costs associated with the IPO, ongoing public company costs and expenses related to growth % Margin % Margin $201.6 $211.3 $228.5 Twelve Months Ended 12/31/2025 Twelve Months Ended 4/3/2026 Twelve Months Ended 7/3/2026 Note: Adj. Gross Profit, Adj. Gross Profit Margin, Adj. EBITDA and Adj. EBITDA margin are non-GAAP measures. Please refer to disclaimer on slide 2 for more information and slides 42 – 45 for reconciliations to nearest GAAP measures. $42.0 $45.3 $51.7 Twelve Months Ended 12/31/2025 Twelve Months Ended 4/3/2026 Twelve Months Ended 7/3/2026 20.8% $23.8 $28.6 $31.8 Twelve Months Ended 12/31/2025 Twelve Months Ended 4/3/2026 Twelve Months Ended 7/3/2026 11.8% 13.9% 22.6% 21.4% 13.5%
K e y Ta k e a w a y s a n d I n v e s t m e n t H i g h l i g h t s
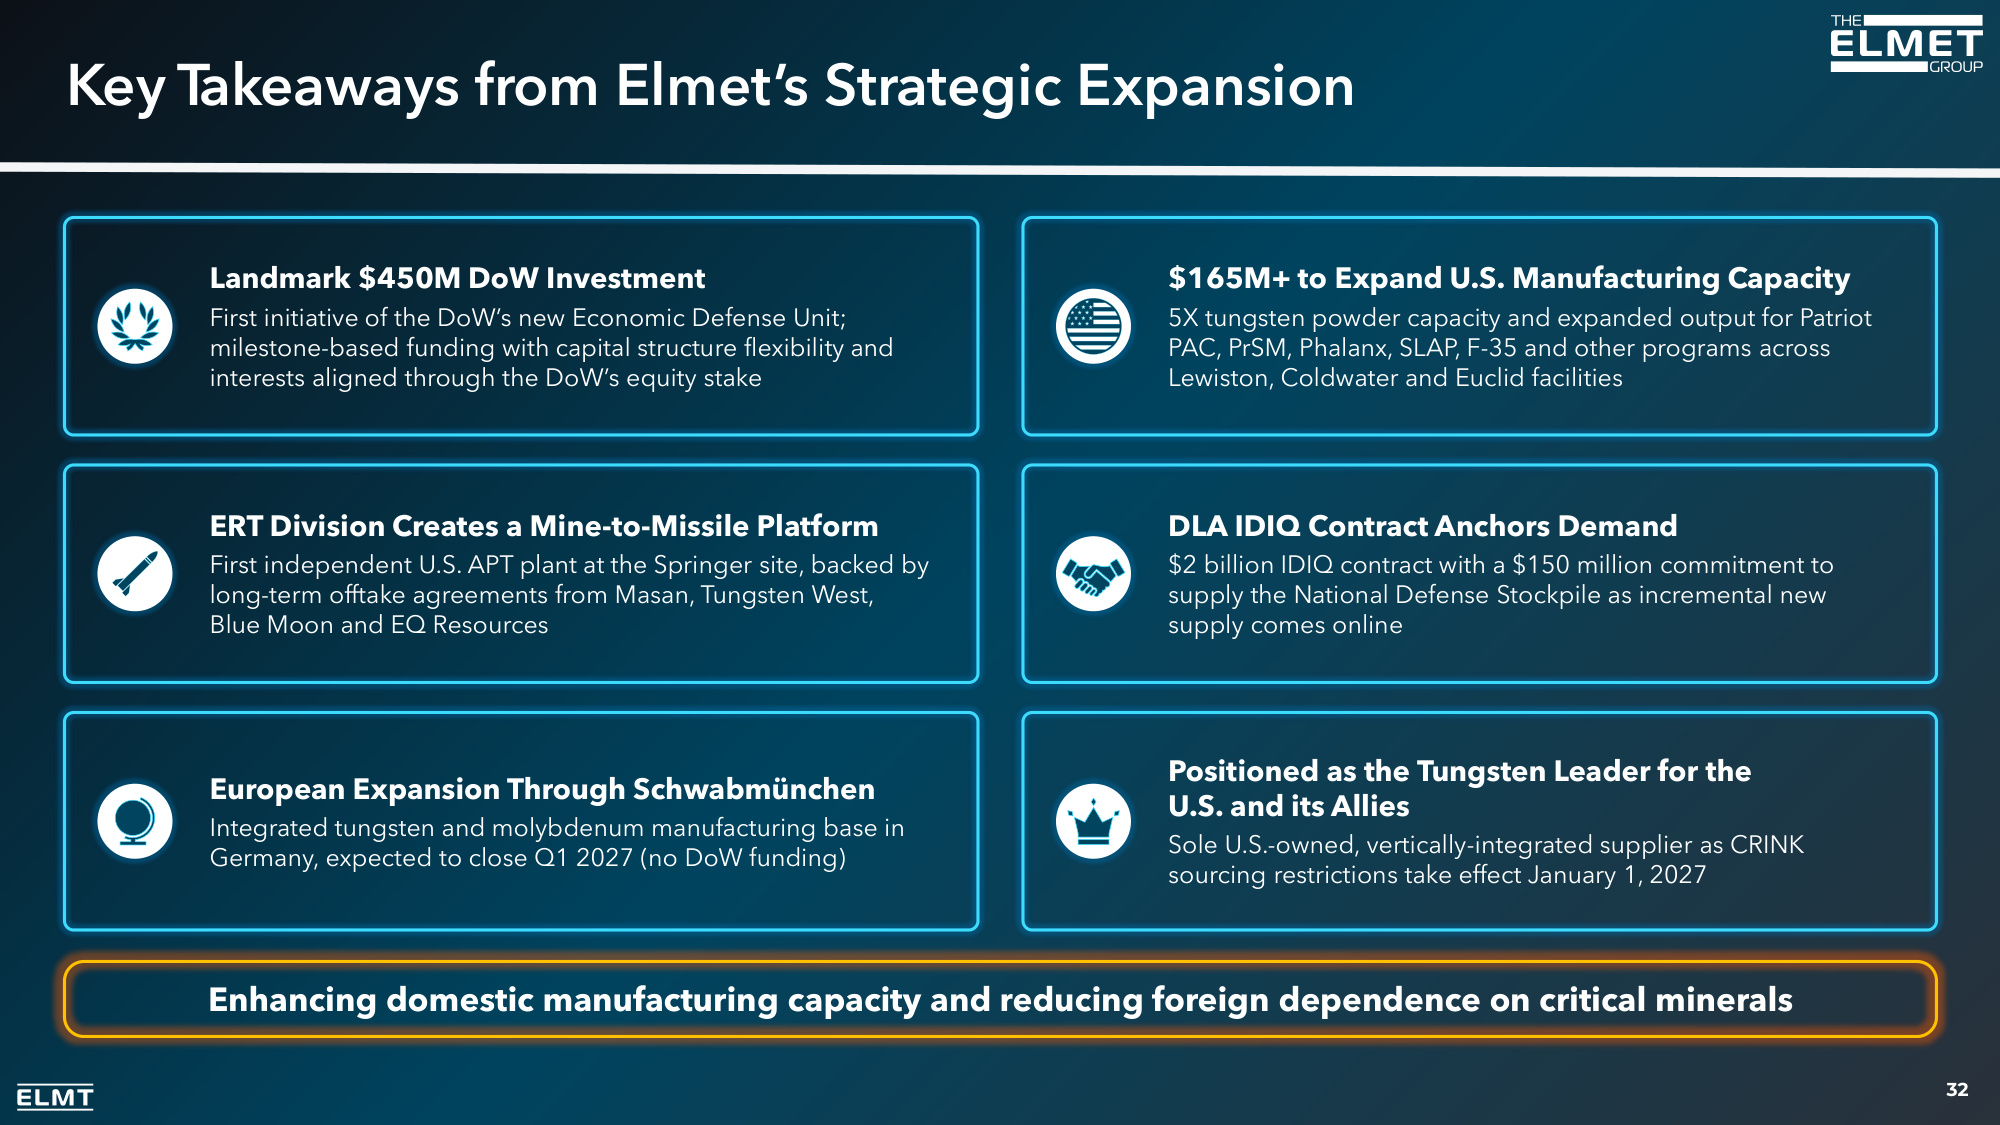
Key Takeaways from Elmet's Strategic Expansion 32 Landmark $450M DoW Investment First initiative of the DoW's new Economic Defense Unit; milestone-based funding with capital structure flexibility and interests aligned through the DoW's equity stake $165M+ to Expand U.S. Manufacturing Capacity 5X tungsten powder capacity and expanded output for Patriot PAC, PrSM, Phalanx, SLAP, F-35 and other programs across Lewiston, Coldwater and Euclid facilities ERT Division Creates a Mine-to-Missile Platform First independent U.S. APT plant at the Springer site, backed by long-term offtake agreements from Masan, Tungsten West, Blue Moon and EQ Resources DLA IDIQ Contract Anchors Demand $2 billion IDIQ contract with a $150 million commitment to supply the National Defense Stockpile as incremental new supply comes online European Expansion Through Schwabmünchen Integrated tungsten and molybdenum manufacturing base in Germany, expected to close Q1 2027 (no DoW funding) Positioned as the Tungsten Leader for the U.S. and its Allies Sole U.S.-owned, vertically-integrated supplier as CRINK sourcing restrictions take effect January 1, 2027 Enhancing domestic manufacturing capacity and reducing foreign dependence on critical minerals
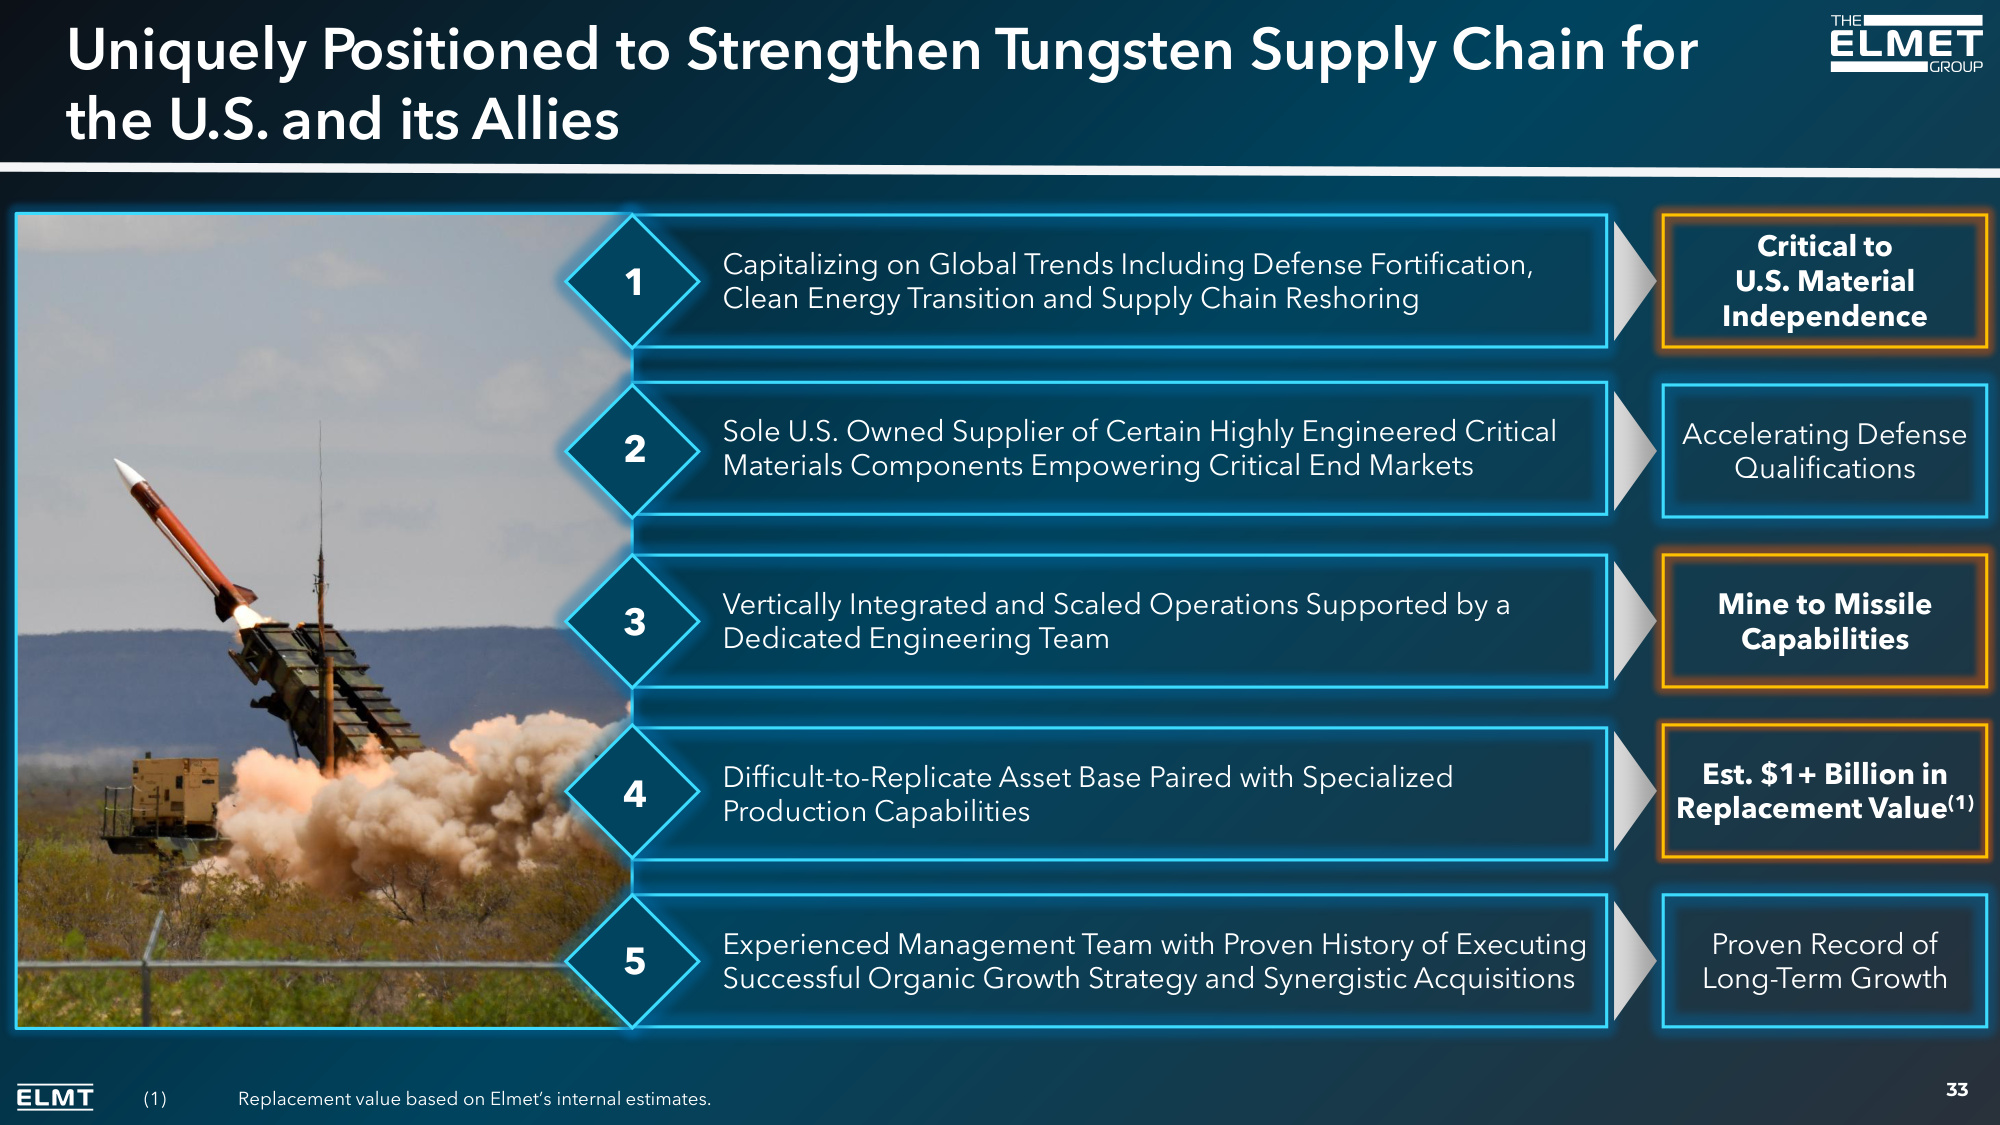
33 Capitalizing on Global Trends Including Defense Fortification, Clean Energy Transition and Supply Chain Reshoring 1 Sole U.S. Owned Supplier of Certain Highly Engineered Critical Materials Components Empowering Critical End Markets 2 Vertically Integrated and Scaled Operations Supported by a Dedicated Engineering Team 3 Difficult-to-Replicate Asset Base Paired with Specialized Production Capabilities 4 Experienced Management Team with Proven History of Executing Successful Organic Growth Strategy and Synergistic Acquisitions 5 Critical to U.S. Material Independence Accelerating Defense Qualifications Mine to Missile Capabilities Est. $1+ Billion in Replacement Value(1) Proven Record of Long-Term Growth (1) Replacement value based on Elmet's internal estimates. Uniquely Positioned to Strengthen Tungsten Supply Chain for the U.S. and its Allies
A p p e n d i x
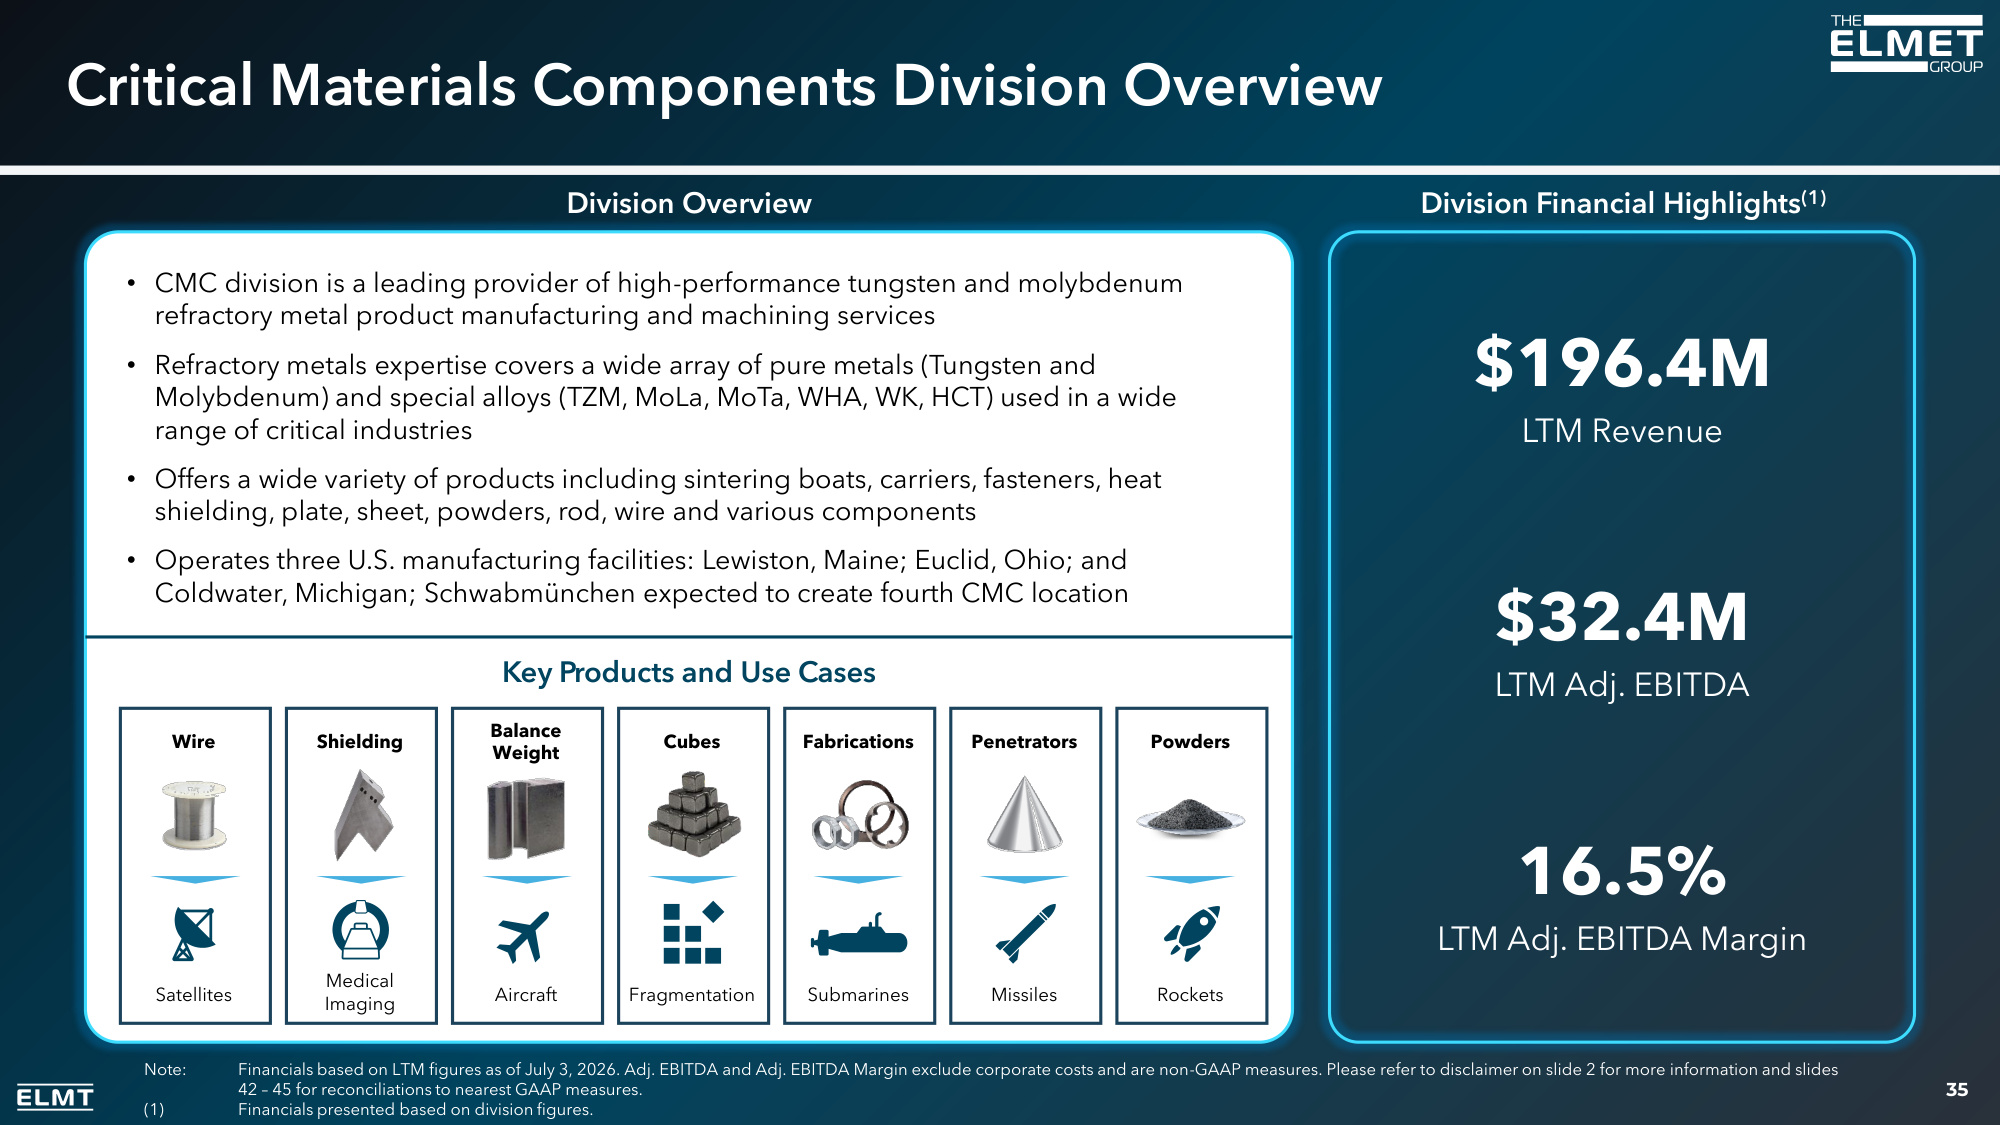
35 Division Financial Highlights(1) Division Overview • CMC division is a leading provider of high-performance tungsten and molybdenum refractory metal product manufacturing and machining services • Refractory metals expertise covers a wide array of pure metals (Tungsten and Molybdenum) and special alloys (TZM, MoLa, MoTa, WHA, WK, HCT) used in a wide range of critical industries • Offers a wide variety of products including sintering boats, carriers, fasteners, heat shielding, plate, sheet, powders, rod, wire and various components • Operates three U.S. manufacturing facilities: Lewiston, Maine; Euclid, Ohio; and Coldwater, Michigan; Schwabmünchen expected to create fourth CMC location $196.4M LTM Revenue $32.4M LTM Adj. EBITDA 16.5% LTM Adj. EBITDA Margin Note: Financials based on LTM figures as of July 3, 2026. Adj. EBITDA and Adj. EBITDA Margin exclude corporate costs and are non-GAAP measures. Please refer to disclaimer on slide 2 for more information and slides 42 – 45 for reconciliations to nearest GAAP measures. (1) Financials presented based on division figures. Balance Weight Cubes Shielding Penetrators Powders Fabrications Wire Key Products and Use Cases Aircraft Fragmentation Medical Imaging Missiles Rockets Submarines Satellites Critical Materials Components Division Overview
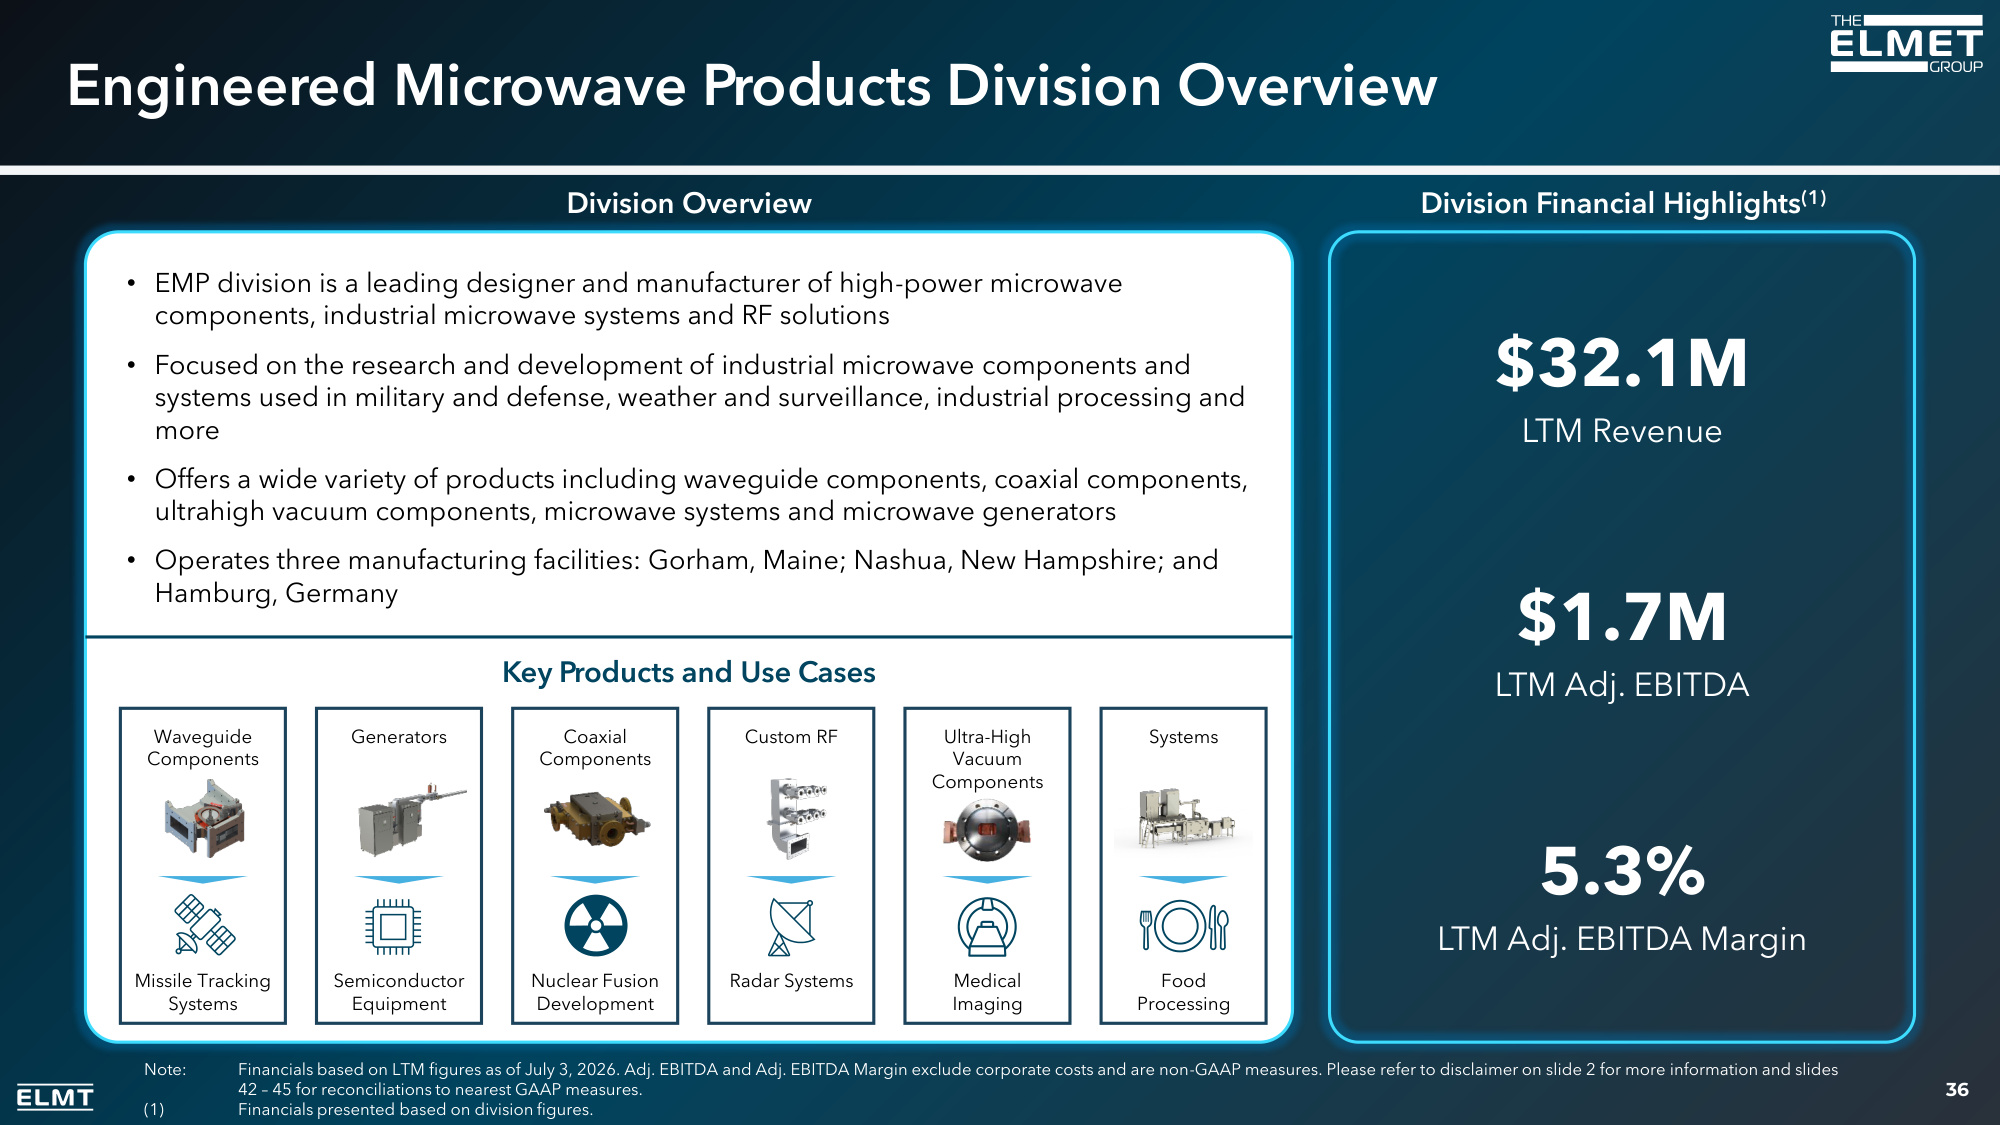
Systems Food Processing 36 Division Overview Division Financial Highlights(1) • EMP division is a leading designer and manufacturer of high-power microwave components, industrial microwave systems and RF solutions • Focused on the research and development of industrial microwave components and systems used in military and defense, weather and surveillance, industrial processing and more • Offers a wide variety of products including waveguide components, coaxial components, ultrahigh vacuum components, microwave systems and microwave generators • Operates three manufacturing facilities: Gorham, Maine; Nashua, New Hampshire; and Hamburg, Germany Waveguide Components Missile Tracking Systems Generators Semiconductor Equipment Coaxial Components Nuclear Fusion Development Custom RF Radar Systems Ultra-High Vacuum Components Medical Imaging $32.1M LTM Revenue $1.7M LTM Adj. EBITDA 5.3% LTM Adj. EBITDA Margin Engineered Microwave Products Division Overview Key Products and Use Cases Note: Financials based on LTM figures as of July 3, 2026. Adj. EBITDA and Adj. EBITDA Margin exclude corporate costs and are non-GAAP measures. Please refer to disclaimer on slide 2 for more information and slides 42 – 45 for reconciliations to nearest GAAP measures. (1) Financials presented based on division figures.
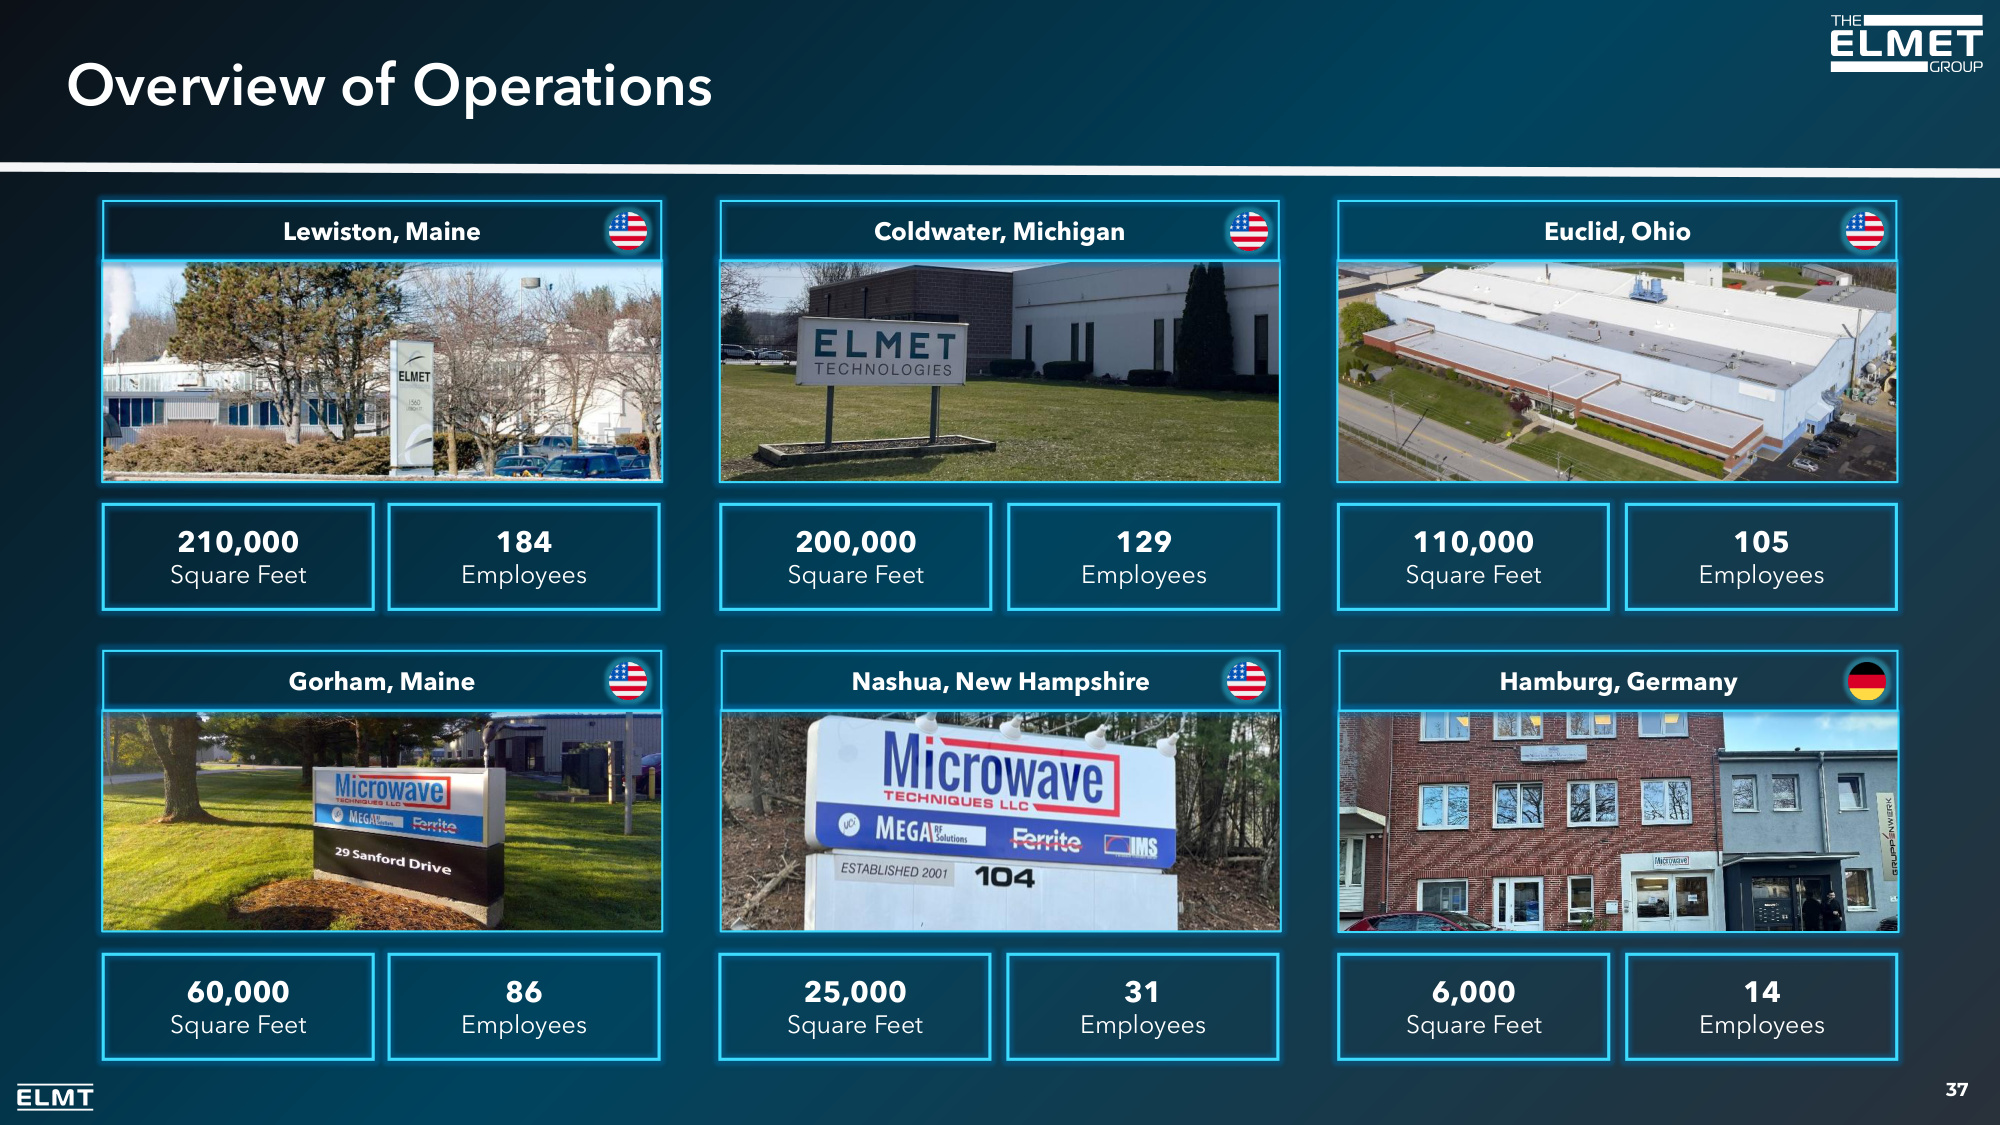
Euclid, Ohio 105 Employees 110,000 Square Feet 37 Coldwater, Michigan 129 Employees 200,000 Square Feet Lewiston, Maine 184 Employees 210,000 Square Feet Overview of Operations Hamburg, Germany Gorham, Maine Nashua, New Hampshire 86 Employees 60,000 Square Feet 31 Employees 25,000 Square Feet 14 Employees 6,000 Square Feet
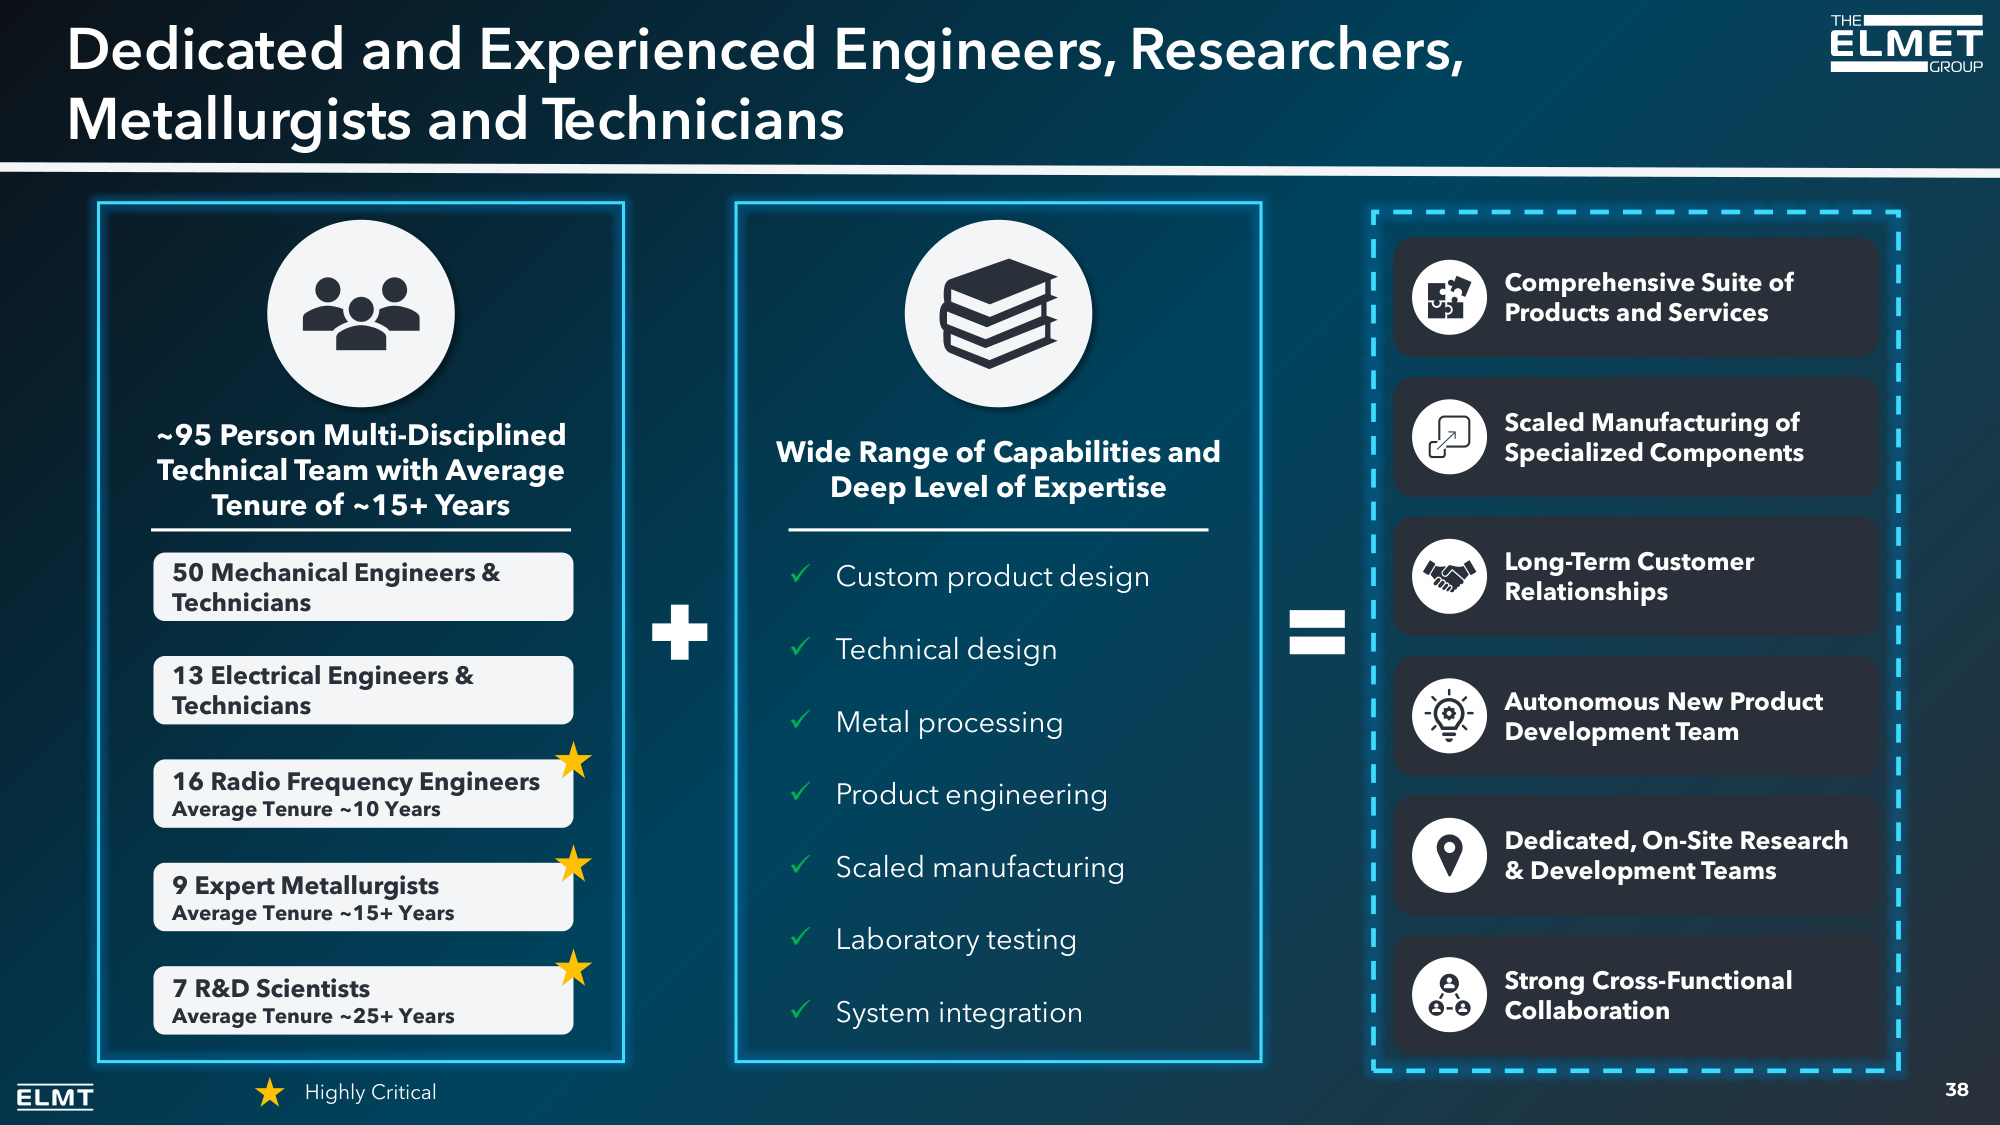
38 16 Radio Frequency Engineers Average Tenure ~10 Years 7 R&D Scientists Average Tenure ~25+ Years 13 Electrical Engineers & Technicians 9 Expert Metallurgists Average Tenure ~15+ Years ~95 Person Multi-Disciplined Technical Team with Average Tenure of ~15+ Years Wide Range of Capabilities and Deep Level of Expertise ✓ Custom product design ✓ Technical design ✓ Metal processing ✓ Product engineering ✓ Scaled manufacturing ✓ Laboratory testing ✓ System integration Comprehensive Suite of Products and Services Scaled Manufacturing of Specialized Components Long-Term Customer Relationships Autonomous New Product Development Team Dedicated, On-Site Research & Development Teams Strong Cross-Functional Collaboration 50 Mechanical Engineers & Technicians Highly Critical Dedicated and Experienced Engineers, Researchers, Metallurgists and Technicians
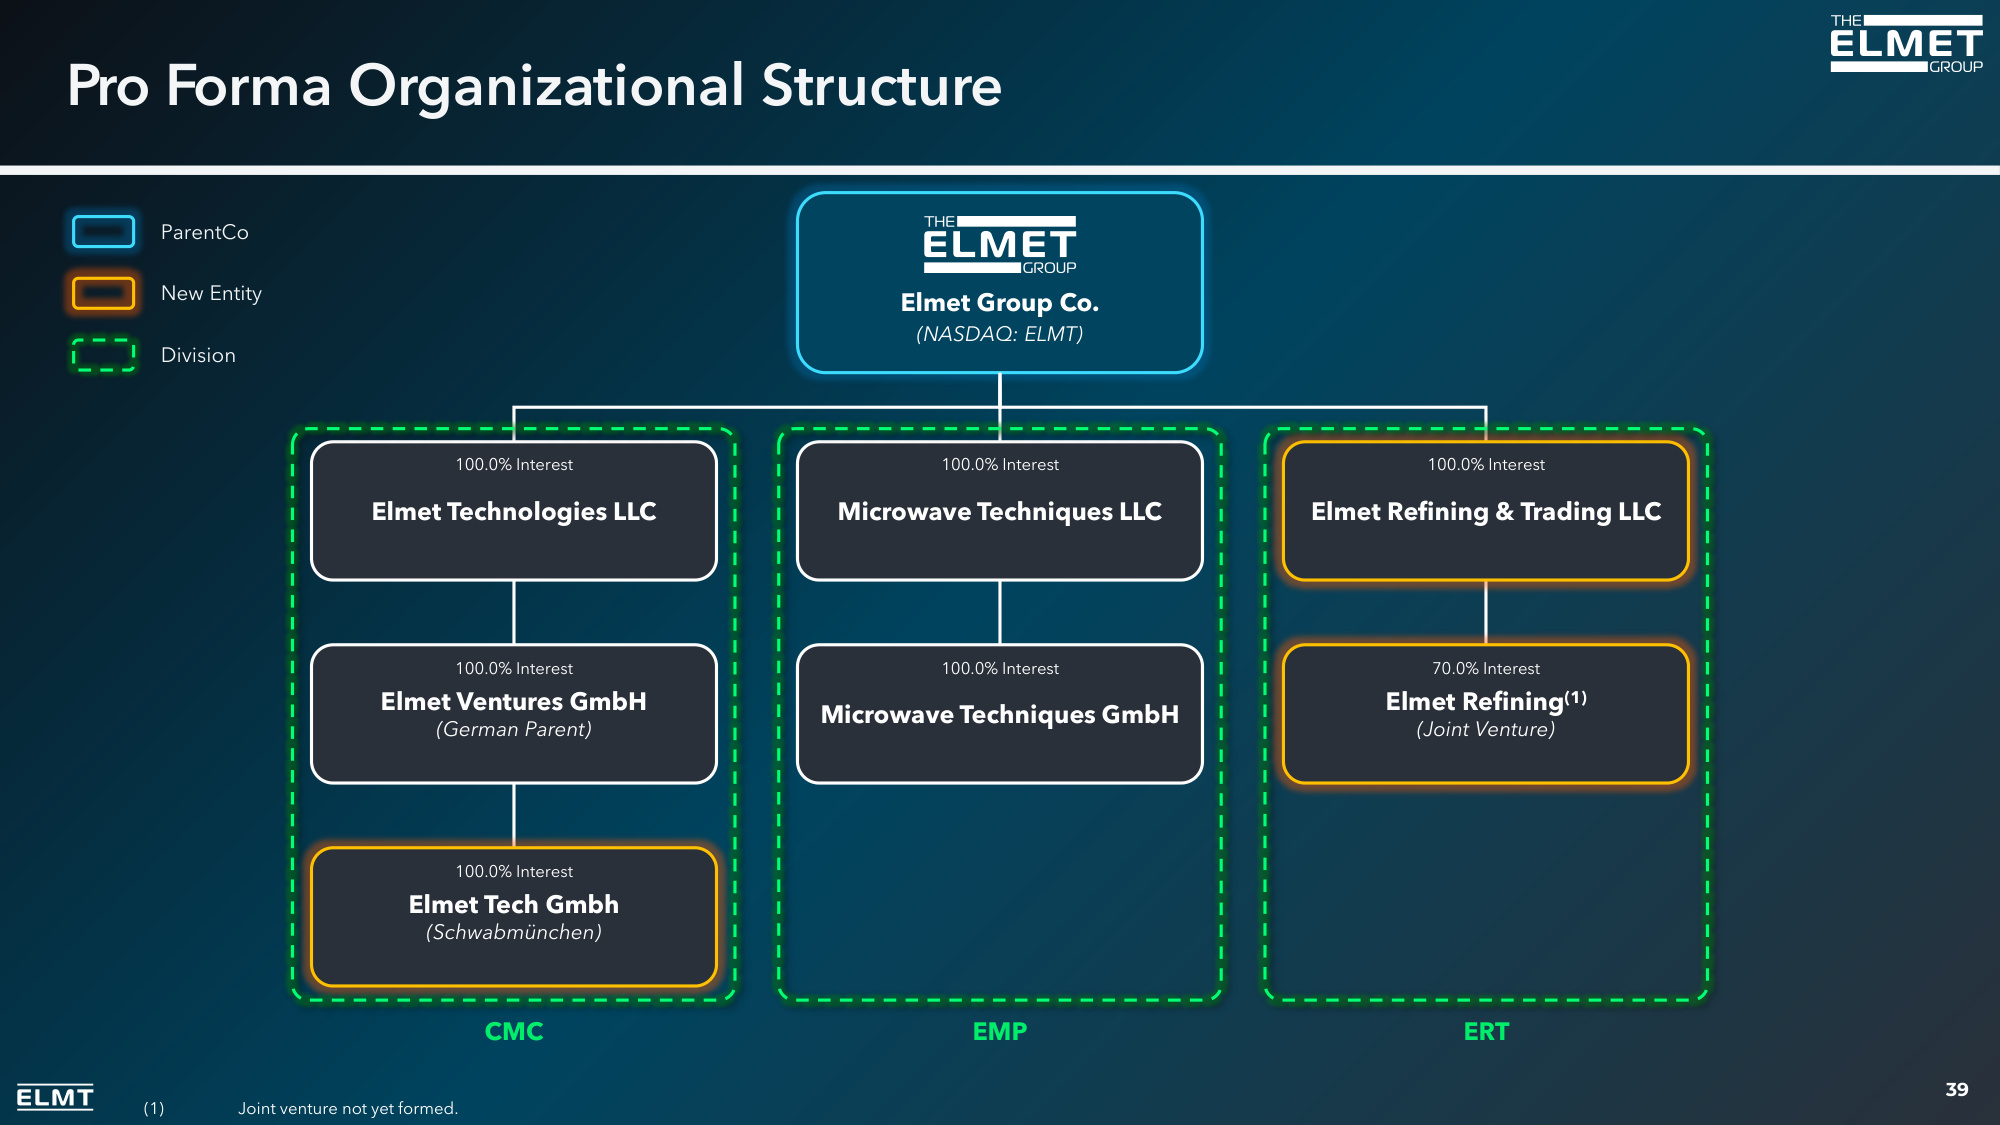
Pro Forma Organizational Structure 39 Elmet Group Co. (NASDAQ: ELMT) New Entity ParentCo Elmet Technologies LLC 100.0% Interest Microwave Techniques LLC 100.0% Interest Elmet Refining & Trading LLC 100.0% Interest Elmet Ventures GmbH (German Parent) 100.0% Interest Microwave Techniques GmbH 100.0% Interest Elmet Refining(1) (Joint Venture) 70.0% Interest Elmet Tech Gmbh (Schwabmünchen) 100.0% Interest CMC EMP ERT Division (1) Joint venture not yet formed.
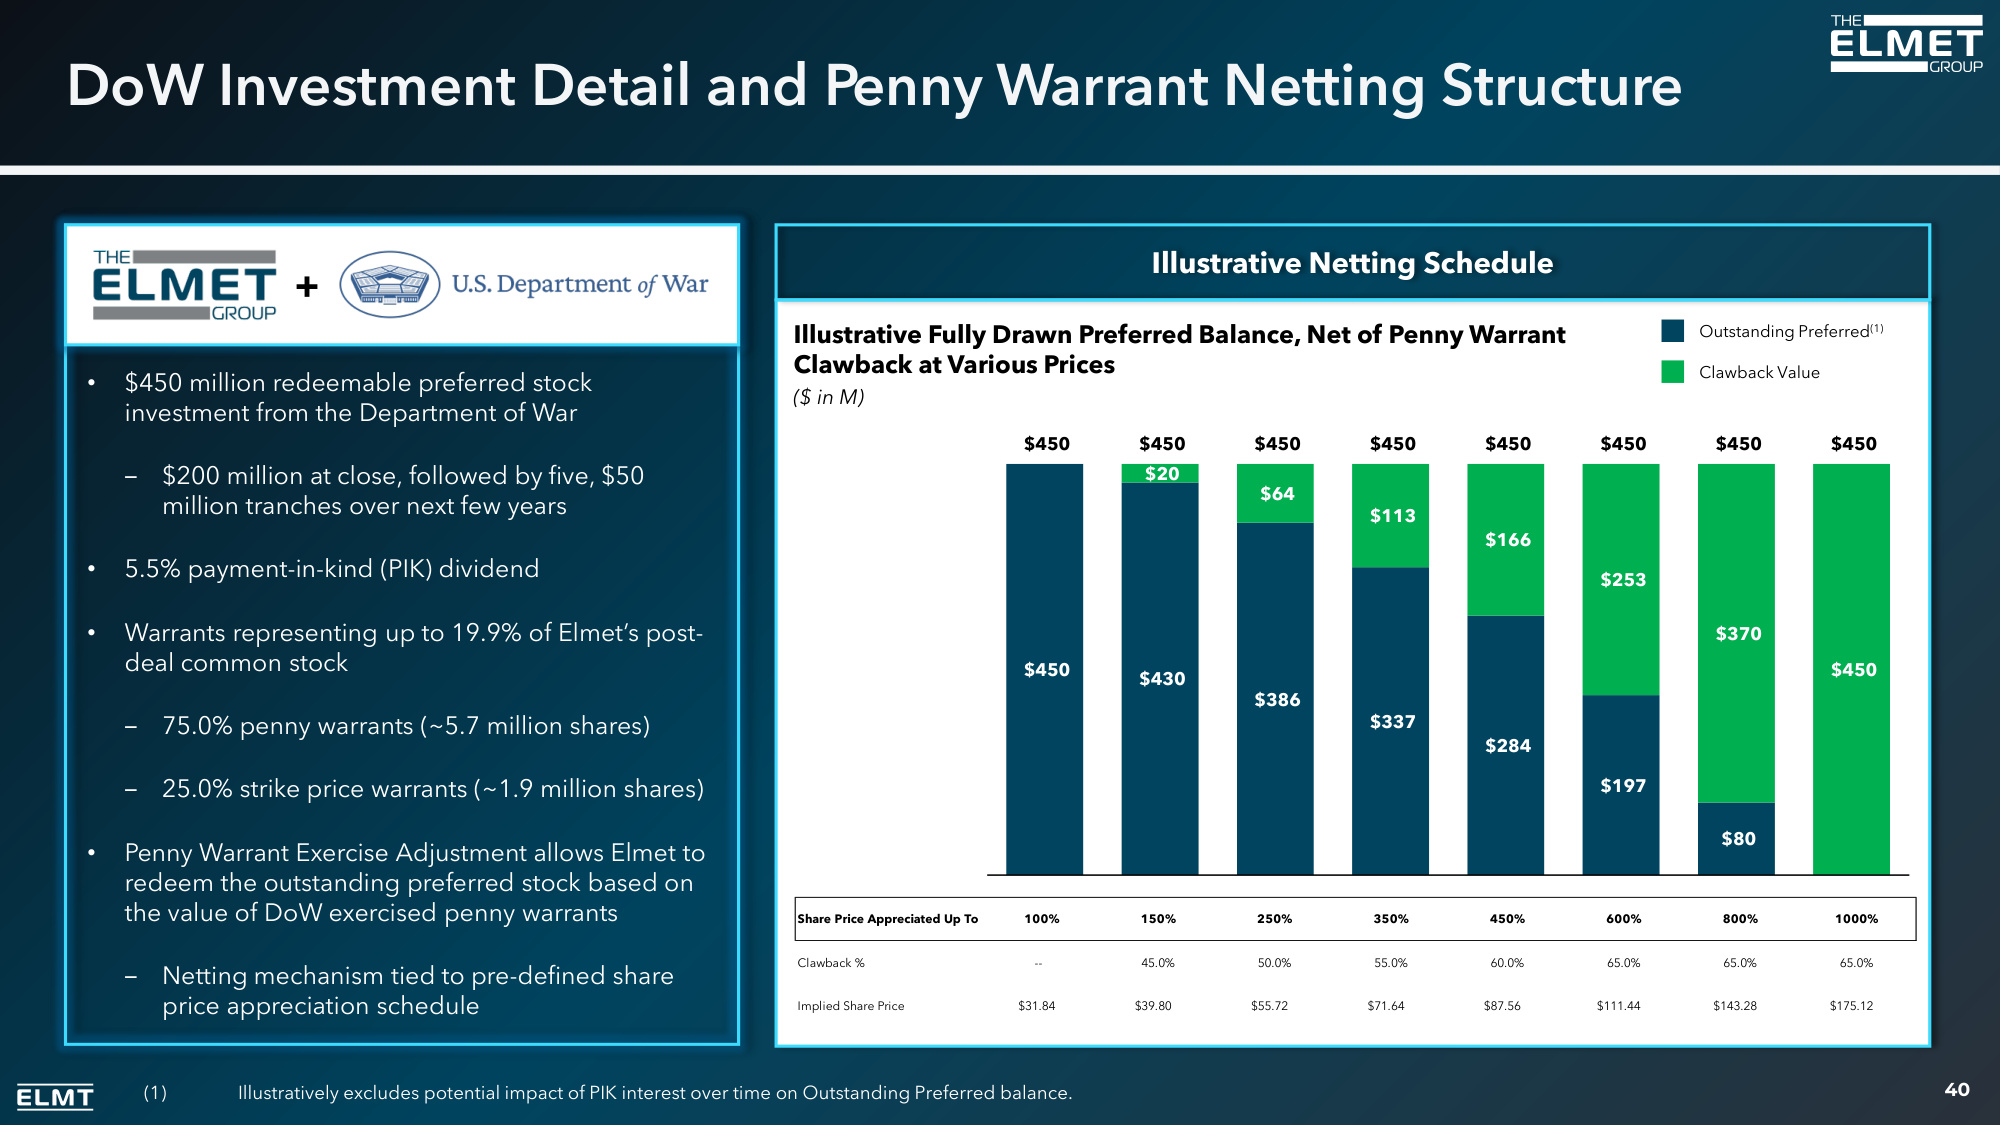
DoW Investment Detail and Penny Warrant Netting Structure 40 + Illustrative Netting Schedule • $450 million redeemable preferred stock investment from the Department of War ‒ $200 million at close, followed by five, $50 million tranches over next few years • 5.5% payment-in-kind (PIK) dividend • Warrants representing up to 19.9% of Elmet's post- deal common stock ‒ 75.0% penny warrants (~5.7 million shares) ‒ 25.0% strike price warrants (~1.9 million shares) • Penny Warrant Exercise Adjustment allows Elmet to redeem the outstanding preferred stock based on the value of DoW exercised penny warrants ‒ Netting mechanism tied to pre-defined share price appreciation schedule Clawback Value Illustrative Fully Drawn Preferred Balance, Net of Penny Warrant Clawback at Various Prices ($ in M) Outstanding Preferred(1) $450 $430 $386 $337 $284 $197 $80 $20 $64 $113 $166 $253 $370 $450 $450 $450 $450 $450 $450 $450 $450 $450 0% - 100% 100% - 150% 200% - 250% 300% - 350% 400% - 450% 500% - 600% 700% - 800% 900% - 1000% Share Price Appreciated Up To 100% 150% 250% 350% 450% 600% 800% 1000% Clawback % -- 45.0% 50.0% 55.0% 60.0% 65.0% 65.0% 65.0% Implied Share Price $31.84 $39.80 $55.72 $71.64 $87.56 $111.44 $143.28 $175.12 (1) Illustratively excludes potential impact of PIK interest over time on Outstanding Preferred balance.
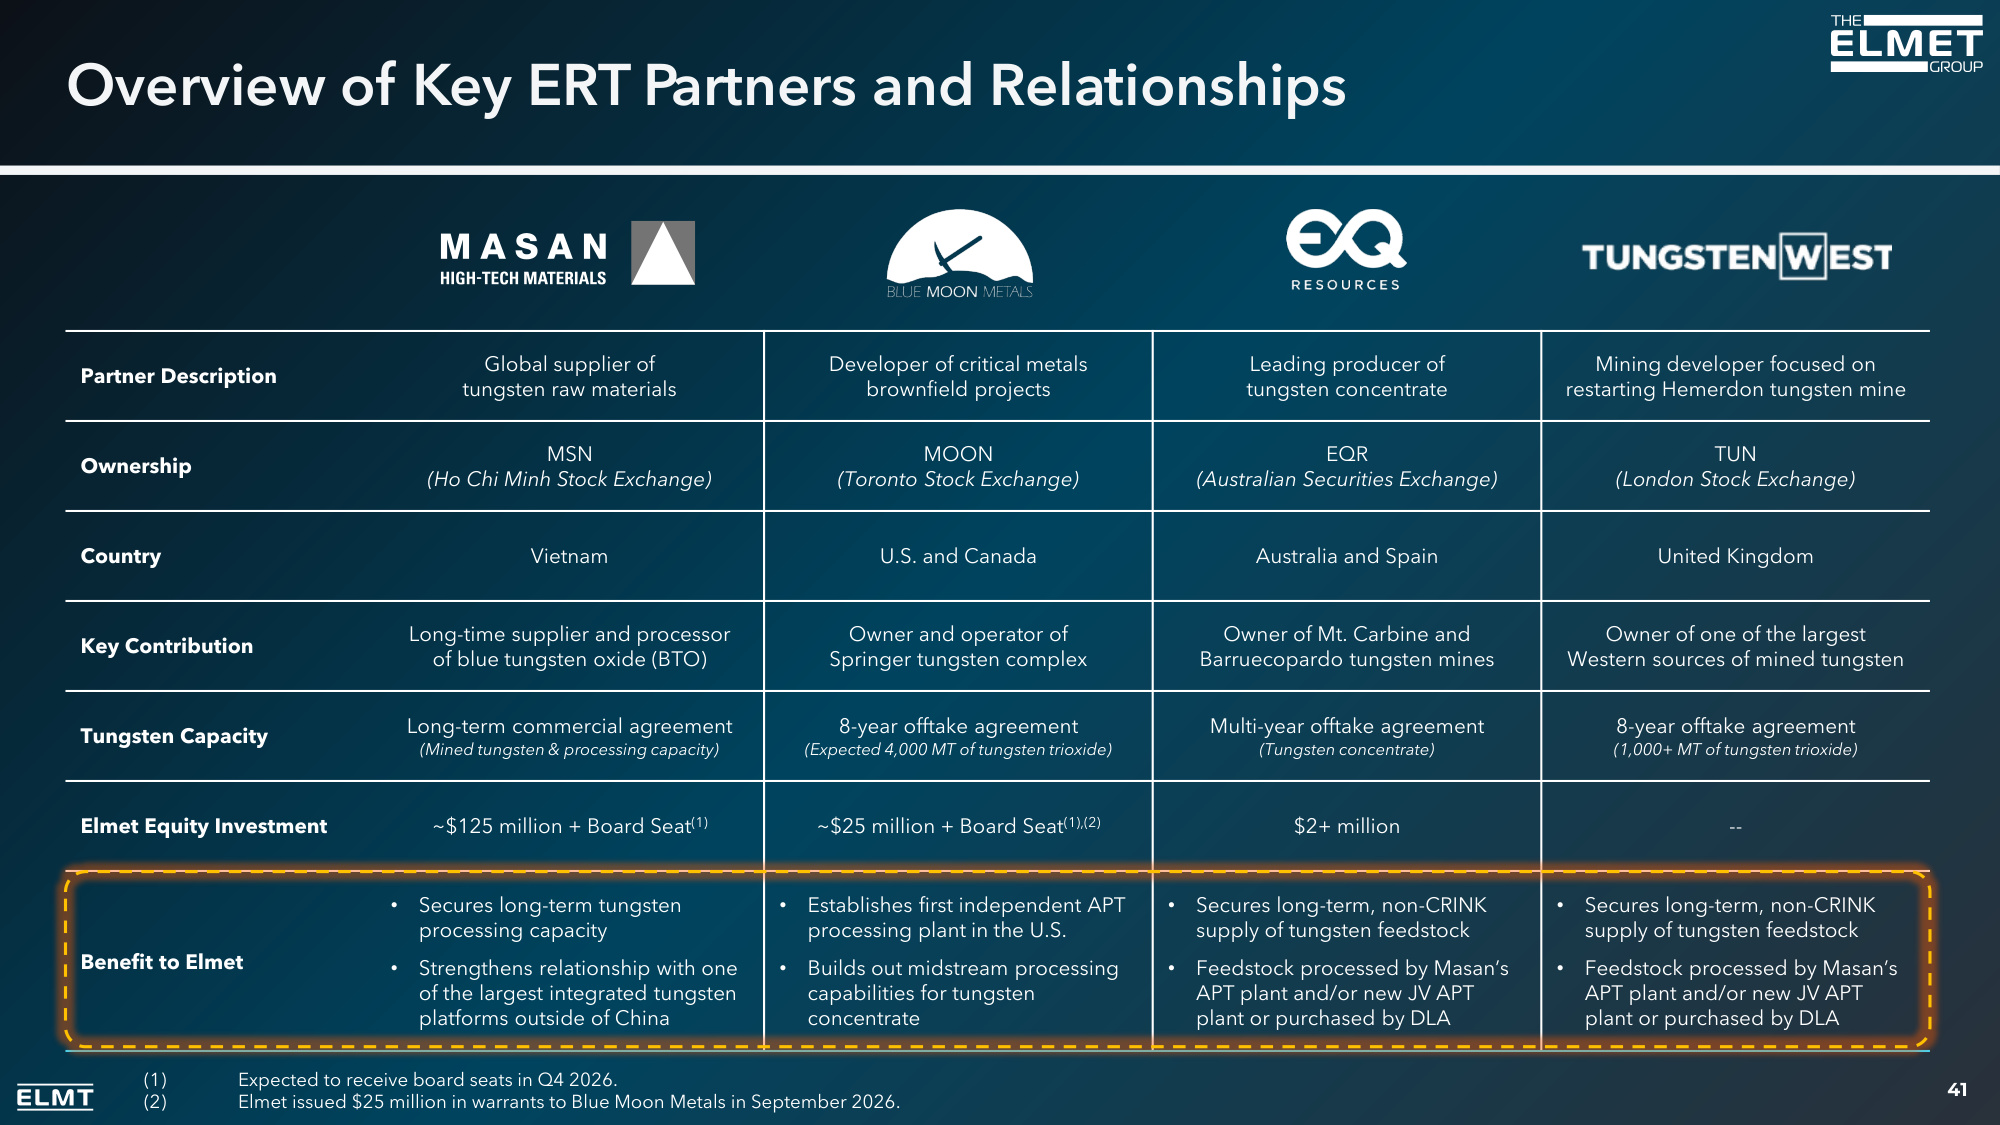
Overview of Key ERT Partners and Relationships Partner Description Global supplier of tungsten raw materials Developer of critical metals brownfield projects Leading producer of tungsten concentrate Mining developer focused on restarting Hemerdon tungsten mine Ownership MSN (Ho Chi Minh Stock Exchange) MOON (Toronto Stock Exchange) EQR (Australian Securities Exchange) TUN (London Stock Exchange) Country Vietnam U.S. and Canada Australia and Spain United Kingdom Key Contribution Long-time supplier and processor of blue tungsten oxide (BTO) Owner and operator of Springer tungsten complex Owner of Mt. Carbine and Barruecopardo tungsten mines Owner of one of the largest Western sources of mined tungsten Tungsten Capacity Long-term commercial agreement (Mined tungsten & processing capacity) 8-year offtake agreement (Expected 4,000 MT of tungsten trioxide) Multi-year offtake agreement (Tungsten concentrate) 8-year offtake agreement (1,000+ MT of tungsten trioxide) Elmet Equity Investment ~$125 million + Board Seat(1) ~$25 million + Board Seat(1),(2) $2+ million -- Benefit to Elmet • Secures long-term tungsten processing capacity • Strengthens relationship with one of the largest integrated tungsten platforms outside of China • Establishes first independent APT processing plant in the U.S. • Builds out midstream processing capabilities for tungsten concentrate • Secures long-term, non-CRINK supply of tungsten feedstock • Feedstock processed by Masan's APT plant and/or new JV APT plant or purchased by DLA • Secures long-term, non-CRINK supply of tungsten feedstock • Feedstock processed by Masan's APT plant and/or new JV APT plant or purchased by DLA 41 (1) Expected to receive board seats in Q4 2026. (2) Elmet issued $25 million in warrants to Blue Moon Metals in September 2026.
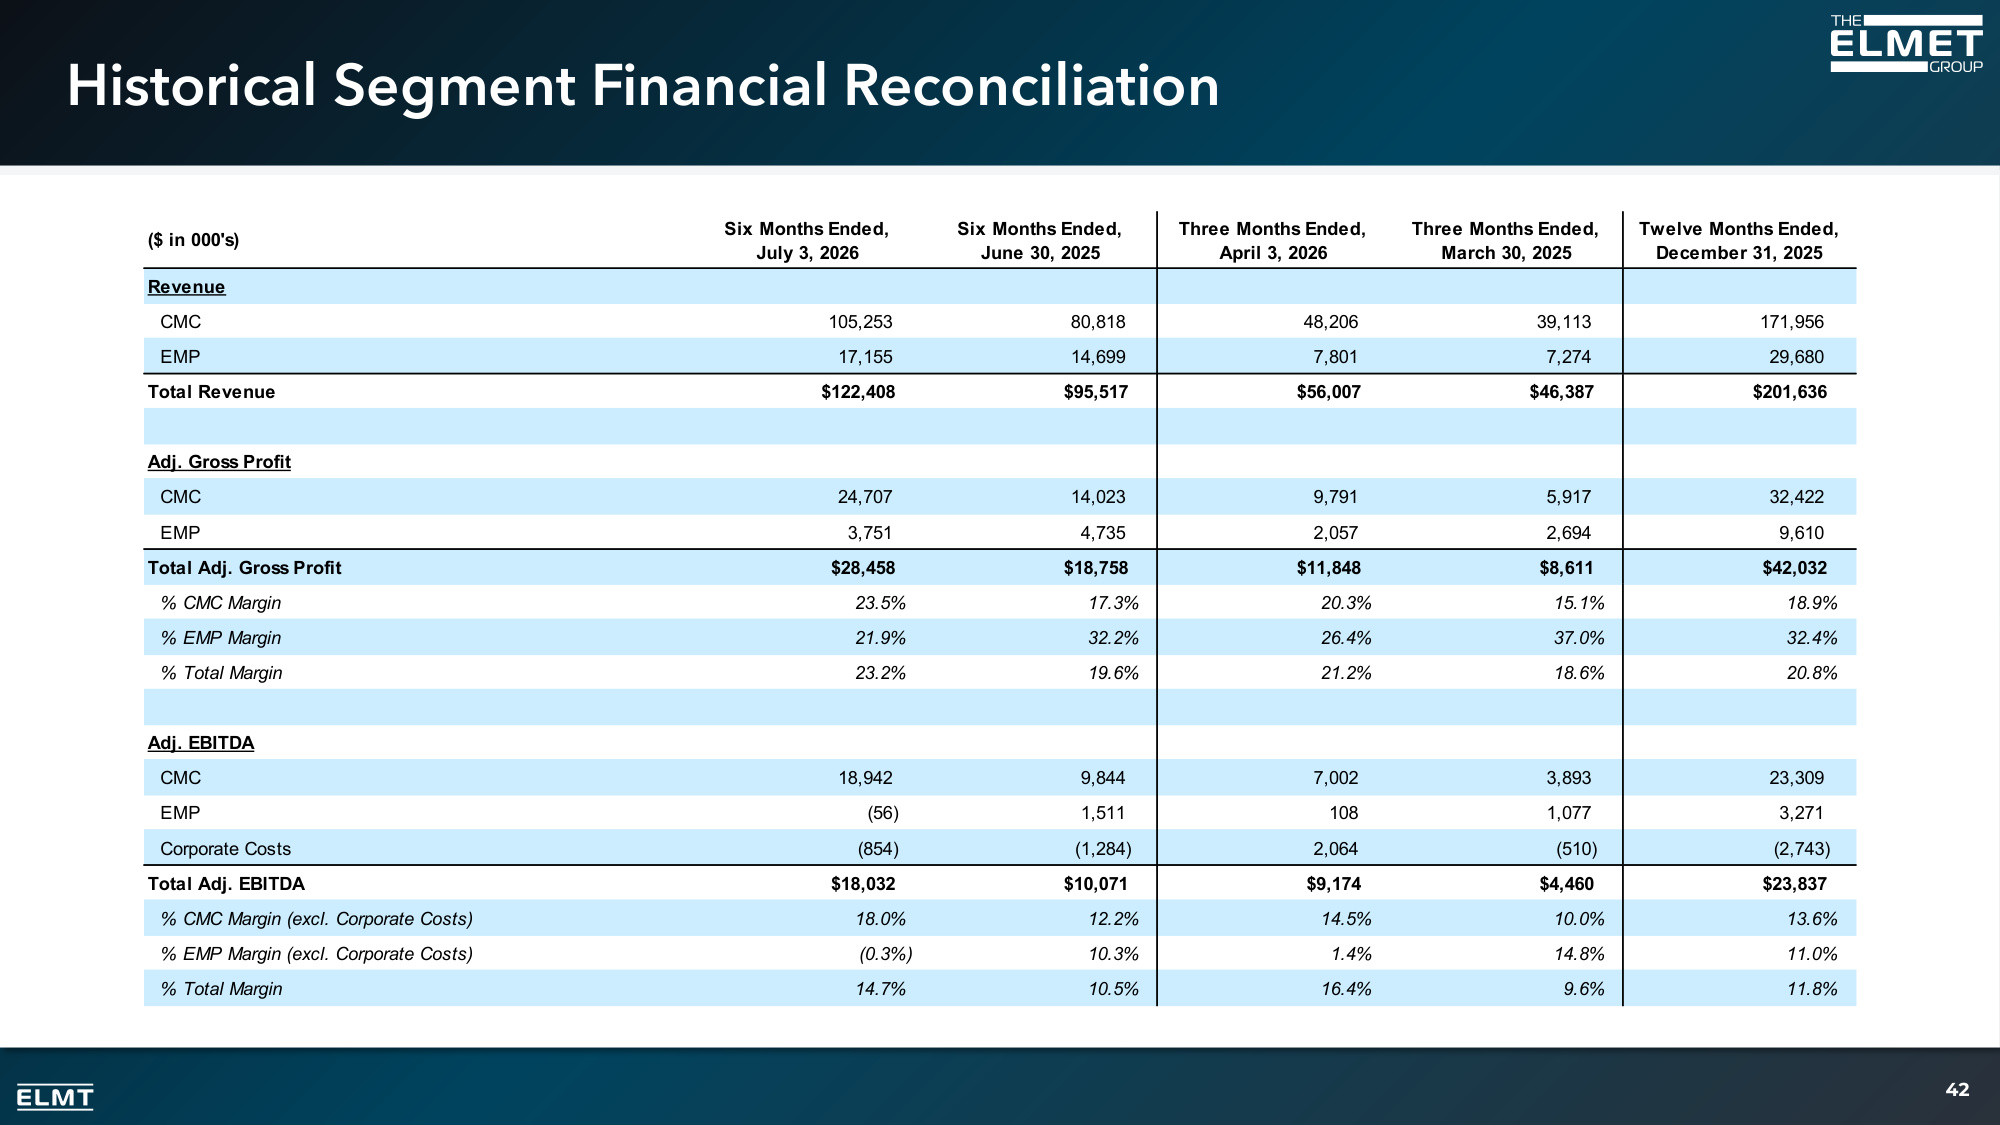
Historical Segment Financial Reconciliation 42 ($ in 000's) Six Months Ended, July 3, 2026 Six Months Ended, June 30, 2025 Three Months Ended, April 3, 2026 Three Months Ended, March 30, 2025 Twelve Months Ended, December 31, 2025 Revenue CMC 105,253 80,818 48,206 39,113 171,956 EMP 17,155 14,699 7,801 7,274 29,680 Total Revenue $122,408 $95,517 $56,007 $46,387 $201,636 Adj. Gross Profit CMC 24,707 14,023 9,791 5,917 32,422 EMP 3,751 4,735 2,057 2,694 9,610 Total Adj. Gross Profit $28,458 $18,758 $11,848 $8,611 $42,032 % CMC Margin 23.5% 17.3% 20.3% 15.1% 18.9% % EMP Margin 21.9% 32.2% 26.4% 37.0% 32.4% % Total Margin 23.2% 19.6% 21.2% 18.6% 20.8% Adj. EBITDA CMC 18,942 9,844 7,002 3,893 23,309 EMP (56) 1,511 108 1,077 3,271 Corporate Costs (854) (1,284) 2,064 (510) (2,743) Total Adj. EBITDA $18,032 $10,071 $9,174 $4,460 $23,837 % CMC Margin (excl. Corporate Costs) 18.0% 12.2% 14.5% 10.0% 13.6% % EMP Margin (excl. Corporate Costs) (0.3%) 10.3% 1.4% 14.8% 11.0% % Total Margin 14.7% 10.5% 16.4% 9.6% 11.8%
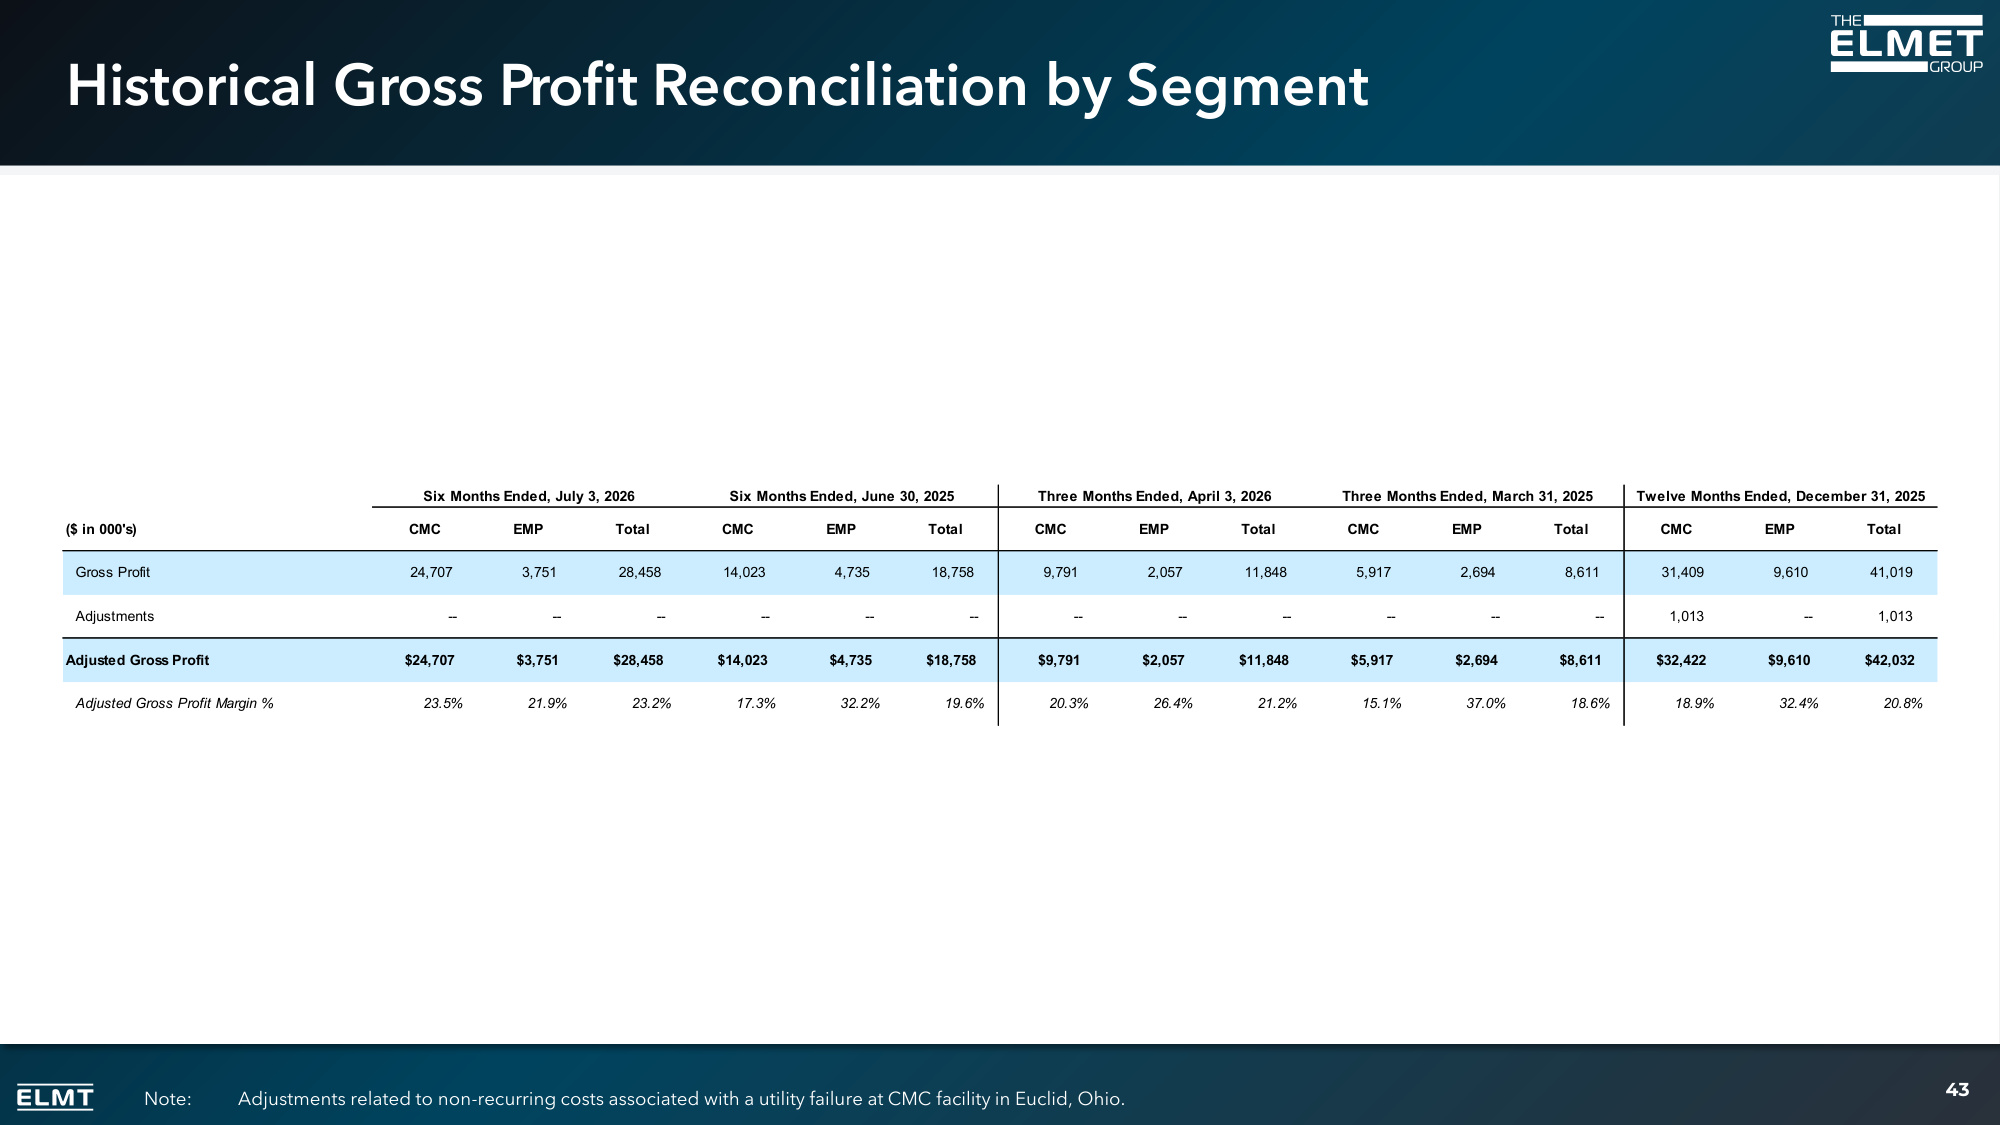
Historical Gross Profit Reconciliation by Segment 43 Note: Adjustments related to non-recurring costs associated with a utility failure at CMC facility in Euclid, Ohio. Six Months Ended, July 3, 2026 Six Months Ended, June 30, 2025 Three Months Ended, April 3, 2026 Three Months Ended, March 31, 2025 Twelve Months Ended, December 31, 2025 ($ in 000's) CMC EMP Total CMC EMP Total CMC EMP Total CMC EMP Total CMC EMP Total Gross Profit 24,707 3,751 28,458 14,023 4,735 18,758 9,791 2,057 11,848 5,917 2,694 8,611 31,409 9,610 41,019 Adjustments -- -- -- -- -- -- -- -- -- -- -- -- 1,013 -- 1,013 Adjusted Gross Profit $24,707 $3,751 $28,458 $14,023 $4,735 $18,758 $9,791 $2,057 $11,848 $5,917 $2,694 $8,611 $32,422 $9,610 $42,032 Adjusted Gross Profit Margin % 23.5% 21.9% 23.2% 17.3% 32.2% 19.6% 20.3% 26.4% 21.2% 15.1% 37.0% 18.6% 18.9% 32.4% 20.8%
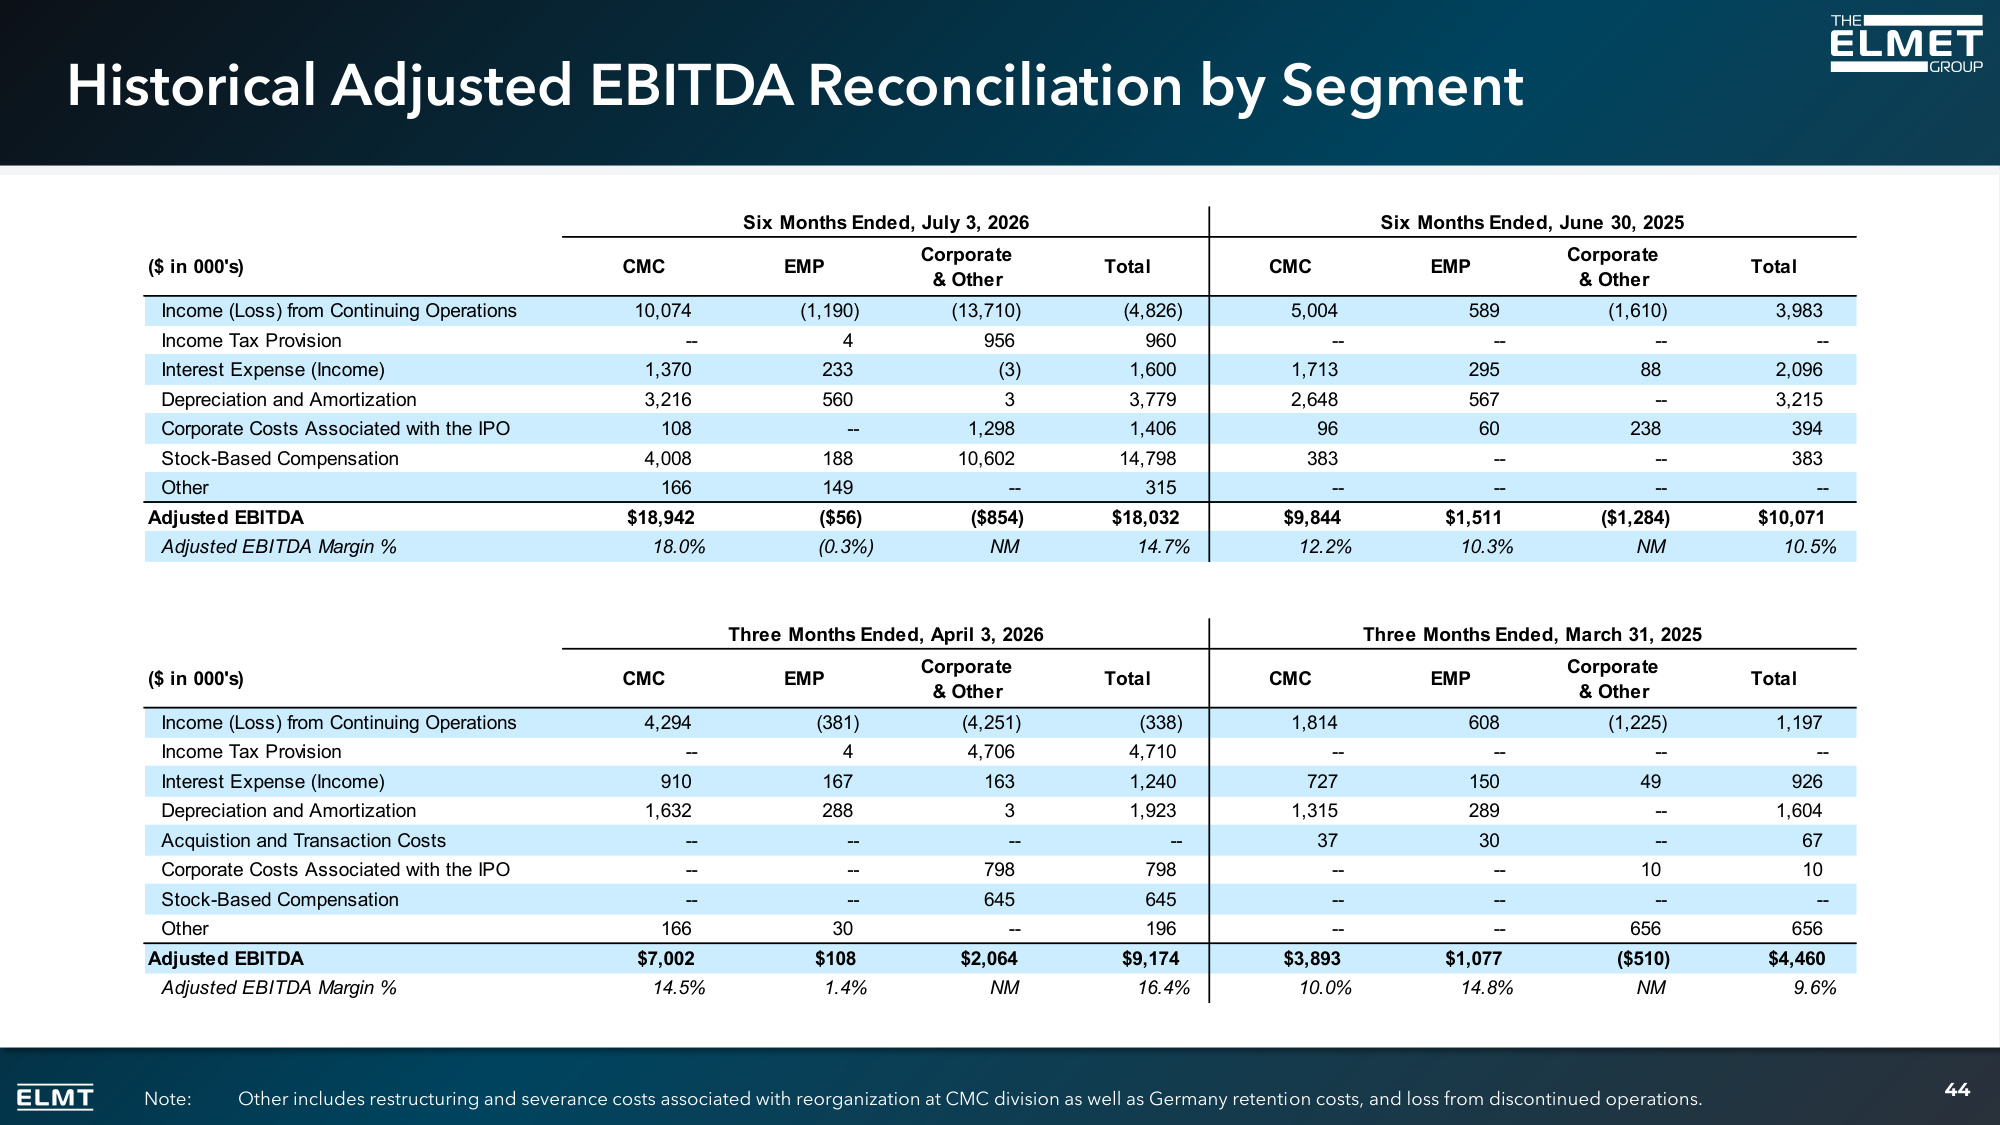
Historical Adjusted EBITDA Reconciliation by Segment Six Months Ended, July 3, 2026 Six Months Ended, June 30, 2025 ($ in 000's) CMC EMP Corporate & Other Total CMC EMP Corporate & Other Total Income (Loss) from Continuing Operations 10,074 (1,190) (13,710) (4,826) 5,004 589 (1,610) 3,983 Income Tax Provision -- 4 956 960 -- -- -- -- Interest Expense (Income) 1,370 233 (3) 1,600 1,713 295 88 2,096 Depreciation and Amortization 3,216 560 3 3,779 2,648 567 -- 3,215 Corporate Costs Associated with the IPO 108 -- 1,298 1,406 96 60 238 394 Stock-Based Compensation 4,008 188 10,602 14,798 383 -- -- 383 Other 166 149 -- 315 -- -- -- -- Adjusted EBITDA $18,942 ($56) ($854) $18,032 $9,844 $1,511 ($1,284) $10,071 Adjusted EBITDA Margin % 18.0% (0.3%) NM 14.7% 12.2% 10.3% NM 10.5% Three Months Ended, April 3, 2026 Three Months Ended, March 31, 2025 ($ in 000's) CMC EMP Corporate & Other Total CMC EMP Corporate & Other Total Income (Loss) from Continuing Operations 4,294 (381) (4,251) (338) 1,814 608 (1,225) 1,197 Income Tax Provision -- 4 4,706 4,710 -- -- -- -- Interest Expense (Income) 910 167 163 1,240 727 150 49 926 Depreciation and Amortization 1,632 288 3 1,923 1,315 289 -- 1,604 Acquistion and Transaction Costs -- -- -- -- 37 30 -- 67 Corporate Costs Associated with the IPO -- -- 798 798 -- -- 10 10 Stock-Based Compensation -- -- 645 645 -- -- -- -- Other 166 30 -- 196 -- -- 656 656 Adjusted EBITDA $7,002 $108 $2,064 $9,174 $3,893 $1,077 ($510) $4,460 Adjusted EBITDA Margin % 14.5% 1.4% NM 16.4% 10.0% 14.8% NM 9.6% Note: Other includes restructuring and severance costs associated with reorganization at CMC division as well as Germany retention costs, and loss from discontinued operations. 44
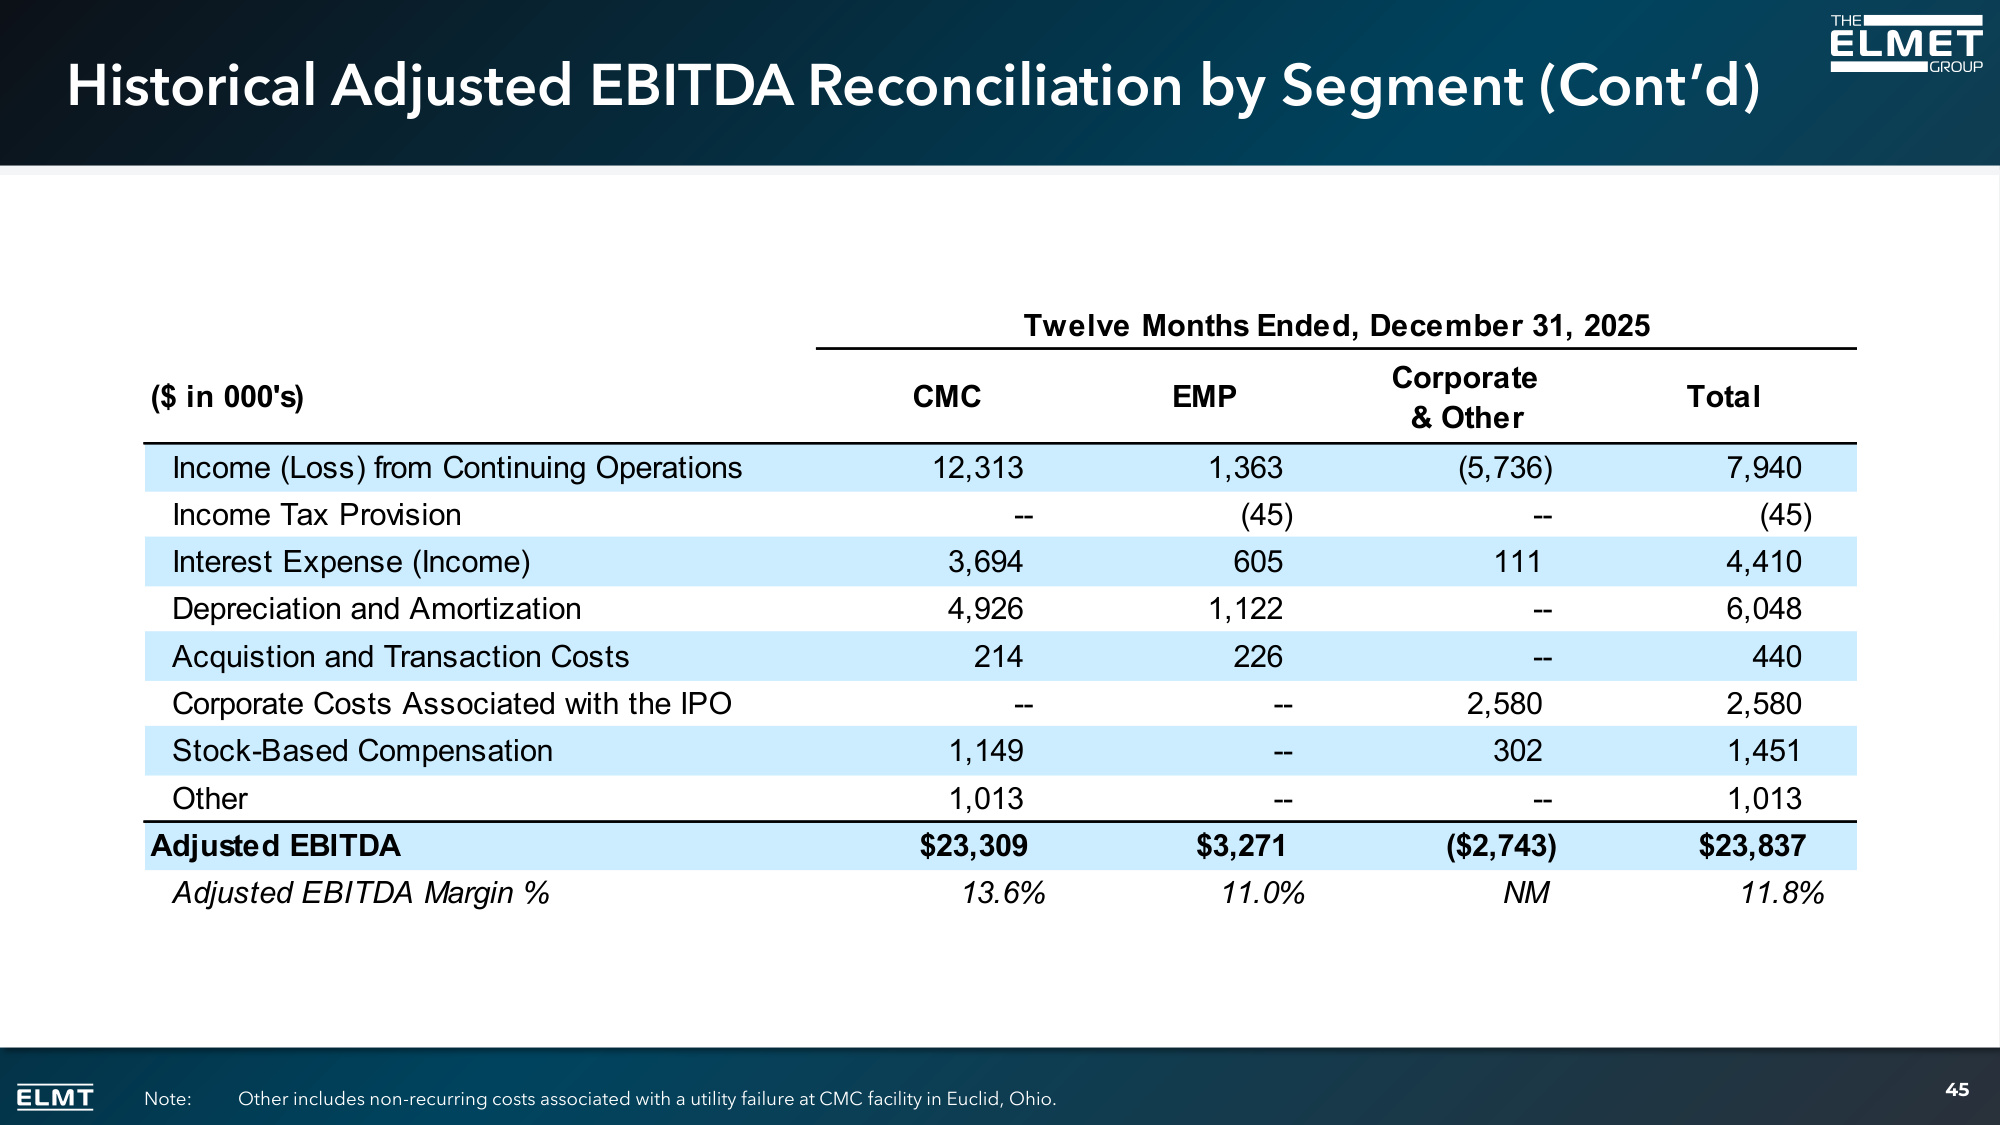
Historical Adjusted EBITDA Reconciliation by Segment (Cont'd) 45 Twelve Months Ended, December 31, 2025 ($ in 000's) CMC EMP Corporate & Other Total Income (Loss) from Continuing Operations 12,313 1,363 (5,736) 7,940 Income Tax Provision -- (45) -- (45) Interest Expense (Income) 3,694 605 111 4,410 Depreciation and Amortization 4,926 1,122 -- 6,048 Acquistion and Transaction Costs 214 226 -- 440 Corporate Costs Associated with the IPO -- -- 2,580 2,580 Stock-Based Compensation 1,149 -- 302 1,451 Other 1,013 -- -- 1,013 Adjusted EBITDA $23,309 $3,271 ($2,743) $23,837 Adjusted EBITDA Margin % 13.6% 11.0% NM 11.8% Note: Other includes non-recurring costs associated with a utility failure at CMC facility in Euclid, Ohio.
Critical Materials Critical Processes Critical Engineering Critical Manufacturing The Elmet Group | www.theelmetgroup.com